It's 3:14 AM. I know this because I just stared at the glowing red numbers on my nightstand clock for the twentieth time. My heart is pounding against my ribs. Why? Because I just ran a retirement calculator in my head and realized that if I max out my 403(b) during residency, I might be accidentally sabotaging my student loan repayment.
Or wait. Am I?
Before deciding on your strategy, it is worth reviewing why maxing every account isn't always optimal for physician retirement to ensure you aren't over-extending your liquidity.
The panic spirals. Six figures in medical school debt is a physical weight on my chest. It sits there every single day. But ignoring compound interest in my 20s feels like financial suicide. I'm caught in a brutal tug-of-war between my past decisions and my future security.
This is what I call the 'Student Loan Payment Trap'. We're constantly told to save for retirement, to capture the employer match, to max out our tax-advantaged accounts. But we're also enrolled in Income-Driven Repayment (IDR) plans like SAVE or PAYE. These plans base our monthly payments on our Adjusted Gross Income (AGI). So, the 3:00 AM panic sets in: If I shelter money in a 403(b), does the government think I'm hiding assets? Does it artificially inflate my loan payments because they know I have retirement cash? What if I'm playing right into a trap that keeps me in debt longer?
Please remember that this article is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Because everyone's situation is unique and figures vary, you should always consult a qualified professional before making major financial decisions.
You can also explore 7 steps to time your 403(b) vesting with student loan payoff to better align your career goals with your financial reality.
The Math Behind the Madness: How AGI Affects Your IBR
Let's kill the worst-case scenario right now. Take a deep breath. Maxing your 403(b) does not inflate your student loan payments. It actually does the exact opposite.
I used to think the Department of Education had a crystal ball. I imagined some bureaucratic algorithm looking at my gross salary, seeing my 403(b) contributions, and saying, "Aha! They have extra cash! Let's raise their monthly bill."
That's not how it works. IDR plans use your Adjusted Gross Income (AGI), not your gross income. Your AGI is your gross income minus specific deductions, and pre-tax retirement contributions (like a traditional 403(b) or 401(k)) are one of the most powerful deductions you have.
Here is the secret advantage that keeps me sane: When you contribute to a pre-tax 403(b), you lower your AGI. When your AGI drops, your "discretionary income" drops. When your discretionary income drops, your required monthly payment on your IDR plan drops.
You aren't hiding money. You are legally and mathematically shrinking the income the government uses to calculate your student loan bill.
Let's look at the actual numbers. If you are a resident making around $65,000 a year, your AGI dictates your SAVE or PAYE payment. By increasing your 403(b) contribution, you directly shave dollars off your monthly loan obligation.
But here is the fear that always creeps back in: Am I just deferring my debt? Am I just kicking the can down the road while interest accrues?
It feels like it, doesn't it? When your loan balance grows because your IDR payment doesn't cover the interest, it feels like you're failing. But you aren't. You are optimizing. You are taking the cash you would have overpaid on a low-interest loan and putting it into an account that grows tax-deferred. If you are on a forgiveness track (like PSLF), those extra payments you would have made are literally burning cash. If you aren't on a forgiveness track, the tax savings and market growth heavily outweigh the subsidized or low interest on your student loans.
You are saving yourself. The math proves it. But the anxiety doesn't always care about math.
The Worst-Case Scenario: What If I Max Out and Can't Eat?
Okay, the math works. But what if I put $23,000 into my 403(b) and then my car's transmission explodes? What if I get sick? What if I need cash now and it's all locked up in a retirement account until I'm 59 and a half?
This is the liquidity nightmare. Balancing retirement 'must-haves' with immediate liquidity needs is the hardest part of residency. You are living on a shoestring budget. Every dollar has a job, and if you assign too many dollars to your 403(b), you might starve your checking account.
We need to talk about the fallacy of 'paying off debt first'. A lot of residents I talk to are obsessed with killing their debt. They want to throw every spare cent at their loans because the psychological burden is so heavy. I get it. Debt feels bad. Being debt-free feels good.
But ignoring the time value of money is a massive mistake. If your student loans are sitting at 4% or 5% interest, and the stock market historically averages 8% to 10%, prioritizing your loans over your 403(b) is mathematically dumb. It keeps me up at night because the debt feels like an emergency, but the numbers suggest the tax break and compound growth are vastly superior. You can never get back the years of compound growth you miss in your 20s. Never.
But that doesn't mean you should blindly max out your 403(b) if it leaves you vulnerable. Financial health is about balance. You shouldn't sacrifice your sanity today for a retirement goal that ignores your immediate cost of living.
You have to stress-test your budget. When is it okay to pause contributions? When your emergency fund is empty. When you are relying on credit cards to buy groceries. When the sheer stress of being cash-poor is making you miserable.
Here is how I force myself to make the decision without spiraling into a panic attack:
If you can't cover your basic living expenses, pause the 403(b). Survival comes first. But if your basic needs are met and your debt interest is relatively low, you need to push through the discomfort and fund your retirement. The liquidity fear is real, but the poverty-in-old-age fear should be terrifying you more.
Final Verdict: Reclaiming Your Financial Sanity
Stop the 3 AM spiraling. I say this to myself as much as I'm saying it to you.
Retirement savings during residency are almost always a net win. You get the immediate tax savings. You lower your AGI, which effectively reduces your monthly IDR student loan payments. And you capture the most valuable asset in finance: time in the market.
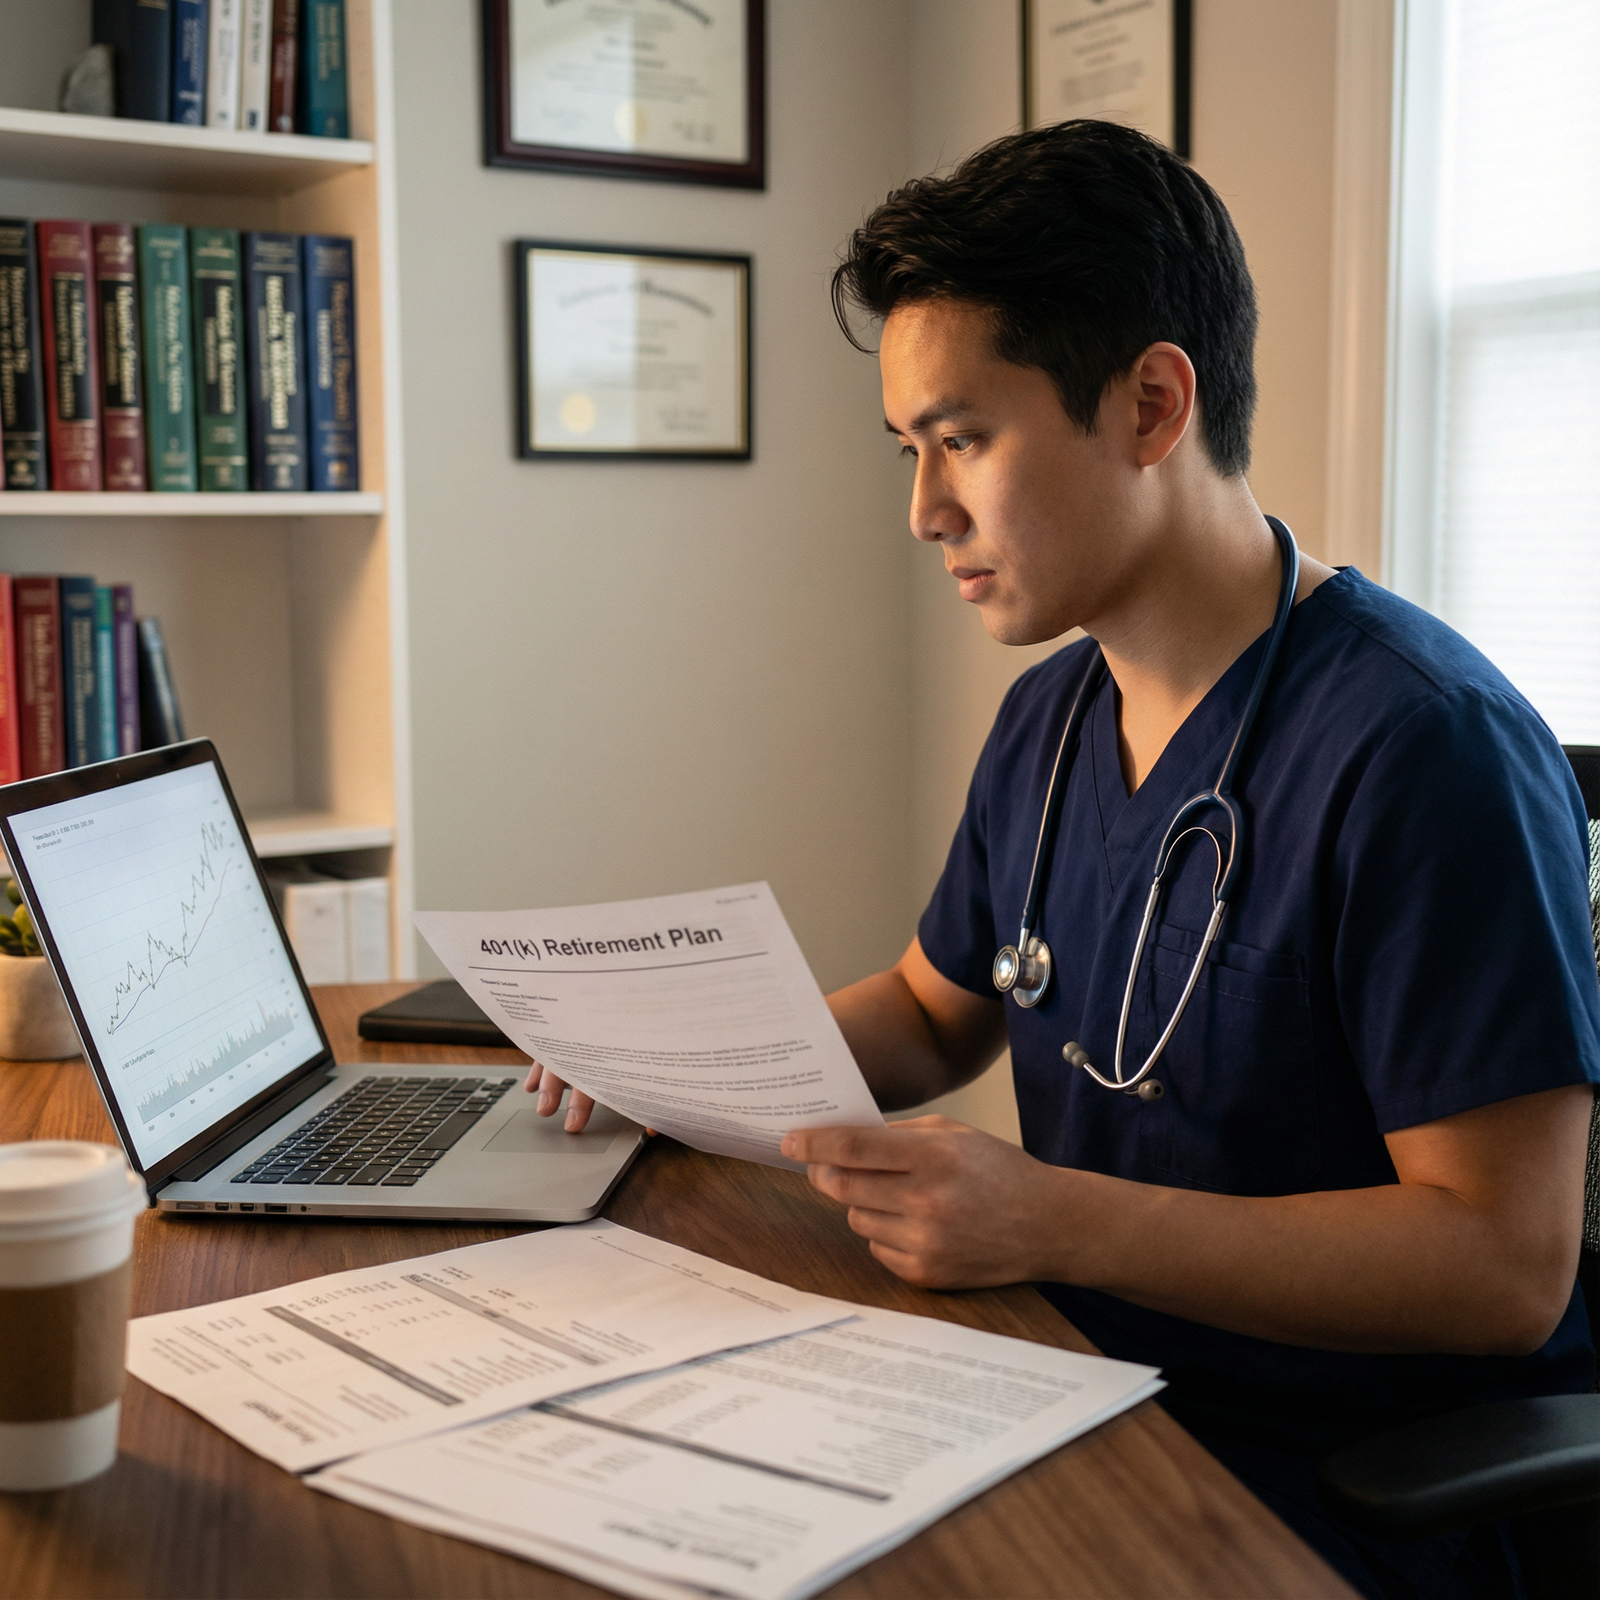
You have to stop 'what-if' spiraling and focus on consistent, small steps. You don't have to max out your 403(b) on day one of residency. Start with the employer match. Then bump it up by 1% every six months. Watch your AGI drop. Watch your student loan bill shrink. Watch your retirement balance grow.
The system is rigged to be confusing, and the sheer volume of debt we carry is objectively unfair. But you can beat it by playing the math, not the emotions.
Take a deep breath. You are going to be okay.
Call to Action: Stop guessing and start sleeping through the night. Download our free Residency Budgeting Spreadsheet to map out your exact AGI, project your IDR payments, and find your perfect 403(b) contribution rate without going broke. Click here to get it and breathe easier.