You moonlight. You make an extra $18,000 covering nights at the community ED. And suddenly your senior resident tells you your income-driven repayment is going to spike $300 a month. So was it even worth it?
No. That is not how this works. At least, not automatically.
This myth persists because residents understand medicine better than they understand federal loan mechanics. And frankly, the financial aid office does a terrible job explaining it.
Let me break this down specifically.
This article is for educational purposes only and is not financial advice, not legal advice, and not tax advice. All figures vary based on your loans, income, and filing status, so consult a qualified professional before you make decisions based on this information.
Introduction
The core misunderstanding is simple: residents think IDR payments react instantly to income like a payroll tax. They do not. Your payment is not based on what you earned last week. It is based on what your tax return said you earned last year, or even two years ago depending on your recertification date.
Here is why this matters to your medical career. Moonlighting is some of the highest-yield time you have in residency. $120-$150 per hour, pure clinical revenue, often with minimal administrative drag. If you avoid it because you think the government will claw back 10% of it through SAVE or PAYE, you are leaving real money on the table. I have seen residents turn down 20-hour weekend shifts worth $3,000 because they thought their student loan payment would increase by $250. The math never worked that way.
Income-driven repayment, SAVE, PAYE, IBR, ICR, uses Adjusted Gross Income. Not gross pay. Not moonlighting cash. AGI. That is a tax concept. And tax concepts can be managed. Timing can be managed. Filing status can be managed.
If you are chasing Public Service Loan Forgiveness, this distinction is everything. You want your payments low during residency to maximize forgiveness. But a small, controlled increase in payment now is not a reason to forfeit moonlighting income that can keep you from credit card debt, build an emergency fund, or let you fund a Roth IRA while you still qualify.
The Core Challenge
The pitfall is not moonlighting itself. The pitfall is misunderstanding the lag, the lookback, and the leak.
The Lag. Your IDR recertification date determines which tax return servicers see. Let's say you certified in October 2024 using your 2023 tax return. That payment stays locked until October 2025. If you start moonlighting aggressively in January 2025, your servicer does not know. Does not care. Your 2025 income will not hit your IDR calculation until you recertify in October 2025 with your 2024 return, or, if you file an extension, potentially until late 2025 with that same 2024 return. That is a 9 to 21-month delay.
Residents get this backwards. They think: I moonlight now, I pay more now. Reality: you moonlight now, you might pay more next year. That float is valuable. Inflation alone favors paying later.
The Lookback. When you do recertify, what do they see? AGI on Form 1040, line 11. Not your W-2 box 1 total if you have pre-tax deductions. This is where moonlighting income gets filtered.
Scenario I saw last year: PGY-3 internal medicine resident, base $68k, moonlighting $22k as 1099 independent contractor working urgent care. Gross increase: 32%. AGI increase: $8,400. How? She contributed the max to her 403(b), $23,000 in 2024, plus $4,000 to traditional IRA, she deducted $6,500 of legitimate business expenses for moonlighting (mileage, malpractice tail for moonlighting, licenses, phone), and she contributed $5,000 to a Solo 401(k) from the 1099 income. Her actual IDR increase? About $70/month. On $22k extra earnings.
If she had been a W-2 moonlighter with no deductions, the impact would have been higher. Still not dollar-for-dollar. But the 1099 path gave her leverage.
The Leak: Self-certification and filing status traps.
Three mistakes that actually do force higher payments when moonlighting:
Recertifying early when you should not. You are NOT required to report income increases mid-year for SAVE, PAYE, IBR unless you want to. Your obligation is to recertify annually. If you voluntarily log into studentaid.gov and update income right after a big moonlighting month, you triggered the increase yourself. Stop doing that.
Switching from Married Filing Jointly to Married Filing Separately incorrectly. Many residents file separately to exclude spousal income from IDR. That works for PAYE and SAVE, at least under current rules, but filing separately kills your ability to do Roth IRA contributions directly, wipes out student loan interest deduction, and often costs more in taxes than it saves in payments. I have run these calculations for dual-physician couples where filing separately saved $400/month in loan payments but cost $9,000 extra in taxes. Bad trade.
Not using pre-tax vehicles. This is the biggest one. Every dollar you put in a traditional 403(b), 457(b), HSA, or, if you are 1099, Solo 401(k) reduces AGI. Your hospital 403(b) limit is independent of your moonlighting retirement options. Yes, you can do both. Most residents do not.
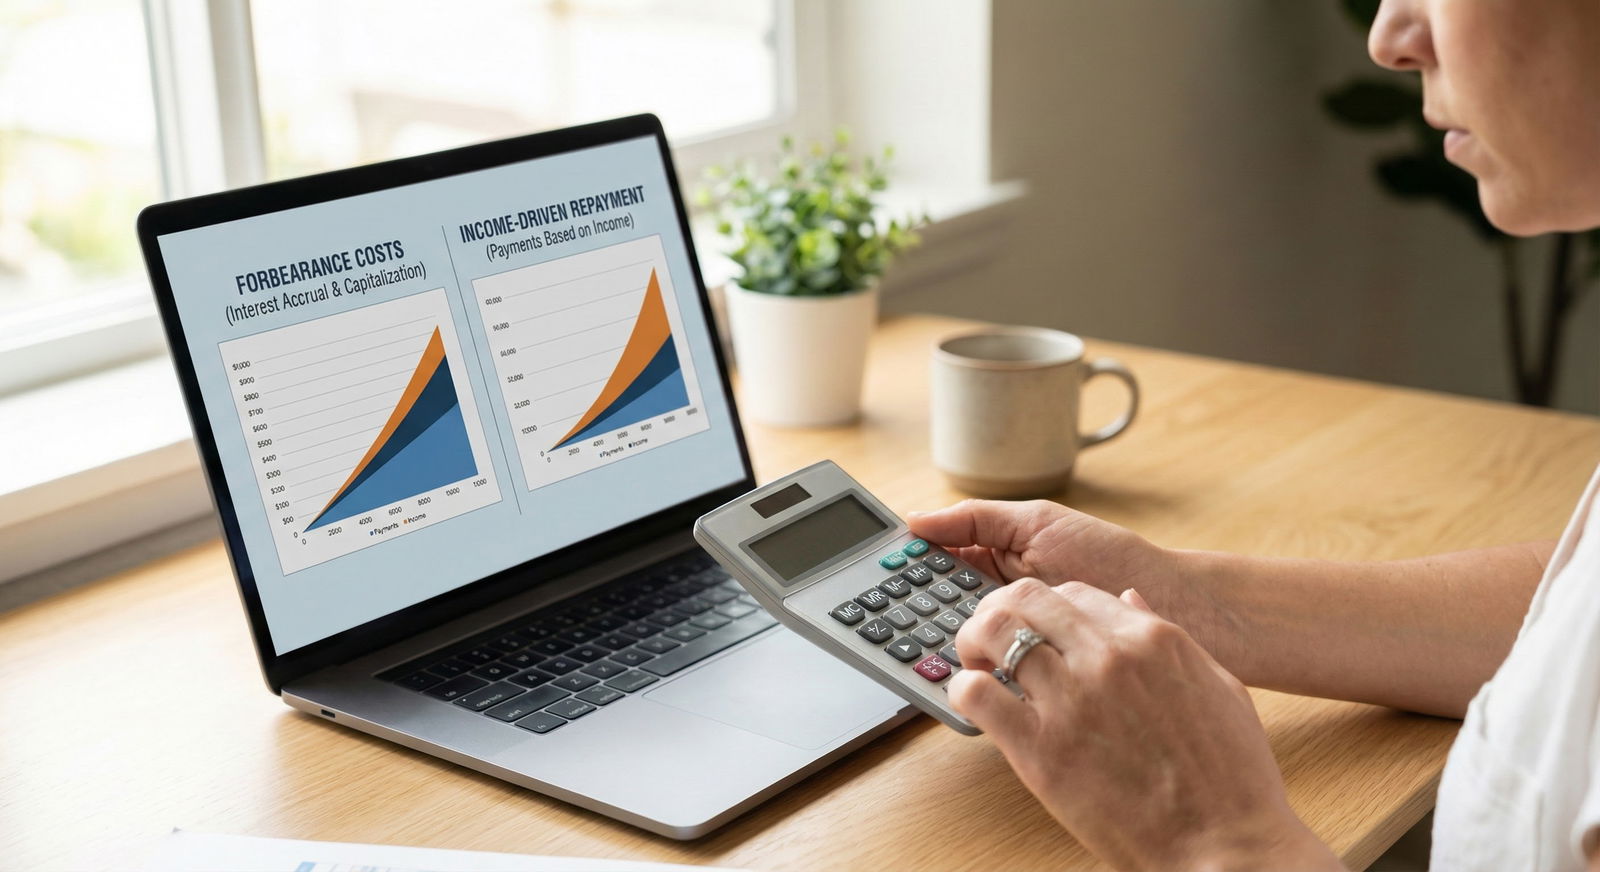
Look at the timeline. The income you earn today is insulated. The system is backward-looking by design. Use that.
Also, understand your specific IDR. PAYE caps payments at the 10-year standard repayment amount. IBR (old borrower) does not cap if you are no longer in partial financial hardship. SAVE, when it is fully implemented, had no cap but a higher income exemption, 225% of poverty line. That matters. A resident earning $85k with $22k moonlighting under SAVE might pay less than under IBR-old because of that exemption, even with more income.
Do not let anyone tell you "all IDR is 10%." Wrong. SAVE was 5% for undergrad, 10% for grad. PAYE is 10%. IBR is 10% or 15% depending on borrower date. The percentage matters when you calculate the true cost of moonlighting.
Quick math you should actually do: (Additional AGI * IDR percentage) / 12 = monthly increase. If you moonlight $15k, but after $5k in pre-tax contributions your AGI only rises $10k, and you are on PAYE at 10%, that is $1,000 per year, or $83/month. You cleared $14,917. That is worth it.
Actionable Next Steps
Stop guessing. Run your own numbers with a plan that matches the tax calendar, not the hospital calendar.
1. Identify your recertification date and your tax return year.
Log into your servicer. When is your annual recertification due? Write it down. If it is in September, remember: the return you will use is usually the one filed the prior spring. If you moonlight heavily between January and August, that income will not appear until next recertification if you file after that date. Intentional timing.
2. Structure your moonlighting correctly from day one.
W-2 moonlighting is simple. Taxes withheld, reports on W-2. No extra work. Slightly higher tax drag.
1099 moonlighting gives you options. You can deduct business expenses. You can open a Solo 401(k) or SEP IRA. You need to track mileage, actual miles to the moonlighting site, not your normal commute, track licensing fees, DEA for that site, scrubs if required only for moonlighting, etc. You need quarterly estimated taxes. More paperwork. Significantly more control over AGI.
I am not telling you which is better. I am telling you they affect IDR differently. If your moonlighting gig offers both, ask. The $2k you pay a CPA who understands physician 1099 work will save you multiples of that in AGI management.
3. Max pre-tax accounts in the right order.
Here is the hierarchy I tell residents who moonlight and want low IDR for PSLF:
First: 403(b) / 401(k) to match. Always. Second: HSA if you have HDHP eligibility. Triple tax advantaged. Reduces AGI. Third: 457(b) if your institution offers it. Another $23,000 of AGI sheltering in 2024, separate limit from 403(b). Many academic centers offer it. Most residents ignore it. Mistake. Fourth: If 1099, Solo 401(k), up to 20% of net self-employment income as employer contribution plus employee deferral if you have not already capped it elsewhere. Fifth: Traditional IRA only if you are eligible to deduct, income limits apply if you have workplace retirement plan.
This is not about being rich. This is about AGI suppression on purpose. You are not evading anything. You are using the tax code as written.
4. Model filing status every year, not once.
If you are married and your spouse earns significant income, run both joint and separate scenarios in January with a CPA or using tax software. Look at three numbers: total tax liability joint vs. separate, total IDR payments joint vs. separate for 12 months, and impact on forgiveness timeline. Add them. Pick the lower total cost. Sometimes that means you file separately during residency and jointly as an attending. That shift is normal.
5. Never recertify early unless you made less.
If your income dropped, you stopped moonlighting, spouse lost job, you had a baby and took unpaid leave, then yes, self-certify early to lower payment. If income went up, let the anniversary date arrive naturally. There is no penalty for waiting.
And a final point: SAVE is in legal limbo. As of my last check, forbearance and court challenges have paused some effects. Do not make a 5-year plan assuming SAVE rules stay exactly as proposed in 2023. Have a PAYE / IBR backup assumption. Your servicer will place you somewhere. Know which IDR you actually want if SAVE disappears.
Summary: Moonlighting does not automatically force higher IDR payments. The connection between what you earn at the bedside on Saturday and what your loan servicer charges you is indirect, delayed, and filterable through AGI.
Be prepared. Track your dates, know your AGI levers, and stop treating IDR like a real-time payroll tax.
Focus on high-yield areas. The biggest return is not the per-hour moonlighting rate. It is understanding that a $20,000 moonlighting year might cost you $600-$1,200 in IDR increases next year if managed well, versus $2,000-$3,000 if you do nothing. That difference is your Roth IRA, your emergency fund, or your ability to say no to the next bad moonlighting shift.
That is real money. Keep it.