What if you wake up tomorrow, walk up to the scrub sink, and realize your hands won't stop shaking? Or worse, what if a sudden neurological diagnosis, a brutal car accident, or crippling clinical depression hits out of nowhere and completely destroys your ability to practice medicine?
It terrifies me. I lie awake at night thinking about this exact scenario. You spend over a decade sacrificing your youth, taking on hundreds of thousands of dollars in student loans, working grueling 80-hour weeks, all to build a career that rests entirely on your physical and mental ability to perform. If your health breaks, the whole tower collapses. Losing your clinical career isn't just about losing a paycheck. It feels like losing your entire identity, your lifestyle, and the baseline financial security you worked so hard to achieve.
This article is for educational purposes only and is not financial advice, not legal advice, and not tax advice. Exact figures vary based on specialty and geography, so always consult a qualified professional to audit your personal situation.
Understanding the Risks: What "Can't Work" Means for Physicians
When doctors picture career-ending events, they usually imagine dramatic trauma, a surgeon losing a hand in a crash. But the reality is far more subtle and creeping. Severe burnout, mental health exhaustion, spine degradation from leaning over patients, or a sudden loss of medical licensure due to an unexpected administrative nightmare can sideline you just as fast.
When you can't practice, the financial hit is immediate and brutal. Your multi-six-figure salary doesn't just dip, it drops to zero. That means employer 401(k) matches stop instantly. Health insurance benefits vanish. Meanwhile, your personal expenses don't care that you're sick; mortgage payments, student loans, private school tuition, and basic living costs keep coming every single month.
To make matters worse, your out-of-pocket spending usually spikes. Specialized medical care, rehabilitation, therapy, and out-of-network treatments drain whatever liquid cash you have left. You aren't just losing your earning years, you are actively burning through your past earnings just to survive.
Portfolio Vulnerabilities: Why Traditional Investments May Fail You
Most doctors think their investment portfolios will save them if things go wrong. But traditional portfolios are notoriously vulnerable when forced to support you ahead of schedule.
First, there's market timing risk. If a health crisis forces you to stop working during a severe market crash, you'll be forced to sell stocks at a 30% or 40% discount just to pay groceries and property taxes. Selling depreciated assets permanently locks in your losses and guts your long-term wealth compounding engine.
Second, doctors routinely fall into the trap of over-concentration. Is your net worth tied up in your medical practice's equity, local real estate where your clinic operates, or employer stock? If you can no longer practice, your clinic's value plummets. Your practice equity becomes worthless at the exact moment you need cash the most.
Then consider liquidity and inflation. Real estate and private equity are illiquid, you can't sell a piece of an ambulatory surgery center in three days to cover rent. And if you flee to cash or fixed income out of pure panic, high inflation will quietly erode your purchasing power year after year. Add regulatory shifts or lingering malpractice liability claims, and an unprotected portfolio can evaporate faster than you ever thought possible.
Protective Strategies: Building a Resilient Financial Fortress
If you want to sleep at night, you need to turn your portfolio into an impenetrable fortress long before disaster strikes. Hope is not a strategy. You need concrete financial defense.
Start with true asset diversification. Stop putting every spare dollar into your practice or local real estate. Broad-market, low-cost index funds, international equities, government treasury bonds, and diversified real estate investment trusts (REITs) give you exposure that isn't tied to your physical hands or your local healthcare market.
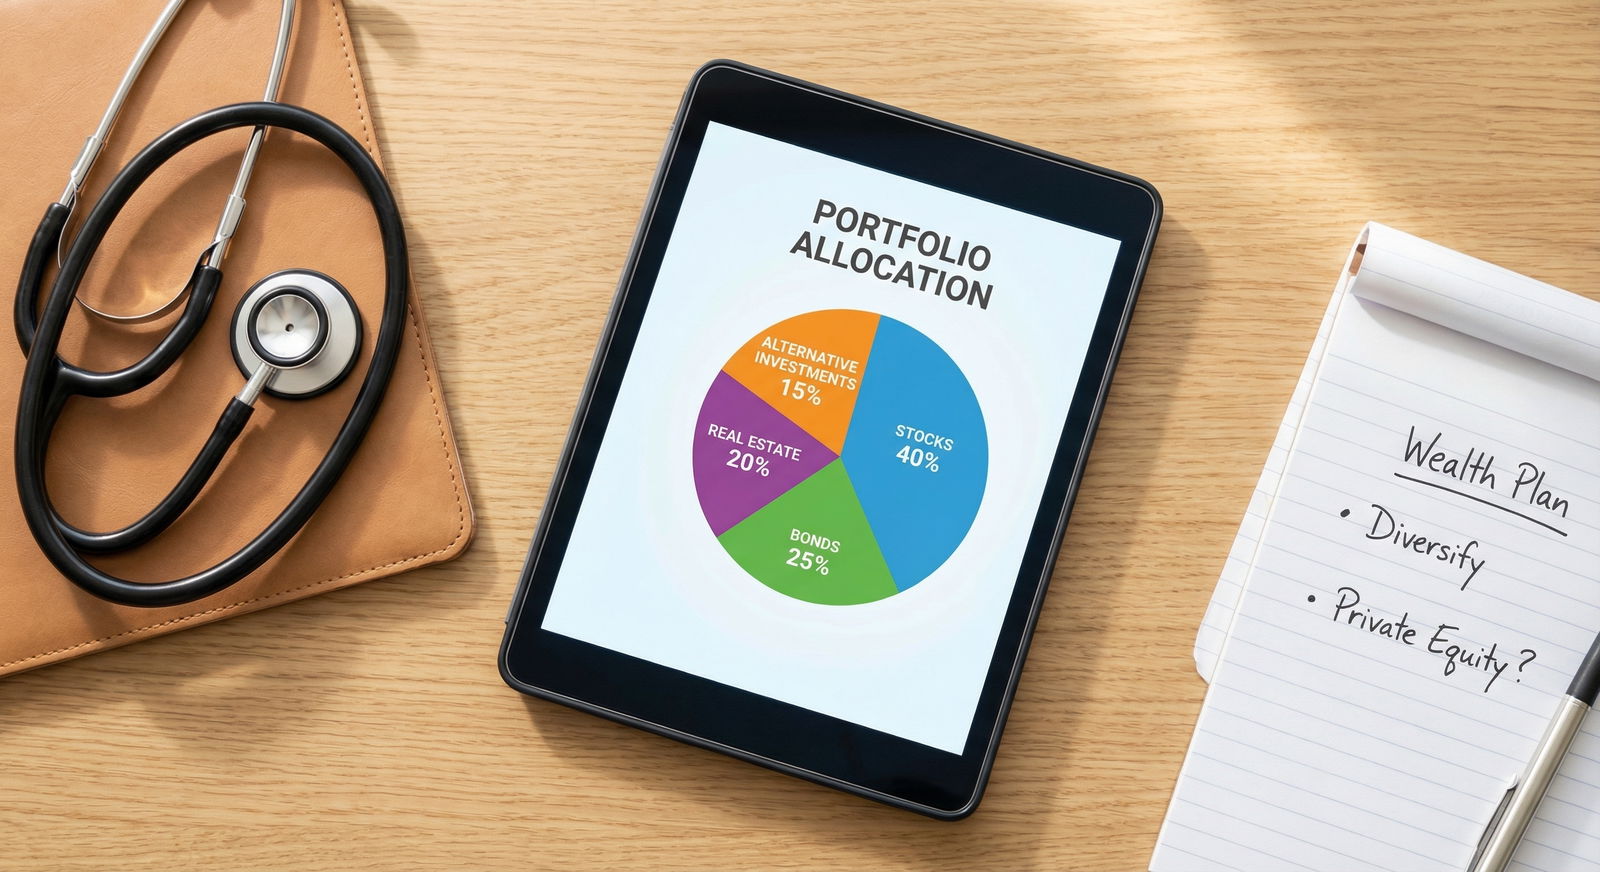
Next, you must build non-clinical income streams. Could you pivot to chart reviews, medical writing, teaching, consulting for biotech firms, or expert witness work? What about passive rental income from non-medical properties? The more income sources you have that don't require standing on your feet for ten hours, the safer you are.
Most importantly, buy true "Own-Occupation" disability insurance. Do not rely on generic group policies from your hospital; they are full of loopholes and can be canceled if you leave your job. An individual, specialty-specific, own-occupation policy pays out if you can no longer perform the specific duties of your specialty, even if you get a job teaching at a medical school. Pair this with Overhead Expense (OE) insurance if you own a private practice.
Finally, ignore the standard advice that says 3 to 6 months of living expenses in cash is enough. That is nowhere near enough peace of mind for a physician facing total career disruption. You need 12 to 18 months of cash reserves in a high-yield savings account or money market fund.
Action Plan: Step-by-Step Checklist to Safeguard Your Future
Don't wait until you get a terrifying lab result or feel your spine give out to start planning. Take these concrete steps immediately:
- Audit Your Disability Coverage Today: Open your disability policy right now. Look for the phrase "True Own-Occupation." If it says "Any Occupation" or lacks specialty protection, replace or supplement it immediately. Ensure it includes a Cost-of-Living Adjustment (COLA) rider to fight inflation.
- Shift Assets Out of Practice-Linked Investments: If more than 20% of your net worth is tied up in your practice, clinic building, or employer stock, trim it back. Redirect capital into liquid, broad-market index funds.
- Build the 12-18 Month Cash Runway: Calculate your exact monthly expenses, including mortgage, debt, and basic lifestyle costs. Multiply that by 18. Move that cash into an FDIC-insured, high-yield account. That money isn't for investing; it's your panic shield.
- Draft a Non-Clinical Contingency Plan: Write down three specific ways you could earn money using your medical degree without touching a patient. Keep contacts in medical consulting, legal chart review, or clinical research active.
Conclusion: Reassurance and Next Steps
It is terrifying to realize how fragile a medical career can be. But catastrophic fears lose their power when you confront them with a real plan. You don't have to live with the constant, nagging anxiety of "what if?"
Many physicians before you have faced career-ending illnesses or injuries and emerged financially secure because they built their safety nets early. You've worked too hard for your freedom to leave your portfolio vulnerable to bad luck. Take action today: schedule a financial review, lock in proper insurance, build your liquid reserve, and guarantee your financial survival no matter what happens to your health.