What if the "guaranteed" salary you were counting on for your first year isn't actually guaranteed in the way you think it is?
That's the fear, right? Not the abstract contract-law fear. The 2:13 a.m. fear. The one where you've already mentally committed to rent, student loans, a move, maybe childcare, maybe a spouse quitting their job to follow you, and then suddenly you're wondering whether that shiny "year-1 guarantee" can shrink, stall, or disappear entirely.
It can. Not always. But often enough that you should be suspicious on purpose.
Recruiters usually present compensation the way real estate agents stage a house: best lighting, clean angles, no mention of the cracked plumbing behind the wall. They'll say "guaranteed first-year income" as if that phrase means one clean, unconditional check structure. It usually doesn't. Contracts are messier. The money may be time-limited, contingent on start dates, linked to productivity, subject to repayment, or quietly converted into something much less comforting after a few months.
And "year-1 guarantee" can mean a lot of different things. A true base salary. A minimum compensation floor. A draw against future production. A sign-on that looks like salary support but acts like a trap if you leave early. A stipend with a clawback. An earnback arrangement dressed up as security. Those are not interchangeable. Not even close.
This article is for the anxious person, honestly, the smart person, who wants the worst-case checklist before signing. I'm not assuming every employer is shady. I am saying you should stop treating "guarantee" as a synonym for "safe."
This article is for educational purposes only, not legal, financial, or tax advice. Contract language, compensation design, and actual outcomes vary a lot by employer, specialty, and state, so get your own contract reviewed by a qualified attorney or advisor before you sign anything.
Why the "Year-1 Guarantee" Feels Like a Lifeline (and Why That's Not the Whole Story)
I get why applicants cling to the guarantee. Training makes most of us weirdly tolerant of delayed gratification, but once the attending job search starts, that first real salary number becomes emotional. It stops being math and starts feeling like survival. You see a guaranteed year-1 figure and think: okay, I can breathe now.
That reaction is normal. It's also exactly why people get burned.
The problem isn't that guarantees are fake across the board. The problem is that the word "guarantee" is used casually in recruiting conversations and precisely in contracts. Those are two very different languages. The recruiter is giving you the headline. The contract is hiding the weather report, the exclusions, and the trap door.
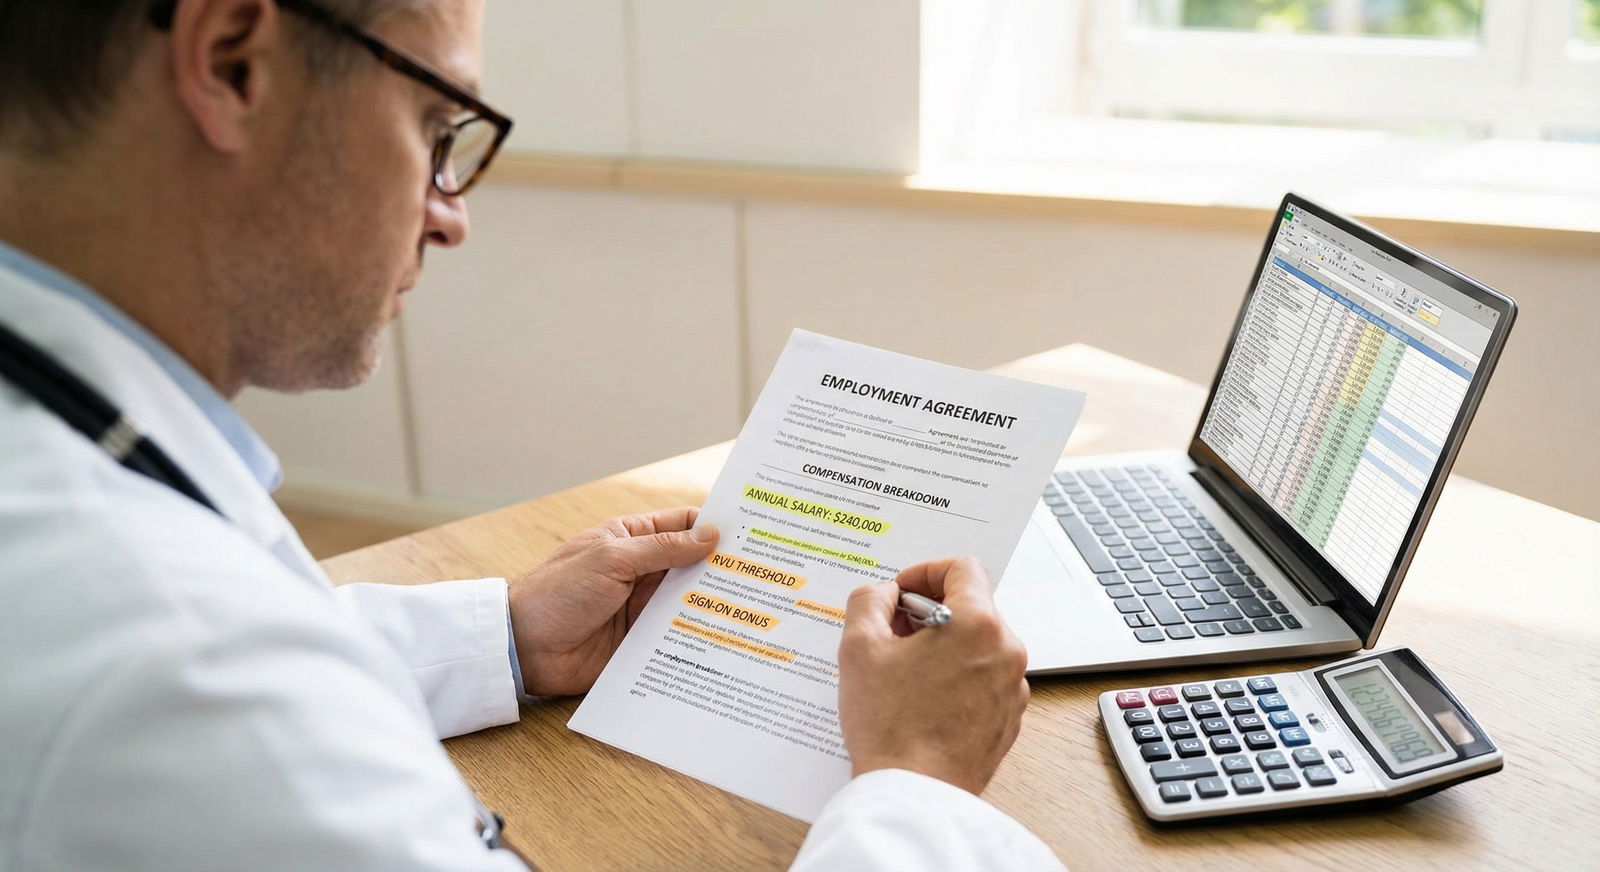
I've seen applicants repeat the compensation package out loud as if they've already verified it: "It's 240 guaranteed first year." Then you read the agreement and realize it's 240 only if they start by a specific date, remain full-time, meet call expectations, keep privileges active, and stay employed through a defined period. Miss one moving part and suddenly the "guarantee" starts acting more like conditional support.
That doesn't mean panic. It means decode the structure before you build your life around it.
The Forms a "Year-1 Guarantee" Can Take (and the Fine Print That Determines Survival)
Here's where things get annoyingly slippery. Employers use one friendly phrase for several completely different pay designs.
A true guaranteed base salary is the cleanest version. You're paid a fixed amount during year 1, usually spread over payroll periods, regardless of short-term production swings. Good. Simple. Less dangerous. But even then, don't get lazy. Some of those "true" bases still require you to remain full-time, cover a certain call burden, maintain privileges, or avoid specific performance failures.
Then there's the productivity floor. This sounds reassuring because it implies you won't fall below a minimum while you ramp up. But the floor may only apply if you meet defined productivity, clinic-session, or schedule expectations. Translation: if operations are a mess, or if referral flow is weak, the contract may still put the burden on you to have been "available enough" to produce.
The draw model is where applicants really get into trouble. A draw is not a gift. It's an advance against future earnings. If you underproduce, the money may still have to be earned back later through reduced compensation, offset bonuses, or repayment terms. Recruiters love soft phrasing here. "Income support." "Ramp support." "Stabilization pay." Cute words. It's still often debt-shaped.
Stipends can be even sneakier, especially pre-start stipends during fellowship or residency. They feel like free money until you realize they may carry a clawback if you don't start, don't stay long enough, or trigger a termination provision. Same with sign-on bonuses. People mentally file them under compensation, but contractually they often behave like conditional loans.
wRVU minimums and guarantee-or-pay hybrids add another layer. You may be promised the greater of a guaranteed amount or your production formula, but only for a set time. Once that period ends, all the comfort vanishes and the math gets real fast. If the formula isn't strong, the floor was just a temporary cushion over a weak long-term comp plan.
Then there are time-horizon traps. Some guarantees begin on your employment start date, not your first day of actual revenue generation. That difference matters. A lot. If your credentialing drags for ten weeks, if licensure lags, if the EMR setup is delayed, if clinic templates aren't opened, the calendar may still be burning through your "guaranteed" year while you can't fully bill. I've seen this happen. The physician thinks they had twelve months to ramp. In reality they had eight productive months and four administrative months counted against them.
Condition traps are just as ugly. Your guarantee may require full-time status defined by a specific number of sessions, call shifts, outreach coverage, or site assignments. If you negotiate a reduced schedule later, if family issues alter availability, or if you're reassigned, the guarantee may adjust or disappear. And yes, even if the reason feels reasonable.
That's the core truth nobody says clearly enough: "guaranteed" does not mean "no risk." It usually means "guaranteed if." And the entire game is hidden inside the if.
How Guarantees "Vanish": The 6 Most Common Real-World Triggers
Let's talk about how this falls apart in real life, because this is where people start saying, "But the recruiter told me, " and I need you to stop that sentence before it forms. If it's not in the contract, it's air.
The first trigger is early termination or resignation. This is the obvious one, but applicants still underestimate it. If you leave before the retention period ends, the employer may argue that part of your year-1 support was advance compensation, not fully earned salary. That can mean repayment of sign-on money, stipend money, relocation support, or even a prorated piece of what you thought was guaranteed comp. Not every employer does this. Enough do.
Second: termination for cause. This gets ugly fast because "cause" definitions can be broader than applicants expect. It's not just criminal conduct or catastrophic behavior. It can include repeated documentation failures, compliance issues, loss of privileges, failure to maintain licensure, policy violations, or conduct they classify as disruptive. Once for-cause termination hits, employers may stop pending payments immediately, deny future installments, or trigger repayment language. You don't have to be a villain for this to become a nightmare. Sometimes you just have to be in a badly managed system with strict paperwork expectations.
Third: not meeting productivity or benchmark requirements. This is where the anxiety gets personal, because now it feels like your fault even when it isn't. Maybe the contract ties your support to wRVUs, patient encounters, panel growth, documentation closure rates, or referral conversion metrics. Maybe no one says that part loudly during recruiting. Then six months later you learn that your schedule has giant holes, referrals are leaking to legacy partners, your templates were built poorly, and somehow you're still the one "under target." Brutal. Common.
Fourth: payer mix changes, service-line disruption, or site closures. This one enrages me because it exposes how often "guarantees" aren't really risk-shifting tools at all. If a clinic closes, if staffing collapses, if a coverage site changes, if your collections crater because of payer issues, some contracts still force the downside back onto you after the initial floor period or through formula adjustments. In other words, the institution's operational failure can become your compensation problem.
Fifth: operational delays you didn't cause. Credentialing delays are the classic example. So are delayed privileging, broken scheduling systems, unavailable exam rooms, slow marketing, poor MA support, incomplete equipment setup, and late payer enrollment. These are not small hiccups. They directly affect your ability to produce. And yet many contracts define the guarantee by calendar time, not by revenue-ready time. So the year starts ticking while you sit there smiling politely in orientation modules, wondering why your panel is empty.
Sixth: the conversion clause. Honestly, this is the part I wish every applicant would obsess over more. Because the guarantee itself may not vanish during year 1, it may simply set you up for a harsh drop in year 2. If your first year is a flat support amount and then your second year flips to collections, wRVU thresholds, or personal billing performance, your pay can swing hard. Recruiters love to sell the floor and glide past the landing. Don't let them.
Here's the practical version: a year-1 guarantee can disappear because you leave, because they say you breached, because you miss performance terms, because operations fail, because the timeline was unrealistic, or because the contract was always designed to get less stable later. Those are the six big traps. None of them are rare enough to ignore.
Salary Math Recruiters Don't Show You: The "Guarantee vs Take-Home vs Expectation" Gap
This is the part people hate because it ruins the fantasy spreadsheet.
Gross compensation is not take-home pay. A year-1 guarantee may sound huge until you subtract taxes, retirement withholding, benefit premiums, malpractice tail questions, licensing costs not fully covered, moving expenses, and any repayment exposure tied to sign-on or stipend money. If part of the package is non-cash, CME, relocation, loan assistance structured a certain way, temporary housing, that may help, but it doesn't pay your mortgage the same way payroll does.
Also, many offers quietly blur base and bonus. The "total comp" number in a conversation may include discretionary quality bonuses, citizenship bonuses, or projected productivity bonuses that are not guaranteed at all. So when you hear a number, break it apart. What is fixed? What is merely possible? What is repayable? What is contingent on staying?
And then there's the year-2 cliff. If year 1 props up a slow ramp, year 2 can be unstable by design. That's not automatically bad. Some physicians do much better after conversion. But if you don't model the downside, you're budgeting off hope. Hope is not a compensation strategy.
My rule is simple: build your budget around four numbers only. Guaranteed base. Guaranteed bonus eligibility, if truly contractual. Maximum clawback exposure. Expected median production after conversion. Everything else is fluff until proven.
Specialty-Specific Considerations: Where Guarantees Hold Up vs Where They Break
Not all specialties carry the same risk after the guarantee period. Anyone telling you otherwise is selling simplicity because simplicity closes deals.
Outpatient-heavy fields often depend on panel growth, referral capture, no-show rates, scheduling efficiency, and payer mix. That means primary care, peds, and many clinic-driven subspecialties can look fine on paper but ramp slowly in the real world. If the patient pipeline is weak, your production formula may punish you for a system problem.
Procedure-heavy specialties can have wider swings. Surgery and certain interventional fields may have high upside after conversion, but they're also vulnerable to block time limitations, referral politics, OR access issues, case mix, and support staff shortages. One broken operational link and your production suffers fast.
Hospital-based jobs can be more stable if compensation is less personally volume-sensitive, but not always. Coverage expectations, shift counts, quality metrics, and call burdens can still be attached to the so-called guarantee.
The metric itself may also be flawed. wRVUs don't capture every real-world barrier. Collections depend on billing infrastructure you don't control. Referral assumptions can be wildly optimistic. New practice builds almost always take longer than the brochure suggests.
So ask for historical data. Not promises. Actual compensation outcomes for comparable physicians in your specialty who started recently under the same model. If they can't show you that, or won't, assume the uncertainty is larger than advertised.
Your Contract Safety Checklist: Questions to Ask Before You Sign Anything
This is where anxious applicants can actually become dangerous in a good way. You do not need to sound confrontational. You do need to sound specific.
Start with the exact guarantee language. Ask them to point to the clause and explain, in writing, what stops the payments, what reduces them, and what triggers repayment. Is the money refundable? Is any portion treated as an advance? If you resign at month ten, what exactly happens? If they dodge with "that rarely comes up," ask again. Rarely is not never, and you're the one taking the risk.
Next, get the year-2 formula in plain English and in writing. Not a vague "it moves to productivity." That phrase is useless. You want the actual mechanics: wRVU rates, thresholds, conversion factors, collections percentages, bonus gates, caps, floors, timing lags, reconciliation schedules, and whether deficits carry forward. If there's an earnback provision, make them show you the spreadsheet logic. If they can't explain it clearly, that's a bad sign. Full stop.
Then ask the operational questions recruiters prefer to wave away. How long does credentialing usually take for this specialty in this state? When does the guarantee clock start: contract start date, first day on site, or first billable day? Who is responsible for building your template? How many clinic sessions are you expected to run by month three? Who is sourcing patients? Do you inherit an existing panel, or are you building from zero? If they say "you'll ramp quickly," ask for numbers. I'm serious. Ask for actual historical ramp data.
Get comparable cohort data. This matters more than polished compensation brochures. Ask what physicians who started in the last 12 to 24 months actually earned in year 2 under the same model. Not top decile stars. Comparable hires. Similar specialty. Similar FTE. Similar site. If the employer says compensation is too individualized to discuss, that's often a polite way of saying the outcomes are more variable than they want you to see.
You also need to understand how performance is measured and challenged. What counts as a deficiency? Who decides whether your documentation is inadequate? Is there a cure period before pay is reduced or termination for cause is triggered? Can you review the productivity reports used to calculate your compensation? Do you have audit rights if the numbers look wrong? Billing and wRVU reporting errors happen more than people realize, and passive physicians get steamrolled.
And yes, check dispute resolution and termination terms. If something goes sideways, how much notice do you get? Is there a without-cause termination provision? How long? What compensation continues during notice? Does repayment accelerate immediately? Is there a noncompete waiting to make a bad situation even worse? These are not side issues. They are the difference between a stressful transition and a financial crater.
If you want the blunt version, here it is: don't sign a comp model you can't explain back to someone else in two minutes. If you can't describe where the money comes from, when it changes, and what makes it disappear, you don't understand it well enough yet.
Worst-Case Preparedness: How to Protect Yourself If the Guarantee Ends Early
I know this sounds grim, but contingency planning is calming once you do it. Undefined fear is what eats you alive. A plan gives the fear edges.
Build an emergency fund around the possibility that compensation drops sooner than expected. Know your minimum monthly survival number, not your ideal lifestyle number. Separate the two. If you're moving for the job, account for deposits, furniture, licensing lag, partner job disruption, and childcare instability if call gets uglier than promised. Real life is expensive in boring ways no recruiter includes on a slide.
Review the termination and repayment language like someone who expects stress, not like someone hoping everything stays sunny. How much notice is required if either side ends the relationship? When do guarantees convert? Are repayments due in a lump sum or over time? Is there a noncompete that could trap you geographically after a bad fit? Worst-case planning isn't pessimism. It's adult behavior.
And if there's room to negotiate, ask for guardrails. A shorter earnback window. A clear cure period before compensation reductions. Guarantee timing tied to billable readiness, not just calendar start. A modest floor into year 2 while the practice ramps. You won't always get these. But asking is smart, and sometimes employers say yes more often than anxious applicants assume.
Most important: preparing for downside doesn't mean you expect disaster. It means you refuse to be blindsided. That's a healthier kind of confidence.
Encouragement: You're Not Overthinking, You're Doing the Right Due Diligence
If this topic makes you anxious, good. Honestly. Not panicked. Just alert.
Recruiters simplify because simplified stories are easier to sell. Contracts don't care about the story. They care about definitions, triggers, dates, formulas, and repayment rights. That's why your questions matter so much. You're not being difficult. You're being competent.
You do not need to become a lawyer. You do need the compensation logic in writing. And if the logic is fuzzy, complicated, or strangely hard to pin down, trust that discomfort. It's usually trying to protect you.
Run the offer by someone who's seen the movie before, an attending mentor, alumni from your program, a physician contract attorney, a compensation consultant. I've watched applicants save themselves thousands of dollars and months of misery just by asking one extra question at the right time.
Year-1 guarantees can absolutely be real. They can also be dressed-up instability. The difference is in the fine print. So no, you're not overthinking this. You're doing exactly what you should: slowing down, reading carefully, and making sure the promise matches the paperwork.