Heads up: this article is for educational purposes only and is not financial, legal, or tax advice. Figures vary by specialty, region, and employer. Before signing any physician employment agreement, consult a qualified professional who can review your specific contract.
Here's the trap. You see a posting that says "$320,000 guaranteed first year." Feels safe. Feels certain. Then month 13 hits, the guarantee evaporates, and suddenly you're earning less than the new grad who started six months ago under a clean base-plus-bonus deal. I've watched this happen. More than once. And every single time, the physician says the same thing: "Nobody told me the guarantee was just the bait."
This is the warning I want to give you. Don't compare Year 1 dollars. Compare the full path of compensation, including renewal terms and what happens when the guarantee ends. The structure that looks "safe" on day one can become the most expensive mistake of your career by year three.
When the "Guaranteed" Number Hides the Real Risk
Let's be blunt about what's actually happening when an employer advertises a guaranteed salary. They aren't doing you a favor. They're reducing their downside risk. A guarantee protects them if your panel doesn't fill, if referrals dry up, or if the local market shifts. It also gives them a built-in exit ramp, a moment where your pay quietly resets to whatever they decide comes next.
The real danger isn't the guarantee itself. It's the silence around what comes after.
Here's how the trap typically unfolds:
- The first-year number looks higher than competing offers. You assume the employer values you more.
- The contract language around year two is vague, buried, or framed as "subject to market adjustment."
- You sign. You move. Maybe you relocate your family. You take on new debt based on the income you were promised.
- Month 12 ends. The "guarantee" sunsets. Your base drops, or your bonus target jumps, or both.
- You're stuck, financially, geographically, or contractually.
Don't fall for the framing that a guarantee is the conservative choice. A guarantee is only as good as the structure underneath it. If the post-guarantee conversion is weak, that first-year number isn't safety. It's a signing bonus with a longer runway.
The lesson: the first paycheck is not the contract. The contract is the contract.
Guaranteed Salary vs Base+Bonus: What Looks Safe Can Cost You
Let's define both structures cleanly, because recruiters blur them on purpose.
Guaranteed salary. You receive a fixed amount for a defined period, usually 12 to 24 months. During that window, your income is essentially a salary, regardless of how many patients you see or how productive you are. After the guarantee expires, the contract converts to something else: often a lower base, often a productivity model, often a formula the employer can adjust.
Base + bonus. You receive a base salary (often lower than a guarantee would be in year one) plus a productivity or quality bonus tied to wRVUs, collections, panel size, patient satisfaction, or some combination. In a well-designed base+bonus deal, the bonus is attainable, measurable, and written in concrete terms.
Now the mistake. Physicians assume guaranteed equals better. Wrong. A guarantee is only better if the alternative is worse across the full contract term. Run the math on a three-year horizon and the picture often flips.
Consider a real-world pattern I've seen repeatedly:
- Offer A, "Guaranteed": $340K year one, then drops to a $240K base with an "aggressive" wRVU target that requires 1.4x the median regional productivity. By year three, you're earning less than $300K and working longer hours.
- Offer B, "Base + Bonus": $260K base with a transparent wRVU bonus that pays $45 per wRVU above threshold, thresholds set at the 50th percentile of MGMA data. By year three, you're earning $360K to $400K and your bonus math is the same formula every year.
The "guaranteed" deal looked safer on paper. It wasn't. It was a slower-burning trap.
Here are the compensation clauses that can erase the apparent advantage of a guarantee:
- wRVU thresholds set above market norms. If the target is higher than what 70% of similar physicians in your specialty actually produce, the post-guarantee base becomes your real ceiling.
- Clawback provisions. Some contracts allow the employer to recover bonus overpayments if a coding audit comes back unfavorable, months or years later.
- Bonus caps. A "uncapped" bonus sounds generous until you read the small print limiting it to 25% of base.
- Delayed payouts. Bonuses paid 6 to 12 months after the performance period mean you're essentially lending your employer your productivity for free.
- "Market adjustment" language. This phrase is the enemy. It usually means "we can lower your pay whenever we want."
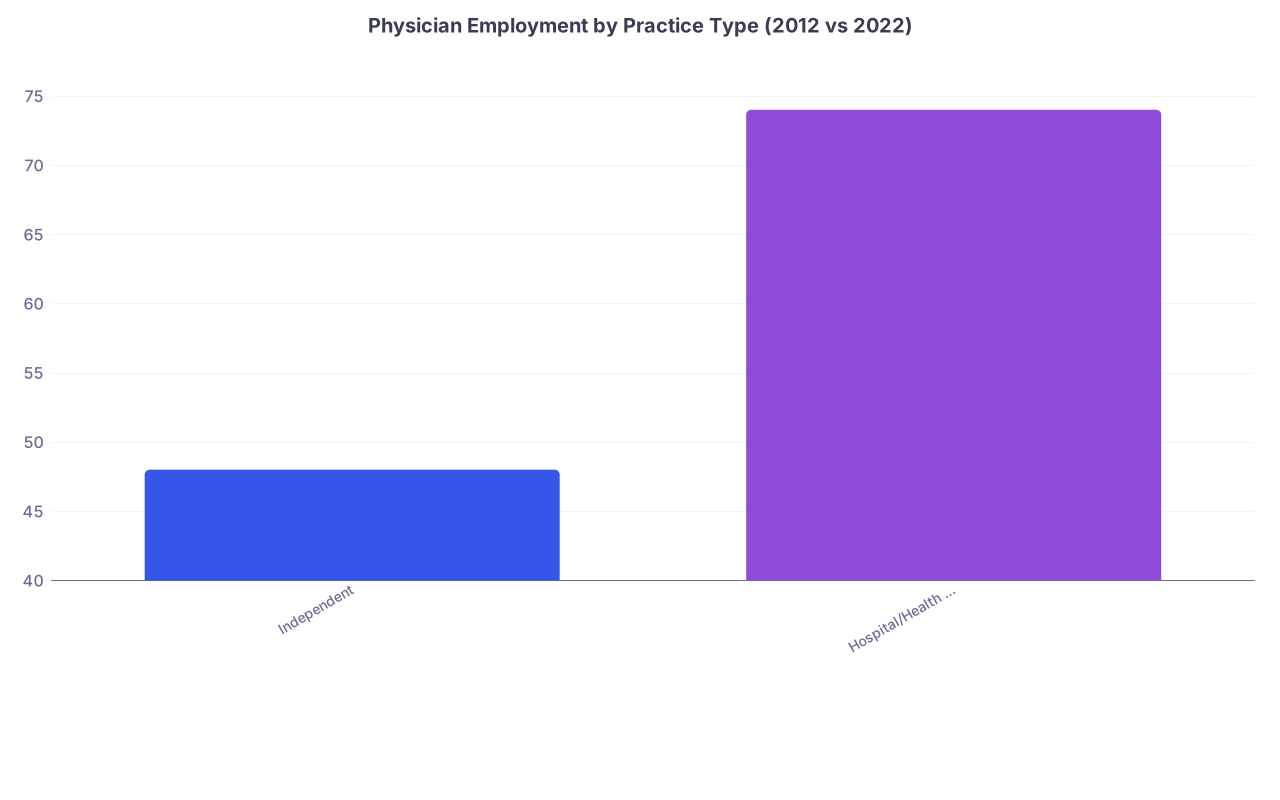
The chart tells the story. Year one favors the guarantee. Year three favors the bonus. And the worst-case base+bonus scenario, where you never hit target, still ends up roughly even with the guarantee's post-conversion reality. That's not a coincidence. That's how the math works when the bonus is honestly designed.
Where Physicians Get Trapped Mid-Contract
The mid-contract trap isn't random. It's engineered into the agreement. Here are the red flags I tell every physician to scan for before signing.
Red flag 1: Short guarantee period with no written post-guarantee formula. A one-year guarantee is not protection. It's a runway. If the contract doesn't spell out exactly what happens in month 13, you're trusting the employer to be fair. Don't.
Red flag 2: Automatic conversion to lower pay. Some contracts contain language like, "After the guarantee period, physician's compensation shall be set at a base consistent with market and adjusted at the discretion of administration." That sentence is a pay cut waiting to happen. "Discretion of administration" means they decide. Not you.
Red flag 3: Vague bonus metrics. If the bonus is tied to "productivity, quality, and citizenship," with no weights, no definitions, and no benchmarks, you have no way to predict what you'll earn. That's not a bonus. That's a lottery.
Red flag 4: Unilateral employer control over RVU targets. Contracts that let the employer raise the wRVU threshold mid-contract, or change the conversion factor, transfer all the productivity risk to you. You do the work. They change the rules.
Red flag 5: Hidden leverage loss. Even if the pay drop is tolerable, the contract may not be. Relocation reimbursement clauses that trigger payback if you leave within 24 months. Noncompete radius that locks you out of every nearby employer. Tail insurance or signing bonus clawbacks that come due the moment you try to exit.
Then there's the practical reality. Patient volume assumptions baked into the guarantee are often optimistic. New physicians typically take 9 to 18 months to build a panel. If your first-year guarantee was calculated assuming full panel from month one, your post-guarantee wRVU target may be based on a fantasy. Meanwhile, staffing shortages, referral bottlenecks, and EMR inefficiencies slow your ramp. Year two becomes financially painful, not because you underperformed, but because the contract was never realistic.
That's the flow. Look familiar? It should. It's how the trap works.
How to Compare Offers Without Getting Burned
Now the practical part. How do you actually evaluate two offers without getting fooled by the headline number?
Use this checklist before you sign anything:
- Annualized total compensation across the full contract term. Not year one. The full deal.
- Guarantee length and post-guarantee formula. Get both in writing. If the employer won't put the post-guarantee math on paper, that's the answer.
- Bonus attainability. Compare the wRVU threshold to MGMA, AMGA, or SullivanCotter data for your specialty in your region. If the target is above the 75th percentile, assume you won't hit it most years.
- Pay timing. When does the bonus pay out? Quarterly is reasonable. Annually with a 6-month lag is not.
- Downside risk. What happens if you underperform, get sick, or have a slow ramp? Is there a floor? A safety net? Or are you exposed from day one?
- Leverage after the guarantee. Noncompete radius, payback clauses, tail coverage obligations, and termination notice periods. These decide whether you can leave if the deal turns bad.
Then model three scenarios before you sign:
- Best case. You ramp fast, hit every target, collect every bonus.
- Expected case. You're a median producer in year two and three. What do you earn?
- Worst case. Slow ramp, missed targets, no safety net. Can you survive this financially?
If the worst case is unacceptable, the contract is unacceptable. Period.
One more thing. Recruiters summarize. They don't disclose. The person selling you the job is not the person paying you the job. Get the actual contract language. Read it. Better yet, have someone who reads contracts for a living read it.
What to Do Before You Sign
Here's your action sequence. Run through this in order. Don't skip steps.
- Ask for total compensation projections across the full term. Not year one. Year one, two, three, and any renewal. If they can't give it to you, they don't know either, and that's a problem.
- Verify the bonus mechanics. Threshold, conversion factor, payout timing, and whether the employer can change any of it mid-contract.
- Request the post-guarantee pay formula in writing. "Subject to market adjustment" is not a formula. Reject it.
- Pressure-test the metrics. Pull regional benchmark data. Compare. If the targets are aggressive, assume they'll stay aggressive.
- Review the exit clauses. Noncompete, payback, tail insurance, termination notice. These determine whether you have a future outside this employer.
- Get a qualified professional to review the contract. Not your med school roommate. Not the recruiter. Someone whose job is to protect you.
And please, do not fall for these pressure tactics:
- "This offer is standard." Standard for whom? You?
- "Everyone signs it." Everyone also gets surprised by year three.
- "We can explain it later." If they can't explain it now, the explanation isn't going to help you.
- "You can always renegotiate." Renegotiation requires leverage. You won't have any in month 13.
Slow down. The offer won't disappear because you took a week to read it carefully. The bad math in year three won't disappear because you signed fast.
A guaranteed salary can be a great deal. It can also be a beautifully wrapped pay cut. The only way to tell the difference is to read past the first year. Model the full contract. Spot the leverage loss before it shows up in your paycheck.
Don't let a temporary guarantee trap you in a long-term pay cut. That's the mistake. Avoid it.
Key Takeaways
- A guaranteed salary is not automatically safer; the real risk is what happens when the guarantee expires.
- Base + bonus can outperform a guarantee if the metrics are clear, written, and realistically attainable, while a "safe" guarantee can hide a future pay drop.
- Never sign without modeling year one, year two, and year three compensation, and check the clauses that control your leverage after the guarantee ends.