Scenario: The Physician's Retirement Healthcare Dilemma
You're 55, maybe 60. You've been socking away money into your 401(k) for decades. Your investment accounts look healthy. And then one day you glance at a projection of your post-retirement medical costs, and your stomach drops.
Because healthcare inflation chews up wealth like nothing else. Fidelity's annual estimates show a 65-year-old couple retiring today needs roughly $315,000 just for medical expenses throughout retirement. That's not counting long-term care. And Medicare won't cover everything.
As a physician, you know better than anyone how fast medical costs rise and how unpredictable health needs become. Yet many doctors I meet still treat retirement healthcare like an afterthought, hoping their employer plans or Medicare will handle it. That's a mistake.
The single most underused weapon in your retirement arsenal? The Health Savings Account (HSA). Most physicians either ignore it, contribute the bare minimum, or drain it each year to pay for current medical bills, missing its real power. An HSA isn't just a spending account; it's a triple-tax-advantaged retirement machine.
I'm going to lay out the 7 strategies that turn your HSA into a fortress for retirement medical costs. No fluff. Just actionable, physician-specific moves.
Disclaimer: This article is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Figures vary. Consult a qualified professional before making any financial decisions.
1. Understand Why HSA Is the Ultimate Retirement Medical Account
Let's be blunt: there's no other account that gives you tax-free money in, tax-free growth, and tax-free withdrawals for medical expenses. That's the triple tax advantage. Not your 401(k). Not your Roth IRA. Contributions go in pre-tax (or are deductible), earnings compound untouched, and if you spend the money on qualified medical costs, you never pay a dime in tax. Ever.
Compare that to a Flexible Spending Arrangement (FSA), which most physicians are familiar with. FSAs have a brutal "use it or lose it" rule, money left over at year's end disappears. HSAs? Your balance rolls over year after year, indefinitely. You can build a six-figure medical war chest and never worry about a deadline.
Physicians can open an HSA if they're enrolled in a high-deductible health plan (HDHP). I know some docs avoid HDHPs because they don't want to deal with higher deductibles. But once you see the retirement potential, the trade-off becomes obvious. Even if you're in a group practice with a traditional plan, consider switching to an HSA-eligible HDHP during open enrollment, or if you're self-employed, you likely have more flexibility.
And here's the kicker: you can invest your HSA money just like a 401(k). Most HSA providers let you select from a range of mutual funds, index funds, or ETFs once your cash balance hits a certain threshold (often $1,000-$2,000). That turns a simple healthcare account into a long-term growth vehicle, compounding tax-free for decades. I've seen physicians accumulate well over $200,000 in an HSA by retirement just by maxing contributions and letting the market do its thing.
Don't treat your HSA as a checking account. Treat it as a stealth IRA with a medical-expense superpower.
2. Maximize Your HSA Contributions Every Year
Here's the straightforward rule: contribute the absolute maximum every year you're eligible. For 2024, that's $4,150 for self-only coverage and $8,300 for family coverage. If you're 55 or older, add an extra $1,000 catch-up contribution.
Why does every dollar matter? Because the power of compounding over a 20- or 30-year physician career is staggering. Let's assume you start maxing your family HSA at age 40, contribute $8,300 annually (with catch-up later), and earn a modest 7% average annual return. By retirement at 65, that account could be worth over $460,000. Even if you only contribute for 20 years, you're looking at six figures of tax-free medical money.
I've seen too many docs prioritize their 401(k) or taxable brokerage while ignoring the HSA. Do the math: a 401(k) gives you a deduction today but withdrawals in retirement are taxable. An HSA withdrawal for medical costs is tax-free. For every dollar you spend from a 401(k), you'll lose at least 20-30% to taxes depending on your bracket. An HSA dollar is a complete, 100% effective dollar.
Catch-up contributions are especially important for physicians in their 50s and 60s. The extra $1,000 per person per year might seem small, but it adds $10,000 over a decade, plus all that tax-free growth. If both you and your spouse are over 55, that's an extra $2,000 per year into the HSA.
And here's a nuance: even if you have other health coverage through a spouse's plan, you can still open and fund your own HSA as long as you're covered by an HDHP and not simultaneously covered by a non-HDHP plan that disqualifies you. Know the rules, but don't leave money on the table.
3. Invest Your HSA Funds, Don't Just Let Them Sit in Cash
I'll say it plainly: leaving your entire HSA balance in cash is wasted potential. Yet surveys show a majority of HSA owners never invest beyond the default cash account. They treat it like an enhanced checking account for co-pays and deductibles. That's exactly backward.
Think of your HSA in two layers. The first layer is your deductible and near-term medical spending, maybe $3,000 to $5,000 kept in cash or a money market fund so you can access it quickly. Everything above that threshold should be invested aggressively for growth, mirroring your long-term retirement asset allocation.
What to invest in? Low-cost total stock market index funds, S&P 500 funds, or a target-date index fund aligned with your expected retirement year. Avoid high-fee actively managed funds that eat returns. The HSA investment menu is usually similar to a 401(k), so apply the same boglehead principles.
Here's a real-world comparison. A physician who contributes $8,300 annually for 25 years and keeps funds in cash earning near 0% ends up with roughly $207,500. The same contribution stream invested at 7% annual return yields about $560,000. That's a $350,000 difference, all tax-free for medical expenses. Which one would you rather have?
Since HSA withdrawals for medical costs are penalty- and tax-free at any age, you can be more aggressive than you might be with a 401(k) where early withdrawals trigger penalties. Even in your 60s and 70s, you can let HSA growth continue while you pay medical bills from other sources, like the shoestring strategy I'll cover next.
Make a rule: right now, log into your HSA portal and set automatic sweeps so any balance above your deductible threshold gets invested. Check asset allocation annually. Don't overthink it. Start today.
4. Adopt the 'Shoestring Strategy', Pay Current Medical Expenses Out of Pocket
This is the single most powerful shift you can make. Instead of using your HSA debit card to pay for every doctor visit and prescription today, pay those bills with after-tax dollars from your regular checking account. Let your HSA balance sit untouched and invested.
Why? Because every dollar you pull out of the HSA today stops compounding and loses its future tax-free growth. By covering current expenses out of pocket, you essentially "transfer" those future tax-free withdrawals to a later date when medical costs are likely much higher, think retirement, long-term care, Medicare premiums.
Imagine you're 45 and face a $2,000 medical bill. If you pay it from your HSA, that $2,000 is gone forever. If you pay from your taxable savings instead, that same $2,000 in your HSA, invested at 7% for 20 years, grows to roughly $7,740 tax-free. Over decades, these decisions compound into enormous differences.
The shoestring strategy is not about deprivation; it's about prioritization. You don't have to eat ramen. You just allocate your cash flow differently. For physicians earning a solid income, redirecting $3,000-$5,000 annually toward current medical costs is usually feasible, especially if you're already maxing retirement accounts.
I've seen this transform a doctor's retirement plan. One physician I advised started the shoestring strategy at 50, paying all current costs out of pocket and investing the HSA aggressively. By 65, his HSA balance had ballooned past $250,000, almost entirely tax-free, ready for Medicare premiums, long-term care, and out-of-pocket costs that his peers were scrambling to cover from taxable assets.
5. Coordinate HSA With Other Retirement Accounts for Maximum Benefit
Most physicians have multiple retirement pots: 401(k), 403(b), IRAs, taxable accounts, maybe a defined benefit plan. There's an optimal order for funding them, and the HSA should come second, right after capturing any 401(k) match.
Here's my recommended hierarchy:
- 401(k) or 403(b) match: Free money. Contribute enough to get every dollar of employer match.
- HSA maximum: Because of the triple tax advantage and future medical costs, the HSA beats unmatched 401(k) contributions. Max it.
- Unmatched 401(k)/403(b) contributions: Up to the limit if you have high income.
- Backdoor Roth IRA or Roth conversions: Tax diversification.
- Taxable brokerage account: For liquidity and legacy.
This order ensures you capture the unique HSA benefits early. The HSA also works beautifully as a bridge for early retirement. If you retire before Medicare eligibility at 65, you'll need health insurance. You can use HSA funds to pay COBRA premiums or private insurance premiums tax-free, something you can't do with a 401(k) without penalties. That makes the HSA an essential tool for physicians aiming to leave clinical medicine before 65.
Tax diversification is another key. By stashing tax-free medical money in the HSA, you reduce your dependence on taxable withdrawals from traditional IRAs or 401(k)s in retirement. This can keep you in a lower tax bracket and protect your Medicare premiums from income-related surcharges (IRMAA). Less taxable income means less tax drag and lower Medicare Part B and D premiums.
Combine an HSA with Roth accounts and you can build a retirement where a significant portion of your spending is completely tax-free. That's a massive advantage physicians often overlook.
6. Plan for Healthcare Inflation and Long-Term Care Costs
Healthcare inflation has consistently run 1.5-2 times the general inflation rate. Over a 30-year retirement, that compounding can easily double or triple your actual costs compared to today's dollars. Medicare helps, but it's not a blank check. You'll still pay Part B and Part D premiums, deductibles, co-pays, and the stuff Medicare doesn't cover at all, hearing aids, dental, vision, most long-term care.
According to the latest estimates, a 65-year-old today will spend an average of $6,700 per year on healthcare (in 2024 dollars) beyond Medicare coverage. For a couple, that's easily $13,000-$15,000 annually. Over 25 years, that's over $300,000. And that doesn't include long-term care, which can cost $100,000+ per year.
Your HSA is tailor-made for these expenses. You can use HSA money to pay:
- Medicare premiums (Part B, Part D, and even Part C Medicare Advantage premiums)
- Long-term care insurance premiums (up to annual age-based limits)
- Actual long-term care costs (home health aides, nursing home fees)
- Dental, vision, hearing care, all qualifying medical expenses.
Because HSA funds grow tax-free forever, you can let a large balance compound throughout your 50s and 60s, then deploy it strategically for big-ticket care in your 70s, 80s, and beyond. It becomes a dedicated healthcare fund, insulating your other retirement assets from the shock of medical inflation.
When you project your retirement needs, don't use today's prices. Assume 5% annual healthcare inflation and see what a $5,000 annual out-of-pocket cost looks like in 20 years, hint: it's over $13,000. Then multiply that by 25 or 30 years. The HSA is the only account that can meet that burden without triggering tax consequences.
7. Leverage HSA for Estate Planning and Legacy Benefits
Most physicians don't think of an HSA as an estate planning tool, but it can be a surprisingly effective one. If you name your spouse as beneficiary, the HSA passes to them and remains an HSA with all its tax advantages intact. They can continue to take tax-free distributions for their own medical expenses, exactly as you would have. That's a rare benefit.
If you name a non-spouse beneficiary, like your children, the HSA loses its tax-free status and becomes taxable income to them in the year they receive it (the full fair market value). That's not ideal, but there's a planning twist: you can spend down the account during your lifetime and leave other, more tax-efficient assets to heirs. Or, if you have a large HSA balance later in life, you might consider using it for medical expenses while leaving Roth IRAs or step-up-basis assets to heirs.
In many states, HSAs are not subject to probate and can transfer directly to beneficiaries, avoiding court delays. That's a plus for physicians who want streamlined estate administration.
The true legacy benefit comes from the account's tax-free nature for medical costs. By keeping a robust HSA balance through retirement, you essentially create a medical-expense cushion that protects your estate from being drained by healthcare. That means more of your 401(k), IRA, or taxable assets go to heirs rather than to hospitals. It's not a direct transfer, but it preserves wealth.
Plan ahead: review your beneficiary designations annually. I've seen too many accounts default to an ex-spouse or a forgotten estate because no one bothered to update. You wouldn't leave your IRA beneficiary blank, treat the HSA the same way.
Action Steps: Implement Your HSA Strategy Today
Here's what I want you to do this week:
- Check your health plan. If you're not currently in an HDHP, evaluate the cost-benefit during your next open enrollment. Run the numbers with an HSA factored in.
- Review your HSA contributions. Are you maxing for 2024? If not, increase your payroll deduction or make a lump-sum contribution before the tax deadline.
- Invest the excess. Log in, see how much cash is sitting idle above your deductible, and move it into a low-cost index fund. Set up automatic sweeps.
- Switch to out-of-pocket payments. If you're using your HSA debit card, stop. Start paying current medical bills from your regular checking. Keep receipts, but preserve the HSA balance.
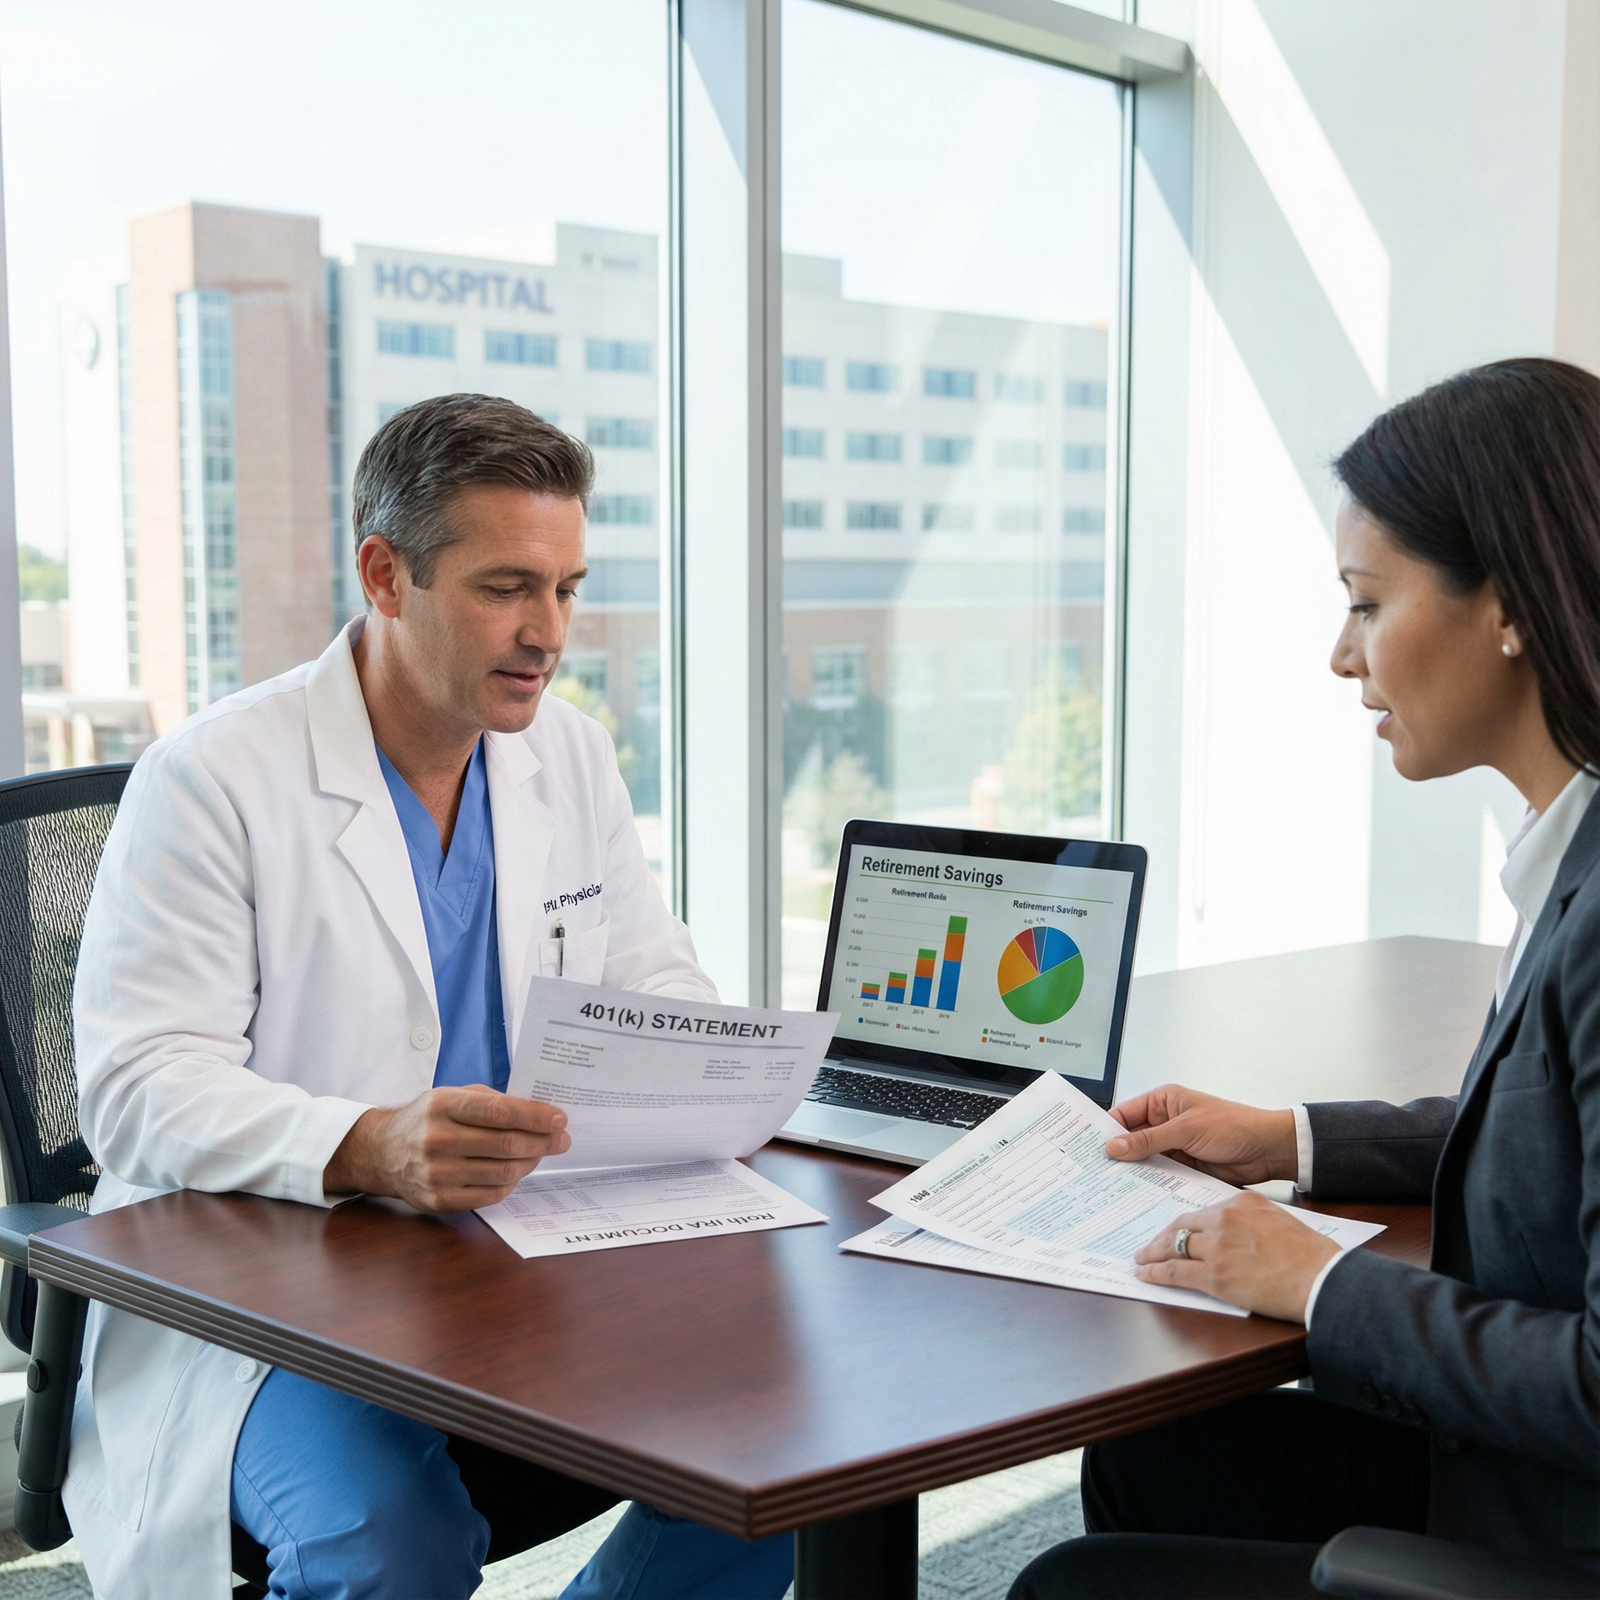
- Create a retirement healthcare projection. Use a conservative growth rate and healthcare inflation to estimate your HSA balance at retirement. Target a number that covers at least 20 years of estimated medical costs.
- Coordinate with your overall portfolio. Align your HSA investments with your risk tolerance and retirement timeline.
- Review beneficiary designations. Make sure your HSA passes to the right person.
Conclusion: Your HSA Is a Retirement Power Tool
The seven strategies I've laid out, understanding the triple tax advantage, maxing contributions, investing wisely, employing the shoestring strategy, coordinating with other accounts, planning for inflation, and leveraging estate benefits, transform a mundane HSA into a retirement medical fortress. As a physician, you have the income and the timeline to make these moves work. The only mistake is ignoring them.
Start now. Don't wait until retirement is knocking. Every year you delay is a year of tax-free growth lost. Take control of your healthcare costs, and you'll sleep better knowing you've built a bulwark against the one expense that can derail even the best-laid retirement plans.