Are you about to pick an IDR plan because someone told you it was "the cheap one"? Stop right there.
That single click can raise your monthly payment instead of lowering it. I've watched borrowers enroll in an Income-Driven Repayment plan expecting relief, only to open their servicer portal six months later and see a payment that jumped 40%. Not because they did something wrong, because they picked blind.
IDR isn't one-size-fits-all. Eligibility, recertification timing, household size, income definitions, and recalculation rules all shift the math. What looks like a $120 payment today can become a $380 payment at your next annual review if you didn't forecast the inputs.
This article is your guardrail. I'm going to walk you through the mistakes that trigger payment spikes, the red flags to watch for, and a concrete checklist you can run before you hit submit. No guesswork. No relying on your friend's outcome. Just protective, mistake-avoiding strategy.
This article is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Figures vary by individual circumstances, so consult a qualified professional before acting.
The Mistake: Picking an IDR Plan Without Forecasting Your Specific Payment Math
Here's the trap: treating IDR plans like they're interchangeable. They aren't.
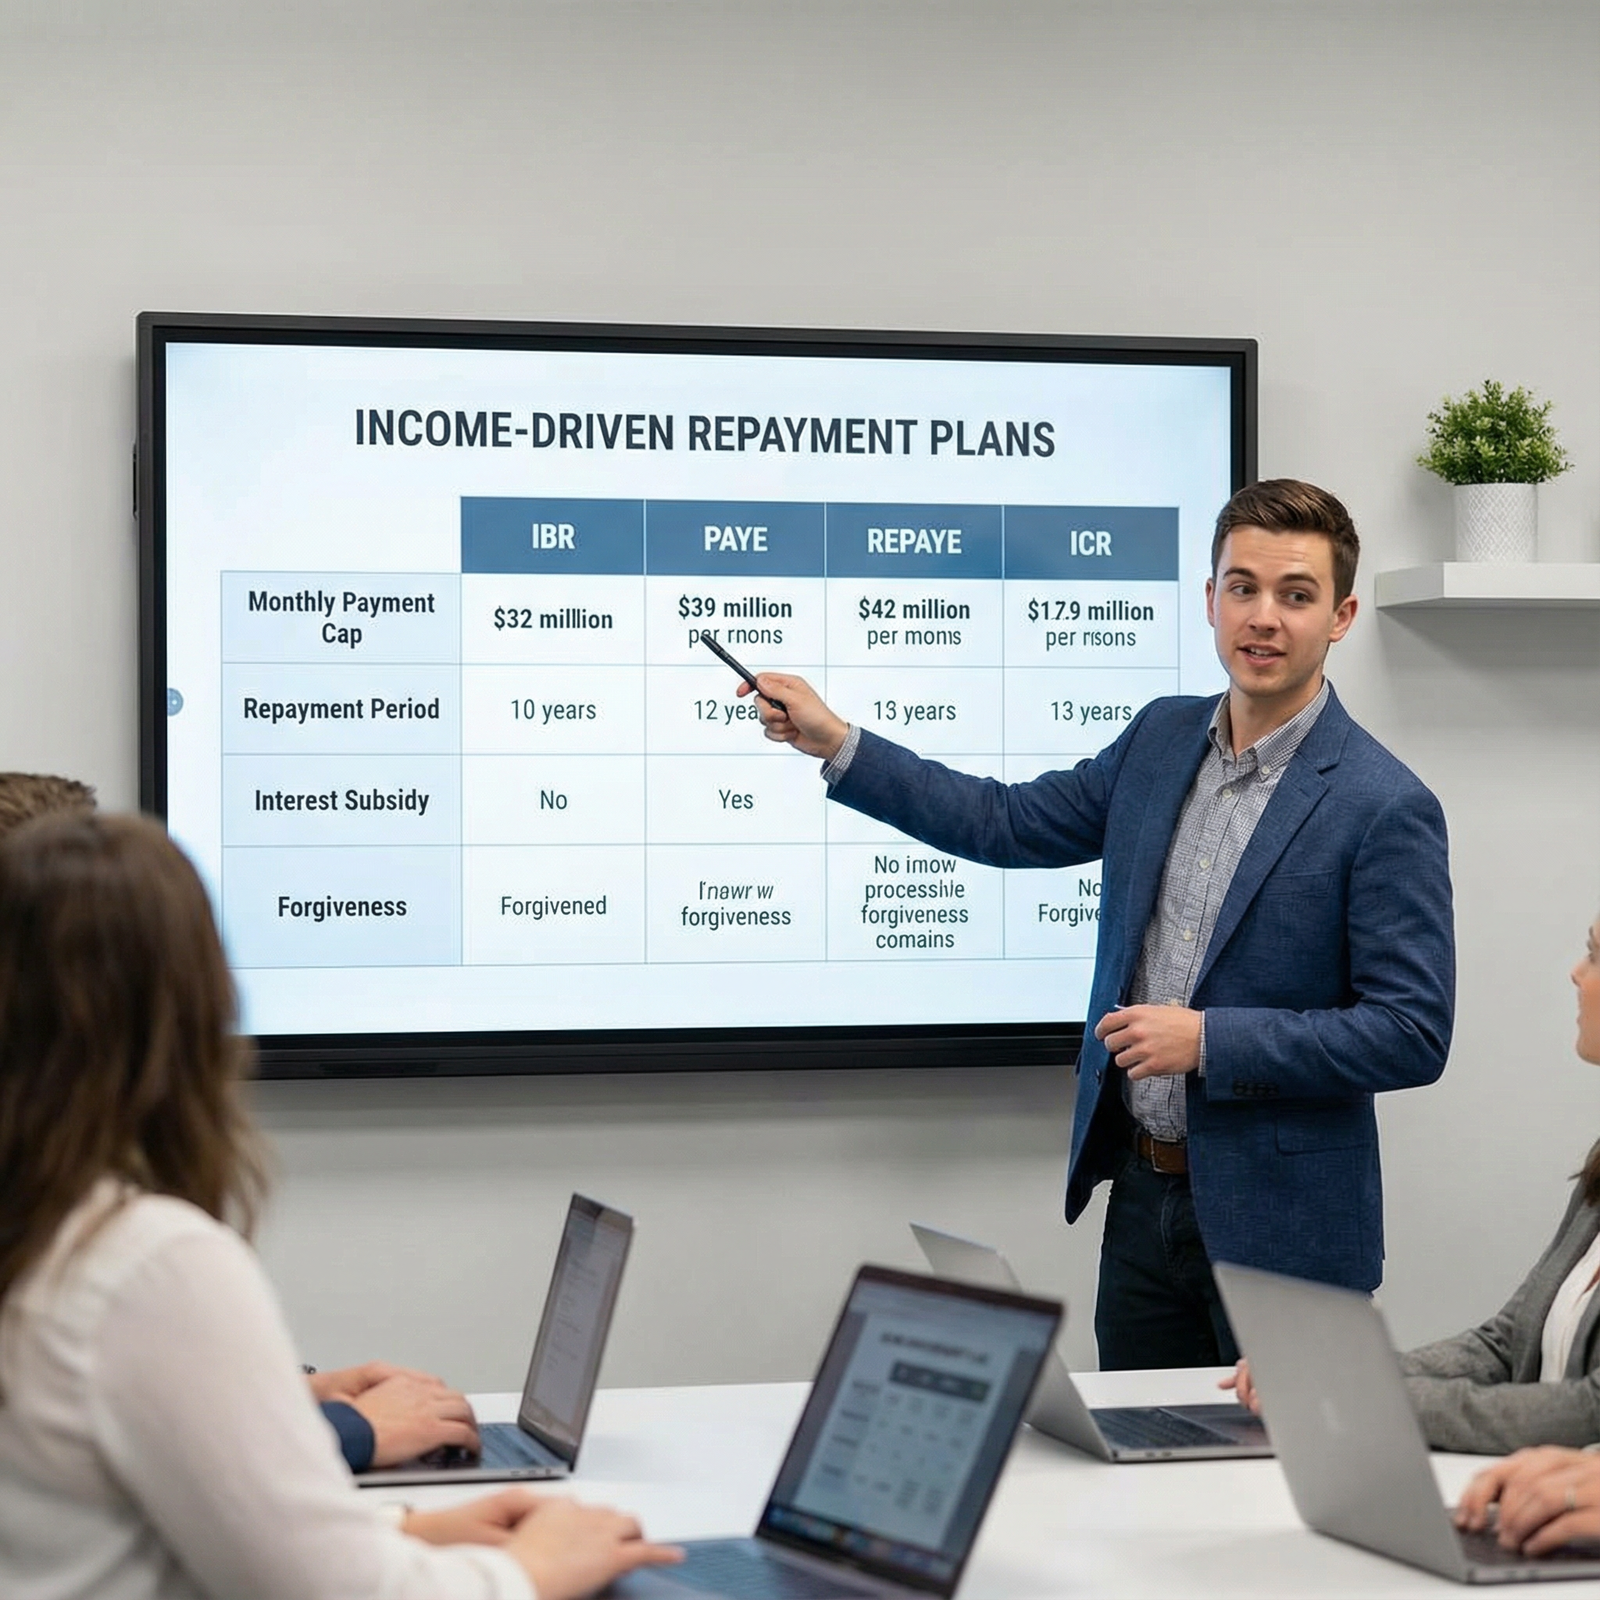
PAYE, SAVE, IBR, ICR, each one uses a different payment formula, treats income differently, and has distinct eligibility requirements. The plan that gave your coworker a $90 payment might hand you a $260 payment because your AGI, loan types, and household size don't match theirs.
Red flags I see constantly:
- Choosing a plan because "my friend pays almost nothing on that one."
- Picking whichever plan shows the lowest advertised cap without running your actual numbers.
- Ignoring what happens at recertification because the starting payment looks fine.
Forecasting means something specific. You estimate your payment using your actual Adjusted Gross Income (or alternative income documentation if you're not using a tax return), your current household size, your dependents, and your loan types. Then you model what happens if any of those inputs change before your next recertification.
If you skip this step, you're gambling. The servicer's calculator will give you a number, but it's only as good as the inputs you feed it, and most borrowers feed it assumptions, not reality.
Understand the Payment Drivers That Can Suddenly Increase Your Bill
Payment spikes don't happen randomly. They happen because specific inputs changed and you didn't see it coming.
Income swings. This is the biggest one. IDR payments are calculated using your income from a specific period, often your most recent tax return or alternative documentation of current income. If you had a strong year (bonus, moonlighting, locums work, side income), your payment at the next recertification reflects that. Even if your income drops back down the following month, the calculation already locked in the higher number. I've seen physicians get hit with this after a lucrative locums stretch. The extra income was temporary. The payment increase was not.
Household size and filing status. Getting married, divorced, adding a dependent, or changing tax filing status can all shift your payment. Some IDR plans use household income if you file jointly. Others may treat spousal income differently depending on the plan and your state. A borrower who got married and filed jointly without checking the impact saw their payment double overnight. Not because they earned more, because the income definition changed.
Loan type and balance coverage. Not every IDR plan covers every loan type. Parent PLUS loans, for example, have limited IDR eligibility. If part of your portfolio doesn't qualify for the plan you selected, those loans stay on a different repayment track, often with a higher payment. You might think you enrolled your full balance into IDR, but only a portion qualified.
Interest accrual and stability risk. Even if your required payment looks manageable, interest may be accruing faster than you're paying it down. That's not a payment spike in the traditional sense, but it's a balance spike, and it creates a different kind of surprise. Some IDR plans subsidize unpaid interest better than others. If you picked the wrong one, your balance grows quietly while you're focused on the monthly number.
The point: a "low payment today" plan can become a "high payment next year" plan if you didn't model the drivers.
Plan-by-Plan Pitfalls: Where Applicants Most Often Go Wrong
Let me walk through the specific mistakes I see repeatedly.
Pitfall #1: Selecting an IDR plan you don't fully qualify for. You fill out the application, get enrolled, and assume your whole portfolio is covered. Then you notice one loan group is still on the standard plan with a payment three times higher. That's because not all loans are eligible for all IDR plans. Before you submit, verify every loan type in your portfolio against the plan's eligibility rules.
Pitfall #2: Ignoring income-source complexity. W-2 income is straightforward. Self-employment income, contract work, variable monthly earnings, those create documentation headaches. If your income is irregular, the servicer may use a different basis to calculate your payment, and delays in providing documentation can trigger a temporary payment increase or even a switch to a standard repayment amount. Know what documentation you'll need and how your income type is treated.
Pitfall #3: Forgetting timing. Late recertification is a silent killer. If you miss your recertification deadline, your servicer can place you on a standard repayment plan temporarily, or permanently, depending on the situation. That standard payment is almost always much higher. I've seen borrowers miss a deadline by two weeks and get hit with a payment that was triple their IDR amount. Calendar the deadline. Set two reminders.
Pitfall #4: Not accounting for past plan changes. If you've switched IDR plans before, your recalculation may not behave the way a first-time enrollee's would. Switching plans can reset certain counters, change which income year is used, or affect progress toward any forgiveness timeline. Don't assume the new plan starts fresh with the same assumptions.
Practical guardrails:
- Verify eligibility for every loan in your portfolio.
- Confirm which loans are included before you submit.
- Review recertification deadlines and set calendar alerts.
- Check whether your current income documentation will still be valid at the next recertification window.
Illustrative only, not an official quote. Your actual payment depends on your specific inputs.
Notice how Plan B starts lower but spikes higher under the +25% scenario. That's the trap. The "cheapest" plan today isn't always the cheapest plan at recertification.
What to Do Instead: A Safer IDR Selection Checklist (Before You Click Submit)
Don't guess. Run the checklist.
Step 1: Gather the right inputs. Pull your most recent tax return (or alternative income documentation if you're not using one). Note your AGI. Count your household size, include dependents as defined by the plan's rules, not just who lives with you. List every loan type in your portfolio, including disbursement dates and current balances. Don't estimate. Get the actual numbers.
Step 2: Validate eligibility and coverage. Cross-reference each loan type against the IDR plan's eligibility criteria. If you have older loans, consolidations, or Parent PLUS loans, check whether they qualify. If only part of your portfolio is eligible, you need to know that now, not after enrollment.
Step 3: Do a recertification stress test. Model at least one plausible change before your next annual recertification. What if your income increases 20%? What if you get married and file jointly? What if you add a dependent? Run the numbers for each scenario. If any of them produces a payment you can't absorb, that plan isn't safe, no matter how low the starting payment looks.
Step 4: Confirm timing and documentation readiness. Find your recertification date. Write it down. Set a calendar alert 60 days before it and another 30 days before it. Gather the documentation you'll need now, don't scramble later. If your income documentation is time-sensitive (pay stubs, profit/loss statements), note when it will expire.
Step 5: Use official calculators, but don't blindly trust them. The Department of Education's Loan Simulator and your servicer's calculators are useful tools. But they're only as good as the inputs. Cross-check their output against your own math. If the number looks surprisingly low, ask yourself why. A surprise-low number is often a sign that the calculator used an input you didn't verify.
After Enrollment: How to Prevent Payment Surprises Later
Enrollment isn't the finish line. It's the starting line.
Stay ahead of recertification. Set alerts. Confirm your servicer processed your enrollment correctly, don't assume silence means success. Log into your account within 30 days of enrollment and verify that your payment amount, plan name, and included loans match what you applied for. If anything looks off, contact your servicer immediately. The longer you wait, the harder it is to fix.
Watch for red flags after enrollment:
- Unexplained payment increases within the first few months.
- Missing documentation notices you weren't expecting.
- Loan groups that don't appear to be on the IDR plan you selected.
- A payment amount that doesn't match what the calculator estimated.
Know what to verify each cycle. Every recertification, check whether your payment calculation used the income year and household information you intended. Servicers make errors. Borrowers make errors. The system isn't flawless. Your job is to catch mismatches early.
If something looks wrong, act immediately. Request a written explanation of how your payment was calculated. Document every communication, dates, names, reference numbers. If errors persist and your servicer isn't resolving them, escalate. File a complaint with the Federal Student Aid Ombudsman if needed. Don't let a processing error cost you months of overpayment.
Illustrative risk timeline. Actual timing varies by borrower and servicer.
The highest-risk moments are the recertification window and the payment recalculation point. That's where most surprise spikes happen. Be vigilant there.
Bottom Line: Choose IDR Like a Mistake Avoider, Not a Guessing Player
Don't click based on headlines. Don't pick a plan because your friend pays nothing on it. Don't trust the first number a calculator spits out without checking the inputs.
Your goal is predictable required payments, fewer surprises, and correct plan alignment. That means forecasting your math, stress-testing your inputs, and calendaring your recertification deadline before you submit, not after.
Do this now: run the checklist above. Gather your inputs. Model one income-change scenario. Set a calendar alert for your recertification date. Ten minutes of preparation beats six months of overpayment.