I watched a spine surgeon in Dallas sign a $100,000 sign-on bonus on a Tuesday. By the next October, fourteen months later, he wired $75,000 back to the hospital system.
No lawsuit. No fight. He just lost. He left a toxic group, took a better offer across town, and got hit with a promissory note he thought was just "standard HR language." He called me panicked. Said the recruiter told him "nobody ever has to pay that back."
That recruiter was lying. Or maybe just doing her job. Because that bonus was never a bonus.
This article is for educational purposes only and is not financial advice, not legal advice, and not tax advice. Figures vary and every contract is different, so consult a qualified professional before you sign anything.
The Hospital's Secret Playbook: What Program Directors and C-Suite Executives Don't Tell You
Let me tell you what really happens when a hospital offers $75k, $100k, even $150k upfront for orthopedics, cardiology, gastroenterology, urology.
It's not generosity. It's leverage.
Hospital C-suites call it a "recruitment investment" but on their balance sheet, that money is a retention weapon. They know exactly what a failed search costs them in the highest paid specialties, $500k+ in lost OR revenue, locums coverage at 2x your rate, another 9-month search with a firm charging 30% of your first-year salary. A six-figure bonus is cheap insurance to lock you in.
Here's the secret playbook. HR and physician recruitment do NOT have a fixed number. They have a range, plus a discretionary bucket. I've sat with Chairs who had $25,000 approved, plus another $50,000 they could pull from a "hard-to-recruit" contingency fund without ever going back to finance. The first offer is never their best offer. It's a test.
Recruiters are trained to say, "This is what we offer everyone at your level." Complete fiction. In high-margin specialties, I've seen the same system offer two interventional cardiologists six weeks apart $30k differences in sign-on, just because one asked and one didn't.
And they love to bundle. They'll slide relocation, sign-on, and early salary advance into one fuzzy number to make it sound massive. You think you're getting $100k bonus + $20k relocation. What you're actually signing is a single $120k promissory note with one repayment trigger. They do that on purpose. Harder to unwind.
If you're in a top 5 earning specialty, you are a profit center. Act like it.
Deconstructing the Clawback: The Trap Behind the Upfront Cash
That "bonus" in your offer letter? Flip to Exhibit B or C. Read the fine print. It almost always says "Promissory Note" or "Forgivable Loan."
That's the language that matters. It is not a gift. It is a zero-interest loan the hospital forgives over time. If you leave early, you don't just lose future money. You owe them cash. Real cash. Due in 30, sometimes 90 days.
Let me break down the two structures you'll see.
Cliff Vesting: The Killer. This is the most aggressive and, unfortunately, the most common for new grads who don't know better. It says: $100k bonus forgiven after 24 months of continuous full-time employment. If you leave at month 23 and day 29? You owe the entire $100k back. No pro-rating. One hundred percent clawback. I've seen this crush surgeons who left because their RVU targets were unattainable or their call was 1:2 instead of the promised 1:4. Doesn't matter. You left. You pay.
Pro-Rata Amortization: The Standard You Should Demand. The note is forgiven in equal monthly installments. $100k over 24 months = $4,166 forgiven per month. If you leave at month 14, you owe 10 months back, about $41,660. Still painful, but not fatal. The best groups will even do quarterly forgiveness, which is effectively the same thing and easier to track.
Now the part no recruiter explains until you ask directly: what happens if THEY fire YOU?
Most boilerplate contracts say: if you resign voluntarily, or are terminated for cause or without cause, the full unvested amount is due. Read that again. Without cause. That means they can decide they don't like your productivity, your fit, or they lose a contract with an insurer, terminate you without cause with 90 days notice, and THEN send you a bill for $75k.
That's not a hypothetical. I've seen a pain management doc in Florida get terminated without cause 11 months into a 2-year forgiveness period. System over-hired. He owed $60k back 30 days after losing his job.
You want the language flipped: Repayment triggered only if you resign voluntarily or are terminated for cause. If they terminate you without cause, the note should be fully forgiven. If that's not in writing, it doesn't exist.
The Negotiation Blueprint: Securing the Bag Without Signing Your Life Away
You can negotiate this. You absolutely should. Here's exactly how I tell fellows in high-paid surgical and procedural specialties to redline it.
1. Unbundle the money. First counter is always separation. Say this: "I appreciate the $120k total. Can we structure it as $80k sign-on governed by a forgivable loan, and $20k relocation as a straight reimbursement not subject to repayment, plus $20k as base salary?" HR often has flexibility to move relocation dollars to a non-clawback category. That instantly cuts your exposure.
2. Kill the cliff. Demand pro-rata monthly. Do not accept 100% forgiveness at 24 months. Your redline should read: "The Loan shall be forgiven in 24 equal monthly installments commencing on month one." If they won't do monthly, ask for quarterly. If they insist on a cliff, walk. It tells you everything about how they treat early attrition.
This matters so much because life happens. Your spouse hates the city. Your Chair is a nightmare. Your case volume is half what they promised. You need a pressure valve, not a financial prison.
3. Fix the termination trigger. This is the hill to die on. Cross out "terminated with or without cause" and insert "terminated for Cause as defined in Section 7(b)." Add a sentence: "If Physician is terminated by Employer without Cause, or if Employer does not renew the agreement, any remaining balance of the forgivable loan shall be fully forgiven and no repayment shall be due."
Send that to your attorney. Watch how fast the hospital blinks. They've seen it before from experienced hires. They're just hoping you're a first-time signer who won't push.
4. Cap the repayment window and method. Never agree to repay within 30 days. Push for 12 months, or at minimum 180 days, with no interest. And add: "Repayment shall be made via pre-tax dollars if possible, or net of taxes withheld if repayment occurs in a subsequent tax year." Otherwise you're paying back $100k you only got $60k of after taxes.
Here's the risk difference in real terms:
That last bar is where you want to be. Low risk. Mobility intact.
Protecting Your Exit Strategy: The Insider Verdict
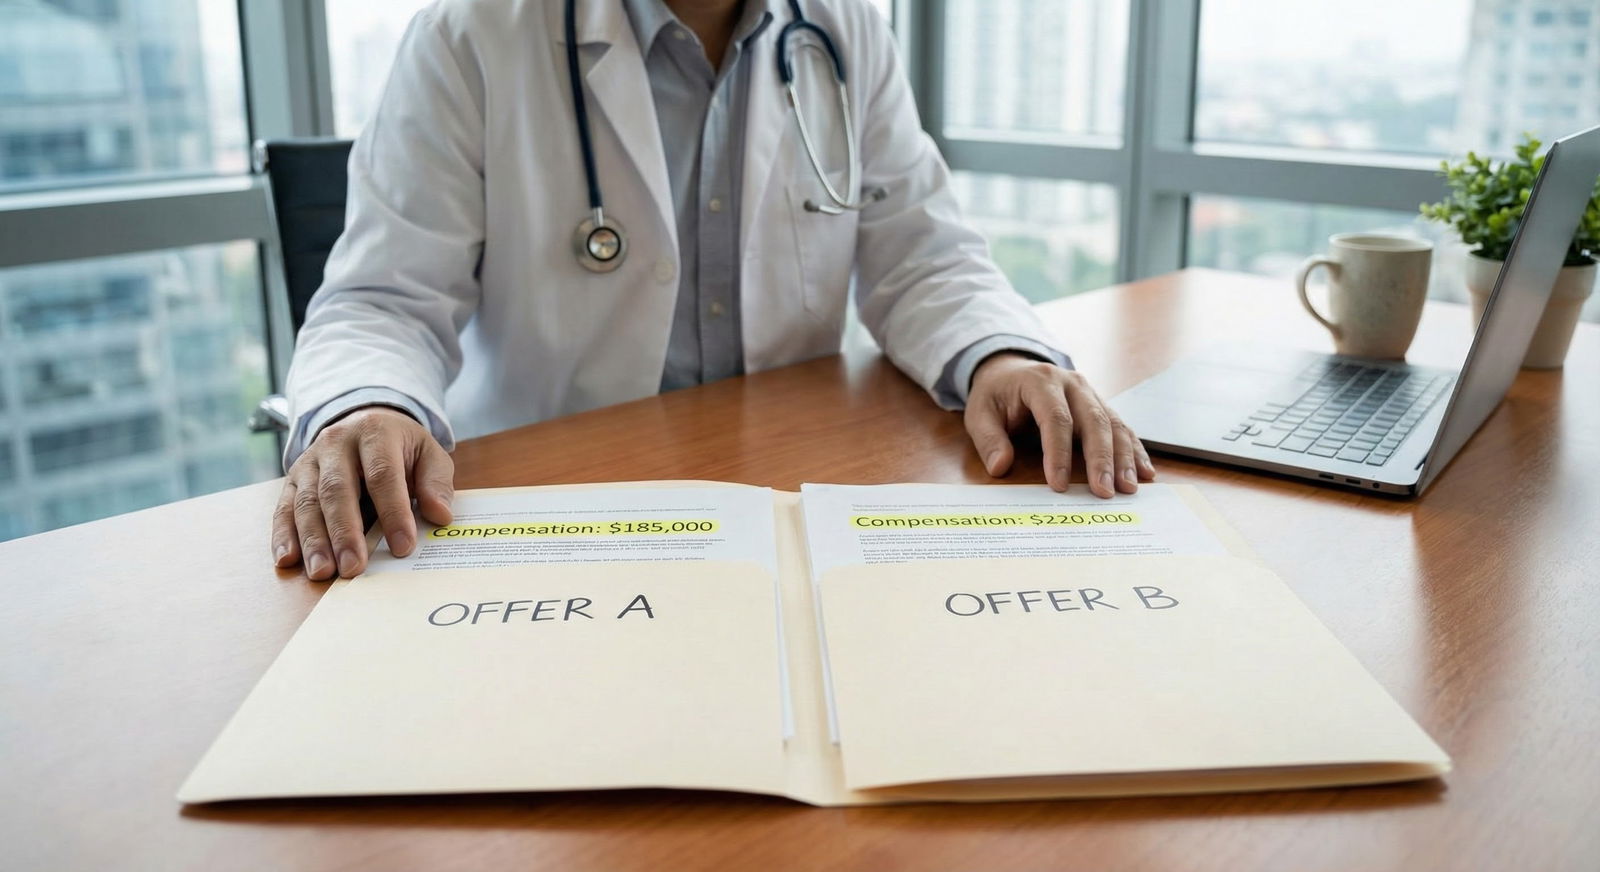
I recently worked with a vascular surgeon, let's call her Sarah. Two offers. Offer A: $200k base + $100k sign-on with 2-year cliff. Offer B: $210k base + $50k sign-on, pro-rata monthly, with a for-cause-only trigger.
On paper, Offer A looked $40k richer. Over two years? Sarah took Offer B. Why? She ran the math. If Offer A's OR block time didn't materialize and she had to leave at month 15, she'd be writing a $100k check. Offer B? She'd owe about $18k. That $22k difference in base covered the rest.
She also did the other smart move: she shifted money from bonus to base. Recruiters hate this because base salary is a long-term budget commitment; bonuses are one-time recruitment dollars. But for you, base is better. It compounds. It's not clawed back. It's taxed normally and flows into your retirement match and disability policy. A $20k bump in base is worth more than a $25k sign-on that you might have to repay.
And let me be blunt about taxes. That $100k? You'll get maybe $58k-$65k after federal, state, and FICA. If you have to pay it back the next calendar year, you paid tax on money you didn't keep. You have to chase it back via a tax deduction claim under IRC 1341, it's a mess. Your CPA will hate you. Never take a huge sign-on in December if you can avoid it.
Here's the final reminder from someone who has seen a dozen young attendings get burned: Nobody reads your contract for you. Not the friendly recruiter. Not the Chair who says "we're like family." Not your residency PD who wants you employed.
Your employment agreement is the single most important document of your early career. More important than where you trained. That sign-on bonus feels like validation after years of being underpaid. I get it. You earned it.
But free money has hooks. Make sure you file down the hooks before you take the check.