You just signed. Or you're about to. That hospitalist contract lands in your inbox at 11 PM after a 28-hour call block, and buried on page 12 is a single checkbox that will cost you $20k-$40k if you get it wrong: W-2 Employee or 1099 Independent Contractor.
Most new grads skim right past it. Don't.
Your first-year tax burden isn't determined in April. It's determined now. Long before your first shift.
This content is for educational purposes only and is not financial advice, not legal advice, and not tax advice. Every contract figures vary, and tax outcomes depend on state, entity, and individual facts, so consult a qualified professional before you decide.
The Hospitalist Timeline: Pre-Employment Tax Planning Foundation
At this point, 6 to 9 months before your first attending shift, you must evaluate your hospital's initial contracting offer structure. Seriously. Not 2 weeks before start. Not during orientation.
Hospitals love W-2. It's clean for them. They withhold. They control. For you, it can be expensive simplicity. 1099 offers flexibility and massive deduction potential, but only if you build the infrastructure in time.
Here is your pre-employment timeline:
9 Months Out (March-April for July starters):
- Request both versions of the offer if available. Some groups will flex. Ask: "What would this look like as 1099?" I've seen hospitalists gain a 15-20% gross bump just by asking.
- Calculate the real W-2 value. Benefits matter. Health insurance, employer 403b match, malpractice with tail, CME allowance, PTO. A $285k W-2 with $45k in benefits is not the same as a $300k 1099 naked.
6-7 Months Out:
- Model two scenarios. W-2 vs 1099. At this point you should be running actual numbers, not vibes.
- Get a CPA who works with physicians. Not your cousin. Not TurboTax. A real physician CPA.
3-4 Months Out:
- If going 1099, you must form your entity now. Not later. Delaware can wait. Form in your practice state.
Checklist for Auditing W-2 Withholding vs 1099 Gross Projection:
- W-2 Side: What is federal + state withholding? Is it enough if your spouse also works? Are you filing jointly for the first time? What is your projected taxable income after standard deduction ($30k joint in 2025)?
- 1099 Side: What is your gross? Subtract self-employment tax (15.3% on ~92.35% of net). Subtract business expenses. Subtract health insurance. Subtract retirement plan contributions. What's left is real take-home.
- Common trap: That $320k 1099 offer looks $35k better than $285k W-2. After you pay both halves of FICA, your own health insurance at $1,400/month, and zero PTO when you get COVID in December, it's often a wash. Unless you use the S-Corp strategy.
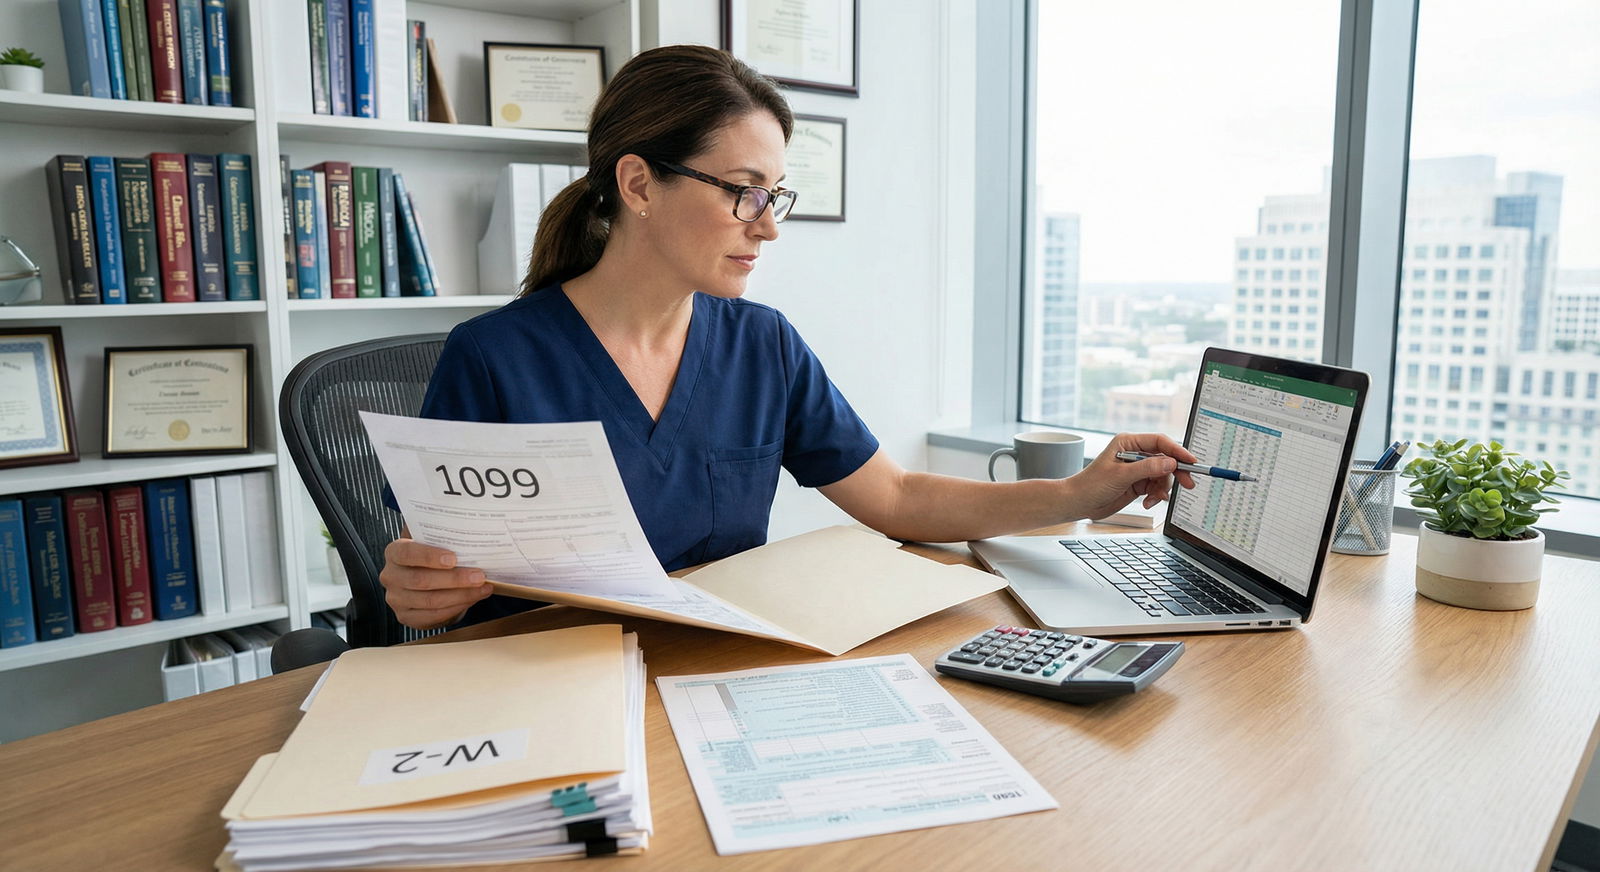
Months 1-3: Setting Up Your 1099 Infrastructure vs. W-2 Onboarding
This is where people blow it. The first 90 days set your compliance for the entire year.
If You're W-2: Day 1-30
At this point, if you are W-2, verify your W-4 withholdings to avoid unexpected Q1 underpayment penalties. HR will hand you a default W-4. That default assumes you have one job, no spouse income, and love giving the IRS an interest-free loan.
- Week 1: Submit new W-4. Use IRS withholding calculator. If your spouse makes $150k+ as an attending, you need extra withholding. Check Box 4(c).
- Week 2: Confirm benefits enrollment: 403b/401k, HSA, disability. At this point you should max that HSA if offered. Best tax triple-play available. $4,150 individual, $8,350 family for 2025.
- Week 4: Set up direct deposit and check your first paystub. Gross vs net should not be a surprise.
W-2 is autopilot. That's its appeal. And its limit. You get standard deduction. You get limited pre-tax retirement ($23,500 401k). You can't deduct your scrubs, your USMLE receipts, or your mileage to that satellite hospital.
If You're 1099: Day 1-90 Is Infrastructure Season
This is not casual. Miss a step and you pay.
Day 1 through Day 14: Entity
- Form LLC, elect S-Corp if projected net > $200k. In most states, this saves you $8k-$12k in self-employment tax year one. I tell every 1099 hospitalist making over $250k: S-Corp is not optional. It's the whole game.
- File IRS Form 2553 within 75 days of LLC formation. Miss that window and you're stuck as disregarded entity for the year.
Day 15 through Day 30: Bank
- Open business banking accounts. Separate. Completely separate. Business checking + business credit card.
- Open Solo 401k at Fidelity/Schwab. At this point you should not wait until December. Open now to fund along the way.
Day 30 through Day 90: Tax Discipline Weekly breakdown of estimated quarterly tax payment deadlines (IRS 1040-ES) for new 1099 hospitalists:
- Q1 was April 15 (you probably weren't earning yet)
- Q2: June 16, 2025 (this one will hit you mid-orientation)
- Q3: September 15, 2025 (your first big hit)
- Q4: January 15, 2026 (covers your Oct-Dec income)
Pay quarterly. Actually pay. The penalty for underpayment is not huge, but the bill in April when you owe $35k all at once? That hurts. Set up auto-transfers: 35-40% of every 1099 check straight to a separate tax savings account. Do not touch it.
Months 4-9: Mid-Year Deductions, Business Expenses, and Cash Flow Audits
At this point in your first attending year, you should conduct a mid-year expense audit for your 1099 practice. July has passed. You've got 3-4 months of real attending income. Look at the books.
For W-2 docs, mid-year is simpler. At this point you should confirm you're on track to max your retirement and that your withholding still makes sense after that moonlighting gig paid you an extra $18k in July.
For 1099, this is where you win back thousands.
Maximizing write-offs unique to hospitalists:
Don't do what I see every new 1099 do: claim $200 for coffee and forget the $8k stuff.
- Malpractice + tail: $8k-$15k fully deductible. If your hospital doesn't cover tail and you're 1099, you pay it. Deduct it.
- Licensing, DEA, board exams, credentialing: $3k-$5k year one. Every dollar.
- CME travel, not just registration: Flight to SHM, hotel, 50% meals. Keep receipts. $3k-$6k typical.
- Health insurance premiums + HSA: Deductible above the line if self-employed. $10k-$20k family.
- Home office - actual use: That 120 sq ft spare room you use exclusively to chart and manage your business? Pro rata rent, utilities, internet. Not huge, but legitimate. Don't invent a home hospital.
- Mileage between sites: If you cover two hospitals in one day as 1099, that mileage (67 cents/mile in 2025) is deductible. W-2? Zero.
Now the big lever: S-Corp reasonable salary strategy.
Example: $300k gross 1099 income. After $25k expenses, $275k net profit.
- W-2 path at same hospital: $285k salary, net after tax, benefits, $23.5k 401k contribution: ~$195k-$210k take-home depending on state.
- 1099 with S-Corp: You pay yourself $170k W-2 salary from your S-Corp. The remaining $105k is distribution, not subject to 15.3% self-employment tax. That's a $16k instant saving. Add Solo 401k: you can do $23.5k employee + ~$30k employer profit-sharing up to $70k total. W-2 can't touch that.
That's the math that matters. Not gross. Net keep. For same work.
Months 10-12: Year-End Tax Closing, Retirement Contributions, and Final Adjustments
Month 10 is not downtime. It's your last real chance to move the needle before Dec 31 traps you.
Month 10 Checklist:
- Finalizing retirement account contributions (Solo 401k, SEP-IRA, or employer 403b/401k). At this point you should know your year-to-date profit. For 1099 S-Corp, you have until year-end to fund employer portion of Solo 401k. Don't leave $20k-$30k of tax-deferred space on the table because you forgot. Solo 401k beats SEP-IRA for most hospitalists under $400k because it allows the Roth and larger contribution at lower income.
- W-2 folks: Check if you're leaving 403b match. I've seen residents leave $4k of free money by not hitting 5% before Dec 31. Fix it now.
- Audit your bookkeeping. QuickBooks, spreadsheet, whatever. But clean. Every transaction categorized.
Month 11:
At this point, 60 days before the tax deadline, execute final loss-harvesting and asset depreciation strategies.
- Do you need a new laptop, tablet for rounding? Buy before Dec 31. Section 179.
- Pay all outstanding business bills, licensing renewals early. Prepaid 2026 professional expenses deductible in 2025 if cash-basis.
- If you had a low income quarter (took unpaid time), consider Roth conversion.
Month 12: Year-End Reconciliation Guide
Step-by-step to give your CPA clean books:
- Reconcile three accounts: business checking, business credit card, tax savings. Should match profit & loss.
- Gather 12 monthly statements + mileage log + CME receipts.
- List health insurance premiums paid Jan-Dec.
- Confirm S-Corp payroll: W-2 issued, payroll taxes filed (Form 941). If you ran payroll through Gusto, download annual report.
- Calculate Q4 estimated payment due Jan 15. Don't wait for CPA in March to tell you.
For W-2, your checklist is shorter: Download final paystub, W-2, 1095 proof of insurance, 403b contribution summary. Done.
The Bottom Line on First-Year Choice
At this point in your career transition, tax structure choice dictates up to 15% of your net first-year attending income. That's not hype. That's a Solo 401k that wasn't funded. That's quarterly penalties. That's paying employee AND employer FICA for no reason.
W-2 is simplicity. Automated. Great if you value Predictability and employer benefits, and your group already covers malpractice tail + great match. Bad if you want control.
1099 is leverage. Harder. Requires discipline. But unlocks massive deductions and retirement space you simply cannot get as W-2. Good if you will run it like a business. Bad if you hate paperwork.
Your move:
- Run both models with actual state taxes this week.
- Pick your entity path in the next 14 days.
- Set calendar reminders for June 16, Sept 15, Jan 15 if you're 1099.
- Get that CPA call booked now, not in March when they won't return your call.
First year attending income only happens once. Make the IRS take less of it than your student loan servicer.
Ready to lock your structure? Pull your contract, grab your last 3 bank statements, and book a 30-minute tax modeling session with a physician-focused CPA before your next block starts.