It is 2:00 AM, and I am staring at an offer letter that could either set me up for life or quietly ruin my future.
I have spent over a decade in school and residency. I carry a mountain of student debt, well over $300,000, and I am starting my earning years dangerously late compared to everyone else my age. I cannot afford to make a mistake here. But as I look at the compensation structure on this contract, my stomach drops. One job offers a high guaranteed salary. The other offers a lower base pay with a massive "production bonus" attached to wRVUs.
What if I choose wrong? What if the bonus structure looks incredible on paper, but six months in, patient volume drops, clinic schedules collapse, or the hospital changes the wRVU conversion rate? Suddenly, that shiny $400,000 package shrinks into a $200,000 base. Even worse, what if my retirement contributions are tied only to that miserable base salary? I lie awake imagining the worst-case scenario: working myself to the bone, chasing production targets, only to realize a decade later that my retirement account is severely underfunded. Is a predictable, salary-only plan the only true safe haven, or can a bonus-heavy model actually shield doctors better if things go right?
This article is for educational purposes only and is not financial advice, not legal advice, and not tax advice. Specific figures vary by institution and contract, so you should consult a qualified professional before making any binding career or financial decisions.
What 'Bonus Heavy' vs 'Salary Only' Really Means in Doctor Compensation
Let's strip away the recruiters' slick pitch decks and look at what these contracts actually force you to trade off.
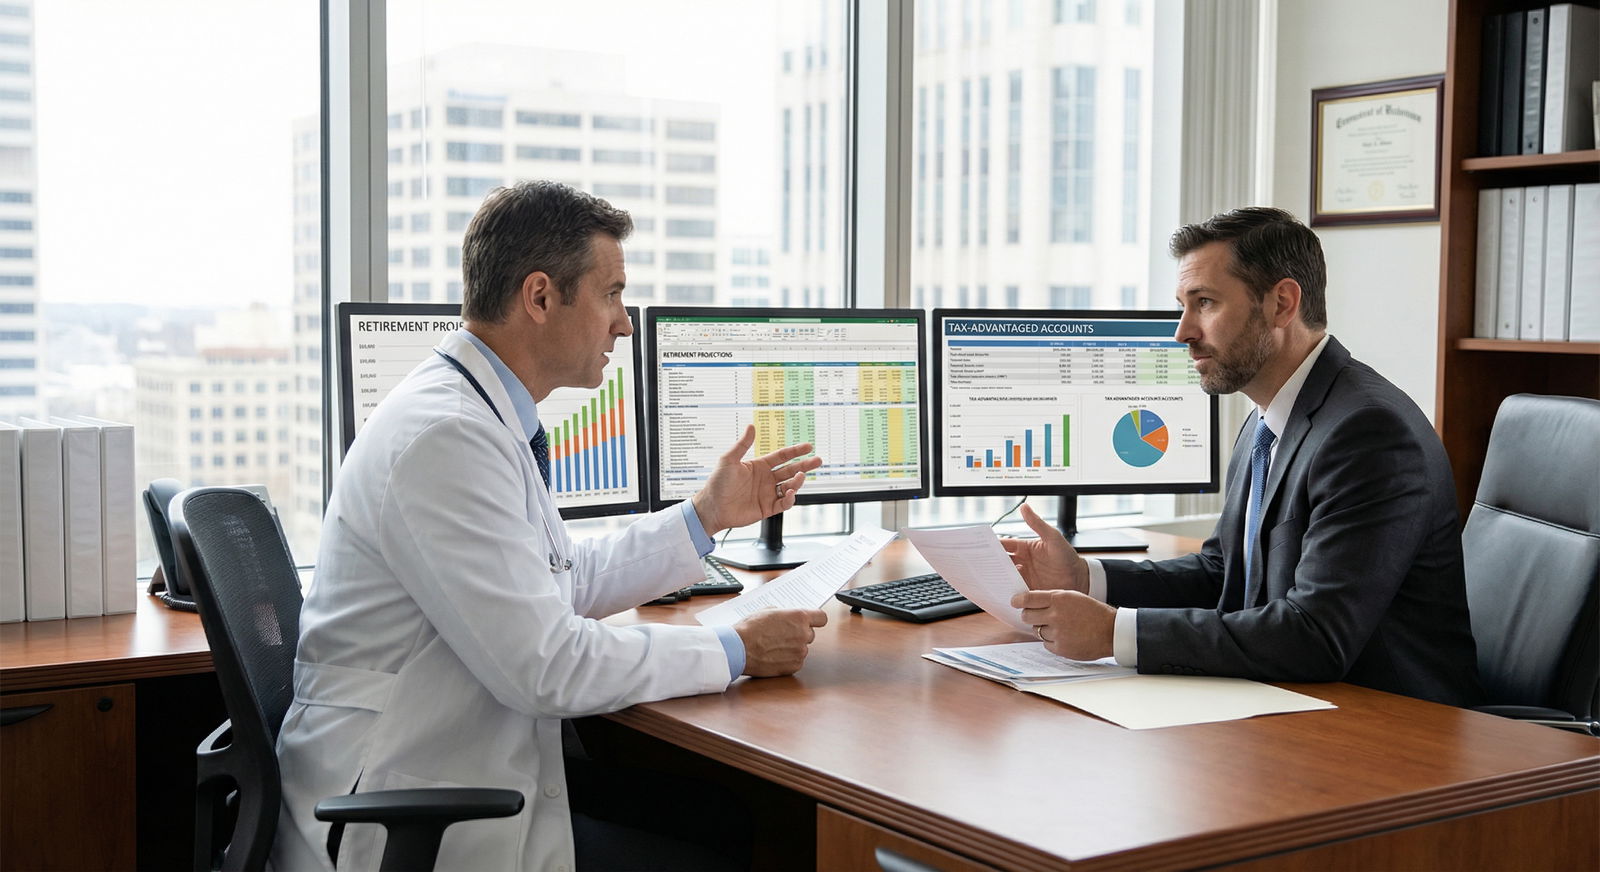
A salary-only compensation model is straightforward. You get a fixed, predictable dollar amount every single pay period. No wRVU tracking. No monthly production stress. No staring at the schedule wondering if a rash of patient cancellations will tank your paycheck. If the clinic has a slow month, you get paid the exact same amount.
A bonus-heavy model, on the other hand, pairs a lower base salary, sometimes 30% to 50% below market average, with variable financial incentives. These incentives might be tied to productivity (wRVUs), quality metrics, patient satisfaction scores, or call coverage. You might see a base pay of $220,000 with the "potential" to earn $450,000 if you hit high production tiers.
Why does this keep me up at night? Because your retirement plan doesn't exist in a vacuum. Your employer's 401(k) or 403(b) match, your Income-Driven Repayment (IDR) student loan math, and your taxes all react differently to these two structures. If your hospital matches 5% of your pay, do they match 5% of your total cash compensation, or just 5% of your lower base salary? That single line in the fine print could cost you hundreds of thousands of dollars over a 30-year career.
How Each Plan Can Affect Retirement Security
The anxiety multiplies when you realize how much can go wrong under the hood of a retirement plan.
If you take a bonus-heavy job, your retirement funding can become an emotional roller coaster. During a booming year, you might max out your retirement accounts early and pocket massive extra cash to throw into taxable brokerage accounts. That sounds dreamlike. But what happens during a bad year? What if you get sick, take parental leave, or suffer severe burnout and have to dial back your clinic hours? Your production bonus vanishes. If your budget was built around that bonus, your retirement savings are the very first thing you'll cut.
There is also a terrifying hidden tax trap with bonus-heavy plans. Many corporate employers calculate their matching retirement contributions on base salary only. If you earn a $200,000 base and a $200,000 bonus, and your employer offers a 4% match on "eligible compensation," you might assume you are getting 4% of $400,000 ($16,000). But if the contract defines "eligible compensation" as base pay alone, you only get $8,000. They just cut your retirement match in half.
The salary-only model feels like a giant security blanket by comparison. You know down to the penny what hits your checking account every month. You can automate your 401(k), Backdoor Roth IRA, and debt payments without second-guessing whether next quarter's wRVU reconciliation check will clear. But the downside is real, too: you cap your upside. If you end up seeing twice the patient volume of your peers, you don't get a single extra dime toward your retirement. You are subsidizing the health system's bottom line while your own wealth building stays at a flat baseline.
My absolute worst-case fear? Taking a bonus-heavy contract with a headline target of $420,000, burning out after two years of chasing unreachable wRVU quotas, making only the base pay of $230,000, and realizing my employer matched a meager percentage of that lower number the entire time.
Which Plan Protects Doctors Better in Real Life?
Neither plan is a magic shield. The truth is terrifyingly nuanced: protection isn't determined by the compensation title, it's buried deep within the contract terms and your own personal psychological limits.
A salary-only plan protects you better if:
- You are in early career with massive debt and need absolute predictability for student loan payments.
- You are entering a specialty or geography with unpredictable patient volume.
- You know that income anxiety causes you real distress, making you prone to overwork or burnout.
- The hospital's retirement plan caps matches tightly regardless of total earnings.
A bonus-heavy plan protects you better if:
- The employer explicitly calculates 401(k)/403(b) matches and non-elective contributions on total W-2 earnings, not just base pay.
- You are an efficient producer in an established clinic with a years-long patient waiting list.
- You possess strict financial discipline, meaning you live entirely off the base salary and automatically route 100% of bonus checks straight into retirement and investment accounts.
You have to inspect the fine print like a detective searching for a motive. Check the vesting schedule. If an employer promises a generous 6% match on your massive bonus-heavy earnings, but requires a 5-year cliff vesting schedule, you walk away with zero employer dollars if you burn out and leave in year three.
How Doctors Can Reduce Risk Before Signing
You do not have to walk blindly into a financial trap. Before you put ink on any contract, you can take control and force clarity out of the employer.
First, stop looking at headline numbers. A recruiter telling you "our doctors usually make $450,000" means nothing. Ask to see the actual distribution: What did the 25th percentile earner make last year? What did the newest hire make in year one?
Second, demand written answers to these exact contract questions:
- Is employer retirement matching calculated on base salary alone, or total W-2 cash compensation?
- Are production bonuses paid monthly, quarterly, or annually? (Quarterly or annual payouts mean you lose interest growth while waiting for your own money).
- What is the vesting timeline for employer retirement matches?
- Is there a true-up provision for the 401(k) match if you hit IRS contribution limits early in the year?
Finally, build your own personal safety net before relying on theirs. If you take a bonus-heavy role, construct your budget entirely around the base pay. Pretend the bonus does not exist. If it comes through, great, it goes straight to your retirement portfolio. If it disappears, your life doesn't fall apart, your loan payments don't bounce, and your baseline retirement contributions keep ticking quietly in the background.
The goal isn't to chase the flashiest compensation headline on Reddit. The goal is to pick the contract structure that lets you sleep peacefully at night, knowing your future self is safe no matter what happens to the schedule tomorrow.
Key Takeaways
- Check the Match Definition: Never assume a 401(k) match applies to your whole paycheck. Employers often calculate retirement matches strictly on base pay, neutering the benefit of a bonus-heavy plan.
- Budget for the Floor, Not the Ceiling: If you accept a bonus-heavy model, anchor your lifestyle and baseline retirement savings to your guaranteed base salary. Treat bonuses as pure investment acceleration.
- Predictability Has Real Value: For early-career doctors carrying heavy debt, the emotional and financial safety of a salary-only contract often outweighs the hypothetical upside of production incentives.