Senior attendings love to boast about complex surgical outcomes or landmark clinical trials. But sit down with a group of department chairs and veteran faculty after a grand rounds presentation, and the conversation shifts to an entirely different, far more uncomfortable topic: their complete inability to pass down their wealth without the IRS gutting it.
I have watched dozens of brilliant clinicians, physicians who spent 35 years diagnosing complex pathology, completely misdiagnose their own estate plans. They operate under a dangerous delusion. They assume the millions sitting in their 403(b), 401(k), and traditional IRA accounts will smoothly transition to their children, providing decades of tax-deferred growth.
That dream died on December 31, 2019.
To avoid unexpected tax liabilities, physicians should review strategies outlined in tax-efficient asset location for physician retirement portfolios.
When the SECURE Act quietly became law, it dismantled the cornerstone of physician wealth transfer: the traditional "stretch IRA." Before the law changed, your adult children could inherit a $3 million retirement account and stretch required distributions over their own life expectancies, taking modest, highly manageable annual payouts across 40 or 50 years.
That strategy is gone. Dead and buried.
Today, most senior physicians are still managing their wealth using estate playbooks written a decade ago. They are handing their heirs a massive tax bomb disguised as an inheritance. If you hold significant tax-deferred retirement accounts and plan to leave them to non-spouse beneficiaries, you are stepping directly into a trap engineered by Congress to siphon off nearly half of what you built.
Evaluating these choices early helps prevent complications discussed in 7 retirement planning mistakes physicians make in their first 5 years.
This article is provided for educational purposes only. The contents herein are not financial advice, not legal advice, and not tax advice. Specific figures vary based on individual circumstances and state jurisdiction; you should always consult a qualified professional to evaluate your personal financial picture.
Anatomy of the Trap: How the 10-Year Rule Decimates Physician Nest Eggs
The mechanics of the SECURE Act are ruthlessly simple. Non-spouse beneficiaries who inherit a traditional IRA or 403(b) must fully liquidate the account by December 31 of the tenth year following the account owner's death.
Ten years. No exceptions for high balances. No gradual stretching across a lifetime.
To make matters worse, IRS regulations now require annual distributions during those ten years if the deceased physician had already reached their Required Beginning Date (RBD) for Required Minimum Distributions (RMDs). You cannot simply sit on the account for nine years and wait.
Here is where the bracket-creeping nightmare hits physician families.
Think about where your adult children will likely be in their lives when you pass away. They will probably be in their mid-40s to late 50s. Their peak earning years. They might be senior attendings, corporate executives, or successful entrepreneurs already sitting comfortably in the 32%, 35%, or 37% federal tax brackets.
Now, force $200,000 to $400,000 of mandatory ordinary taxable income on top of their existing salary every single year for a decade.
Every dollar withdrawn from that inherited pre-tax account gets tacked directly onto the top of their income stack. Federal taxes eat 37%. State income taxes in states like California, New York, or Massachusetts swallow another 9% to 13%. Local taxes and net investment income surcharges jump in. Before your child touches a dime, nearly 50% of your life's work vanishes into government coffers.
The math is brutal. Under the old rules, a $2.5 million IRA stretched over 40 years generated steady wealth while remaining in lower tax brackets. Under the 10-year rule, that same $2.5 million account forced into high-earning years becomes a revenue extraction machine for the Treasury.
Behind Closed Doors: The Mistakes Attending Physicians Make While Alive
Why do smart doctors keep falling for this? Because they confuse earning power with financial sophistication.
The most catastrophic error I see senior attendings make is naming their adult children as direct primary beneficiaries on standard account forms, completely divorced from a coordinated estate plan.
If your child is a subspecialist surgeon making $700,000 a year, naming them as a direct beneficiary on your $3 million 403(b) is tax vandalism. You are guaranteeing that almost half of that account will be surrendered in taxes.
Worse yet, physicians trust standard estate attorneys who simply do not understand the intersection of high clinical income and retirement distributions. Most suburban estate attorneys write generic revocable living trusts. They insert standard conduit trust language that was popular ten years ago.
Under pre-2020 rules, a conduit trust passed RMDs straight through to the beneficiary while protecting the underlying principal. Under the 10-year rule, a conduit trust forces the entire trust balance out to the beneficiary by year ten. It completely destroys asset protection and triggers the maximum tax hit all at once.
Another silent killer: failing to update beneficiary forms after major life events. I've seen a division chief leave an inherited 401(k) to a child who was a third-year orthopedic resident. The child hit their peak attending salary right as the mandatory liquidation window opened. Zero tax planning. Hundreds of thousands in unnecessary losses.
Actionable Counter-Moves: How to Defeat the 10-Year Rule
You do not have to accept this outcome. The tax code gives you tools to strike back, but you must execute these moves while you are alive and healthy.
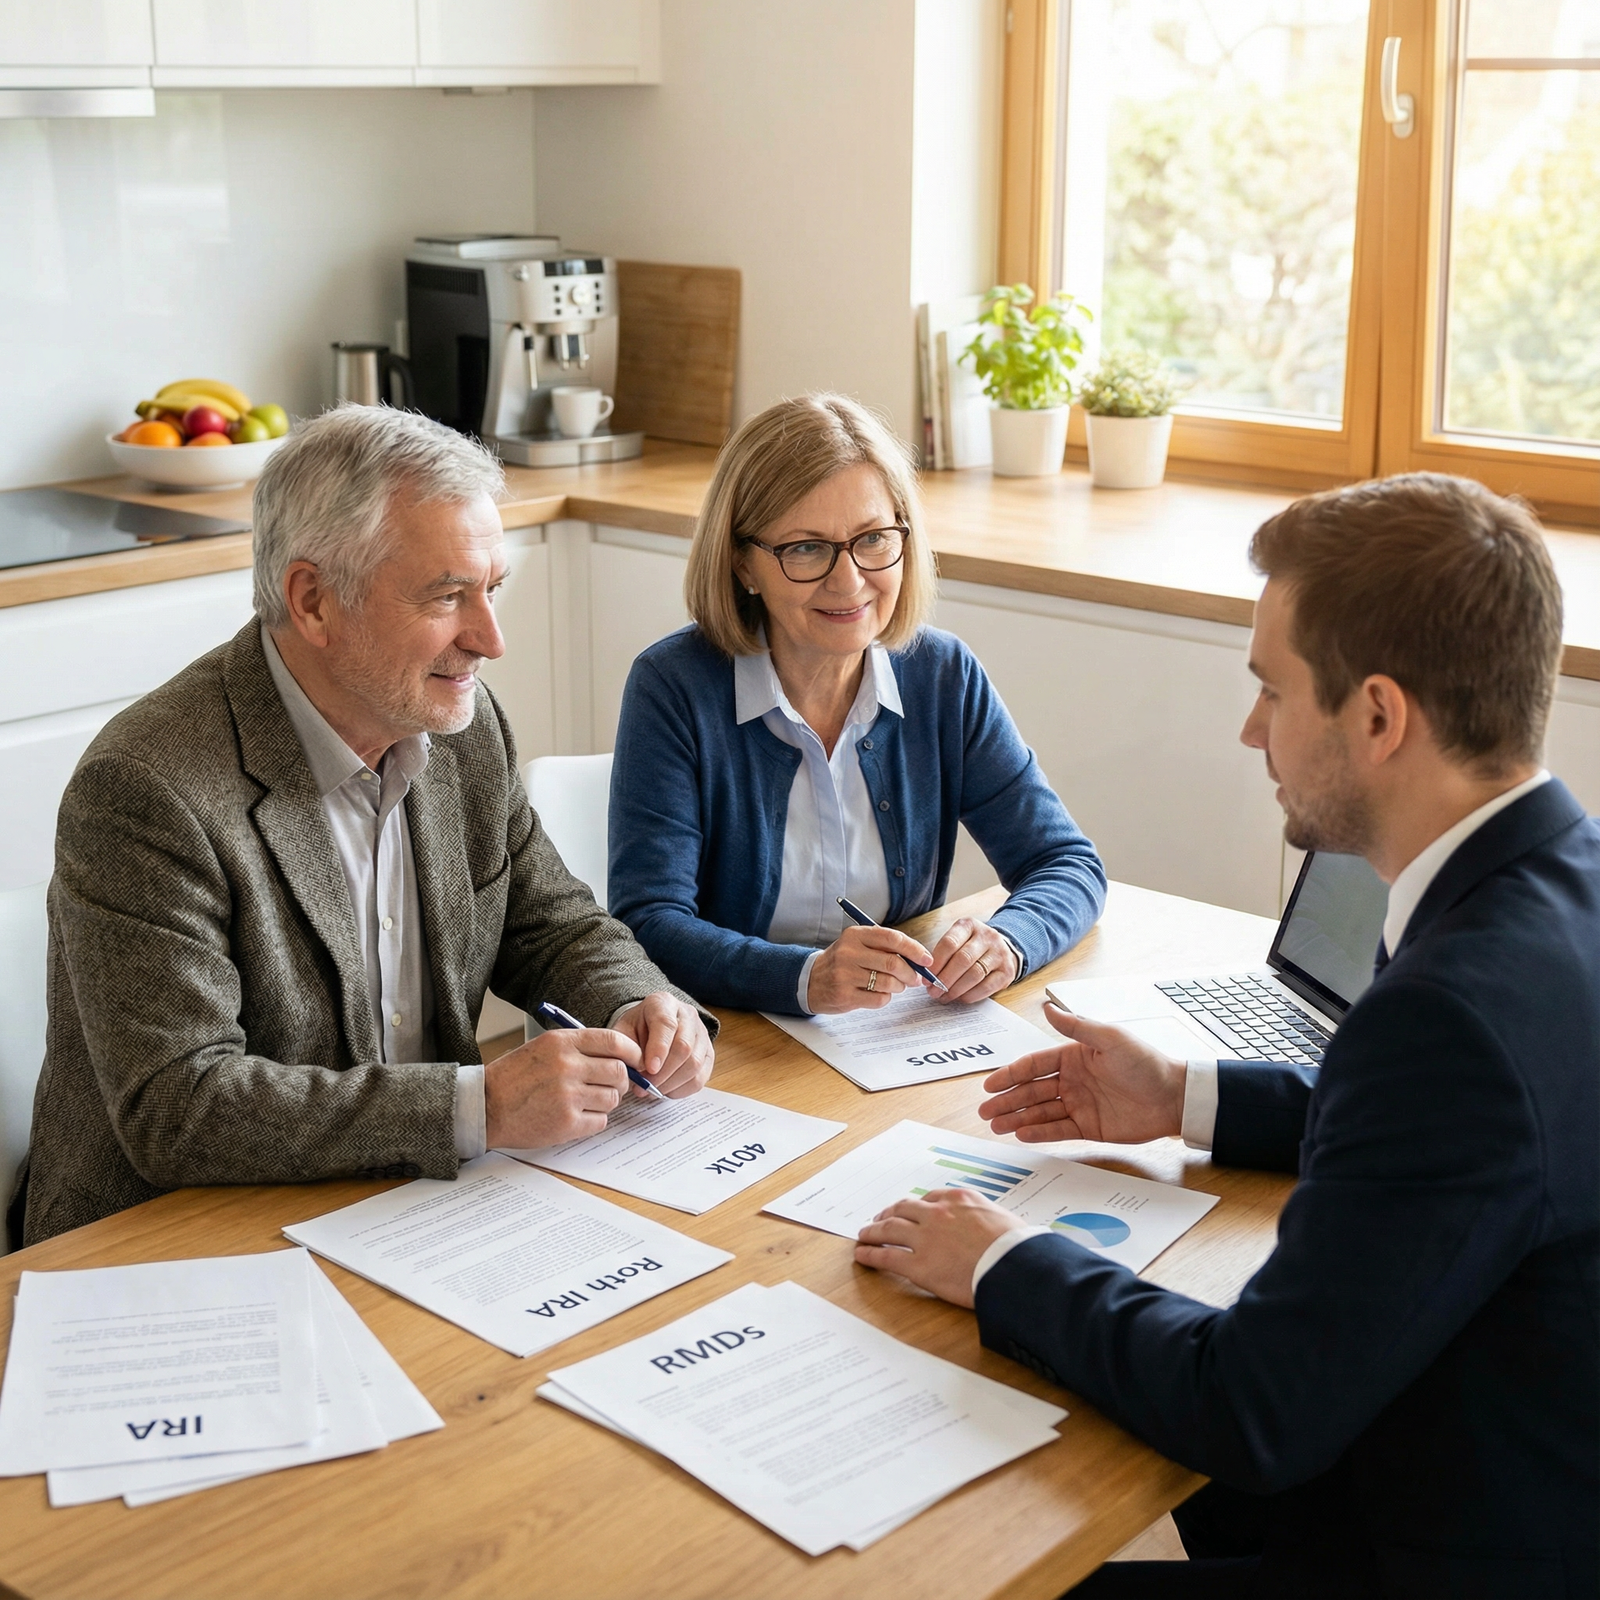
1. Execute Systematic Partial Roth Conversions
This is the single most powerful lever available to a retired physician.
Between the age you stop practicing medicine and the age mandatory RMDs kick in (age 73 or 75 under current law), your tax bracket will likely drop. This is your strategic window.
Convert portions of your traditional pre-tax 403(b) or IRA into a Roth IRA every year. You pay taxes on the converted amount today at your lower retired marginal rate (perhaps 22% or 24%), rather than forcing your heirs to pay at their peak rate (37%+).
Inherited Roth IRAs are still subject to the 10-year rule. However, distributions taken from an inherited Roth during those ten years are 100% tax-free. Your heirs can let the inherited Roth compound tax-free for nine years and 364 days, pull out the entire balance tax-free in year ten, and pay zero income tax.
2. Deploy See-Through Accumulation Trusts
If you want to protect the funds from divorces, lawsuits, or irresponsible spending, do not use a standard conduit trust. Use an Accumulation Trust.
An accumulation trust permits the trustee to take the mandatory withdrawals from the inherited IRA within the required 10-year period, but retain those funds inside the trust rather than forcing them out into your child's hands. While trust tax brackets are compressed, strategic distributions of trust income to lower-earning family members (like grandchildren in college) can smooth out the tax burden significantly.
3. Build a Life Insurance Liquidity Bridge
For high-net-worth attendings who cannot execute Roth conversions without spiking their current Medicare IRMAA premiums or income brackets, life insurance offers a clean workaround.
You can reposition taxable IRA distributions during your lifetime to fund a permanent life insurance policy housed inside an Irrevocable Life Insurance Trust (ILIT). When you pass, the life insurance policy pays out a completely tax-free death benefit to your heirs. This replaces the value lost to taxes on the remaining traditional IRA balance.
The Ultimate Legacy Blueprint: Securing Your Family's Financial Future
Building generational wealth requires operating like an executive. The biggest reason physician estate plans fail is professional fragmentation.
Your CPA files your taxes based on last year's figures. Your estate attorney drafts documents based on template laws. Your financial advisor manages assets for annual yield. None of them talk to each other unless you force them into the same room.
Break down these silos. Hold an annual meeting with your entire advisory team. Explicitly ask them: "If I die tomorrow, what is the exact tax rate my children will pay on my retirement accounts over the next ten years?"
If they cannot give you a clear, numbers-backed answer, you have the wrong team.
Leaving a legacy isn't about hoarding dollars. It's about protecting the sacrifices you made through 80-hour residency weeks, overnight call, and decades of high-stakes clinical decision-making. Don't let four decades of hard work end up as an avoidable windfall for the tax collector.
Key Takeaways
- The 10-Year Mandate: Non-spouse heirs must fully liquidate inherited pre-tax retirement accounts within ten years, eliminating the classic "stretch IRA."
- The Income Stacking Problem: Forcing large withdrawals during an heir's peak earning years pushes their distributions into top-tier federal and state tax brackets.
- Outdated Estate Tools: Traditional conduit trusts and simple beneficiary designations created before 2020 actively damage your legacy under current IRS rules.
- Proactive Defense: Partial Roth conversions during early retirement years and accumulation trusts are the primary mechanisms to neutralize the tax trap.