The Scenario: Eyeing Your First Investment Property While Wearing a Physician Loan
You did what every new attending does. You used a physician loan to buy your primary residence. Zero down. No private mortgage insurance (PMI). You kept your cash liquid and moved into a house you actually wanted to live in. It felt like a massive financial win.
Evaluating your debt thresholds correctly is vital; review how program directors interpret overapplication style checks for mortgages to avoid unexpected roadblocks.
Now, a year or two later, you're eyeing your first investment property. Maybe it's a duplex in a transitioning neighborhood. Maybe it's a single-family rental in a growing suburb. You walk into a retail bank, confident in your six-figure attending salary, and get hit with a denial. Or worse, a laughably low pre-approval amount.
Why? Because that "great" physician loan is now a massive anchor on your debt-to-income (DTI) ratio.
When you finance 100% of a primary home, your monthly mortgage payment is inherently larger than if you had put 20% down. Lenders look at that high-balance, zero-down debt and immediately flag you as a risk when you ask for a second mortgage. They don't care that you're a doctor. They care about their secondary market guidelines. Managing your DTI when your first mortgage didn't require a traditional down payment is the exact bottleneck you need to solve. If you don't understand how underwriters view your existing physician loan, your real estate portfolio will stall before it even starts.
The following information is for educational purposes only and is not financial advice, not legal advice, and not tax advice. Real estate figures vary based on market conditions and individual circumstances, so always consult a qualified professional before making investment decisions.
The Core Obstacle: How Lenders Calculate Your DTI with a Physician Loan
Let's talk about the math. Retail lenders operate on strict Fannie Mae and Freddie Mac guidelines. They cap your total DTI, your housing debt plus all other monthly debts divided by your gross monthly income, around 45% to 50%.
Here is where the physician loan betrays you. Because you put zero down, your loan amount is the full purchase price. On a $600,000 home at a 7% interest rate, your principal and interest payment is roughly $3,990. Add in property taxes and homeowners insurance, and your total monthly housing debt easily crosses $4,800. If you gross $20,000 a month, that single primary residence eats up 24% of your gross income before we even look at your student loans, car payments, or the new investment property you want to buy.
Unconventional underwriting makes this worse. Physician loans waive PMI, which saves you money monthly, but the 100% financing means your base loan balance is maxed out. When you apply for an investment property, the lender has to underwrite both mortgages. They will count 100% of your primary physician mortgage payment against you.
I've seen attendings get flat-out denied by big-box banks because the underwriter couldn't offset the primary housing debt. The bank's algorithm just sees a borrower with two massive housing liabilities and a high loan-to-value (LTV) ratio on the primary home. They don't see a high-earning medical professional with immense job security. They just see a spreadsheet that doesn't balance.
Step-by-Step Playbook: How to Position Yourself for Approval
You can't change the math of your existing physician loan, but you can change how you present your financial profile. Here is the exact sequence you need to follow to get approved.
1. Respect the Seasoning Timeline If you closed on your primary physician loan six months ago, stop looking at Zillow. Wait. Most conservative underwriters want to see at least 12 to 24 months of timely mortgage payments on your primary residence. This "seasoning" period proves you can comfortably handle the jumbo-sized payment without defaulting. It also gives your primary home a chance to build equity, which lowers your overall risk profile. Patience here is non-negotiable.
2. Weaponize Projected Rental Income You can use the future income from your investment property to offset the new mortgage debt. Lenders typically allow you to use 75% of the gross scheduled rent from a signed lease agreement (or a market rent schedule from an appraiser) to qualify. If the new property's mortgage is $2,500 a month, but 75% of the projected rent is $2,600, the new property actually helps your DTI. However, this only offsets the new debt. Your primary physician loan liability remains fully counted against you unless you have a documented history of renting out a portion of your primary home.
3. Stack Your Liquid Reserves Retail banks get nervous when a borrower has two mortgages and thin bank accounts. You need to show massive cash buffers. I'm not just talking about the down payment for the investment property. You need to show 6 to 12 months of liquid reserves covering the principal, interest, taxes, and insurance (PITI) for both properties. If your primary PITI is $5,000 and your investment PITI is $2,500, you need to show $45,000 to $90,000 in liquid assets post-closing. Keep this cash in easily verifiable accounts. No crypto, no locked-up retirement funds.
Alternative Financing Routes If Traditional Investment Loans Say No
If you run the numbers and a conventional Fannie Mae loan is mathematically impossible, you pivot. You stop playing by retail bank rules and find lenders who actually understand the physician trajectory.
Portfolio Lenders and Physician-Niche Banks This is your best move. Portfolio lenders hold the loans on their own books rather than selling them to the secondary market. Because they keep the paper, they write their own underwriting guidelines. Physician-specific banking partners understand that a first-year attending making $250,000 is highly likely to be making $400,000 in three years. They will often allow higher DTI ratios, accept smaller reserve requirements, and look at your employment contract rather than just your past two years of tax returns.
HELOCs and Cash-Out Strategies If your primary home has appreciated rapidly, you might have enough equity to pull cash out via a Home Equity Line of Credit (HELOC) to buy the investment property in cash or put a massive down payment on it. Be careful here. Read your original physician loan promissory note. Some lenders restrict secondary financing or impose specific LTV caps that make piggyback lines tricky to secure. If your primary lender allows it, a HELOC can bypass the DTI issue entirely because you aren't taking on a new traditional mortgage for the investment property.
LLCs and Co-Signers I get asked about putting the investment property in an LLC all the time. Great for liability protection. Terrible for getting a cheap mortgage. If you put the property in an LLC, you are forced into commercial loan territory, which means higher interest rates, shorter amortization periods, and massive down payments. Keep the property in your personal name to get residential financing, then transfer it to an LLC later if your risk tolerance demands it. As for co-signers, adding a non-occupant co-borrower (like a parent) can help with DTI, but it complicates the title and tax situation. Avoid it unless absolutely necessary.
Action Steps: What to Do This Week
Stop guessing and start calculating. Here is your immediate homework:
- Pull your current credit report. Calculate your exact DTI. Include your physician loan minimum payment, your minimum student loan payment (even if it's on an income-driven repayment plan, lenders have specific rules for how they calculate this), and your car loans.
- Schedule a consultation. Do not walk into a local branch of a massive national bank. Find a mortgage broker who specifically handles physician real estate portfolios and has access to niche portfolio lenders.
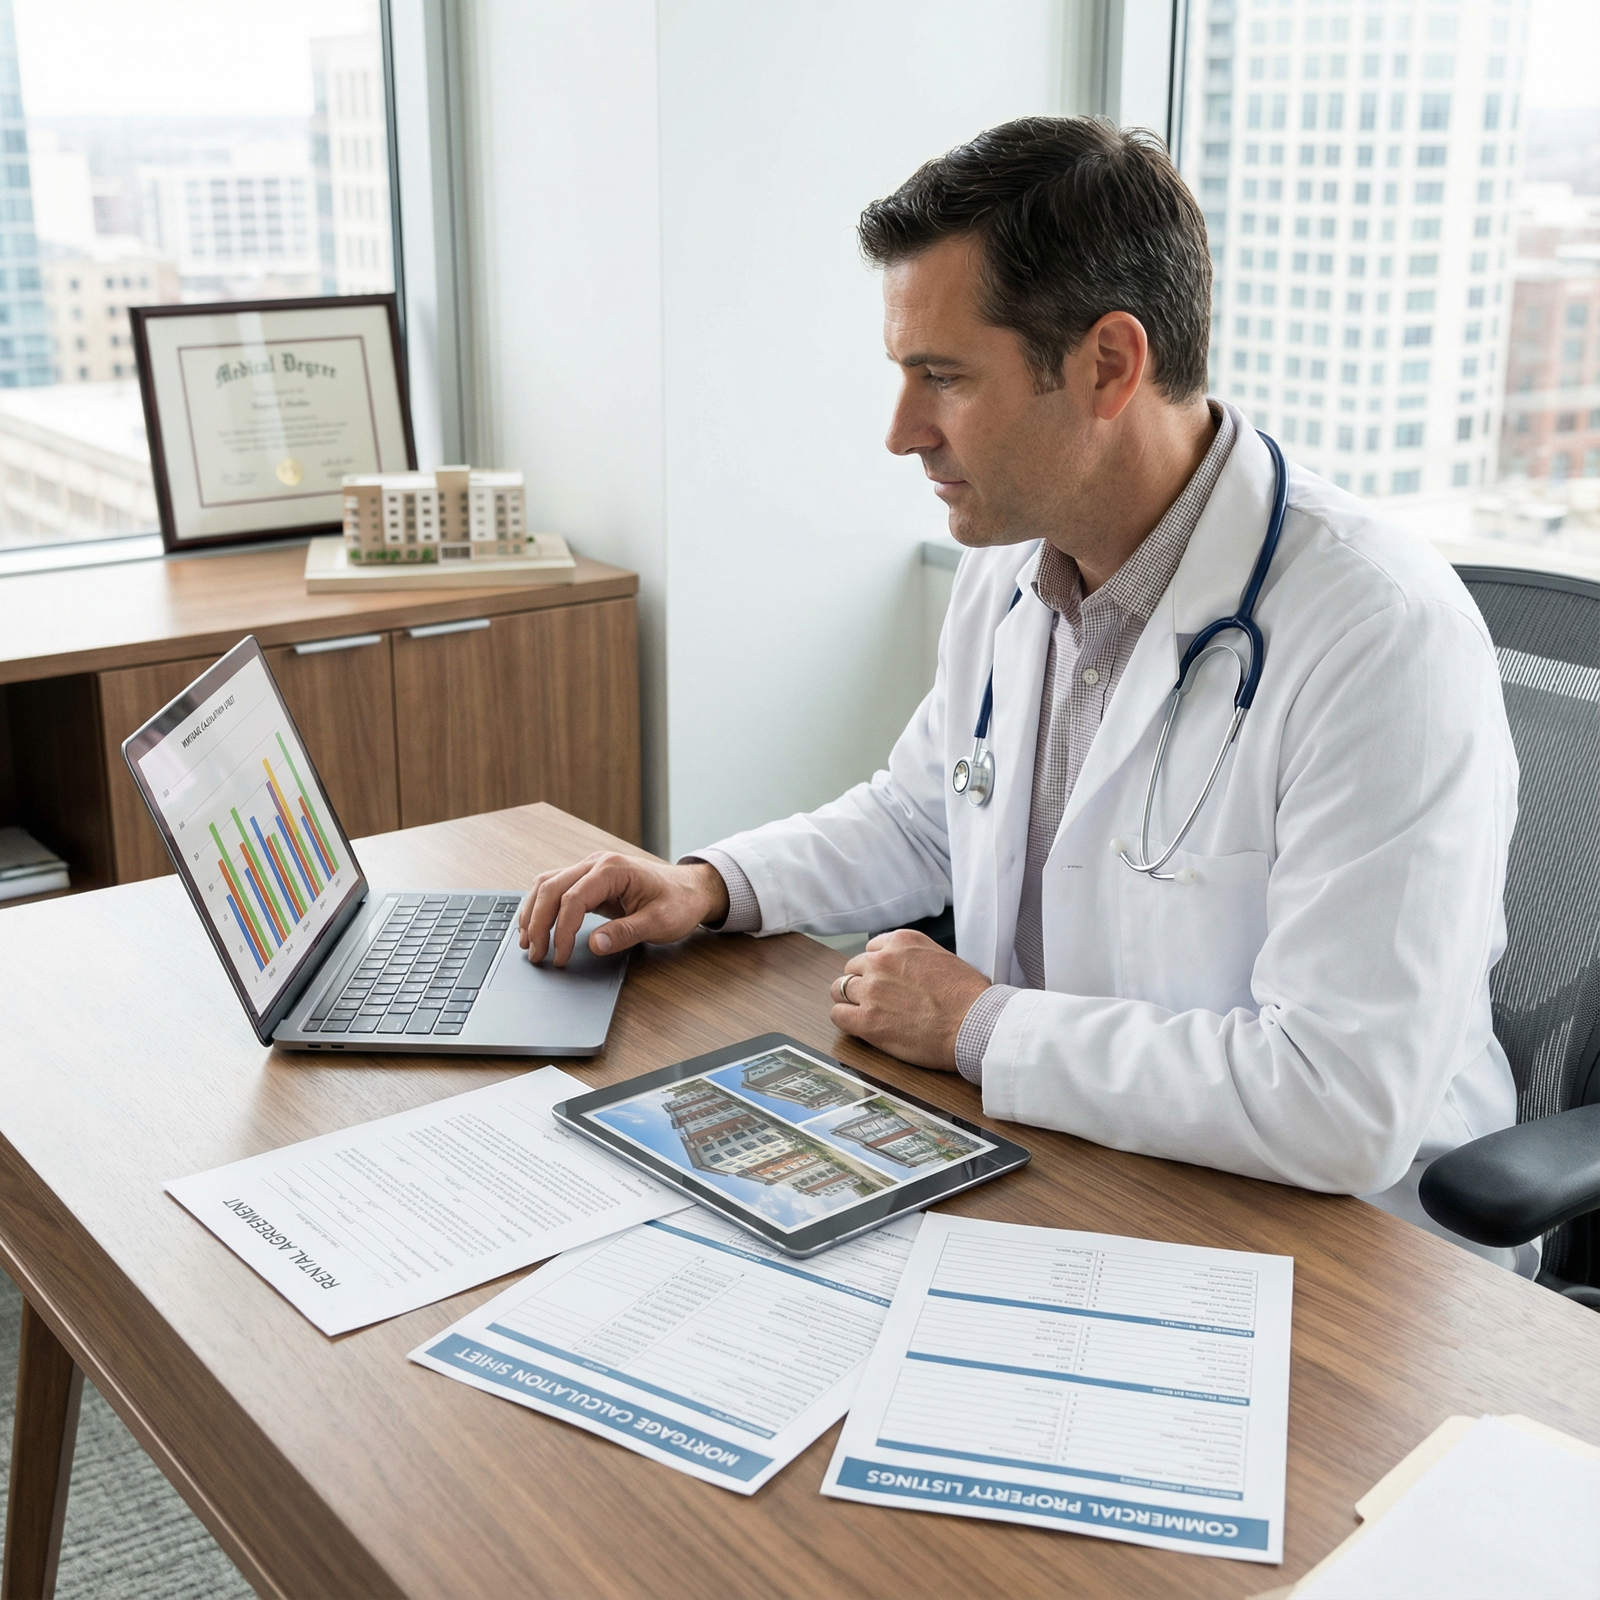
- Gather your documents. Pull your last two years of W2s, your most recent tax returns, and your last two pay stubs. If you are looking at a specific investment property, get the listing agent to pull comparable rental data so you can calculate the 75% gross rent offset. See where your numbers truly stand before you fall in love with a property.
Key Takeaways
- Holding a physician loan doesn't disqualify you from buying an investment property, but it heavily impacts your DTI ratio because of the 100% financing.
- Lenders will count 100% of your primary physician mortgage payment against you unless you can prove sufficient rental income offset or wait out the seasoning period.
- Working with physician-niche lenders and portfolio banks is often the only way to get creative investment loans approved compared to standard retail banks.