That $50,000 signing bonus sitting at the top of your job offer isn't a gift. It isn't a reward for surviving residency, and it sure as hell isn't "free money." It's an uncollateralized, high-risk loan masquerading as compensation. Hospital recruiters know you're broke. They know you've got six figures of student debt, credit card balances accrued during fellowship, and a bank account clinging to life. So they dangle a bright, shiny five-figure check to blind you to what's buried in section 14B of your employment contract.
I've reviewed hundreds of physician contracts, and I see the exact same disaster play out every single year. A fresh attending signs a contract, gets a $60,000 signing bonus, spends it immediately on a house down payment or high-interest loans, and then realizes nine months later that the practice environment is an unsalvageable wreck. When they try to resign, the hospital slaps them with a bill for $60,000, payable within 30 days, plus interest.
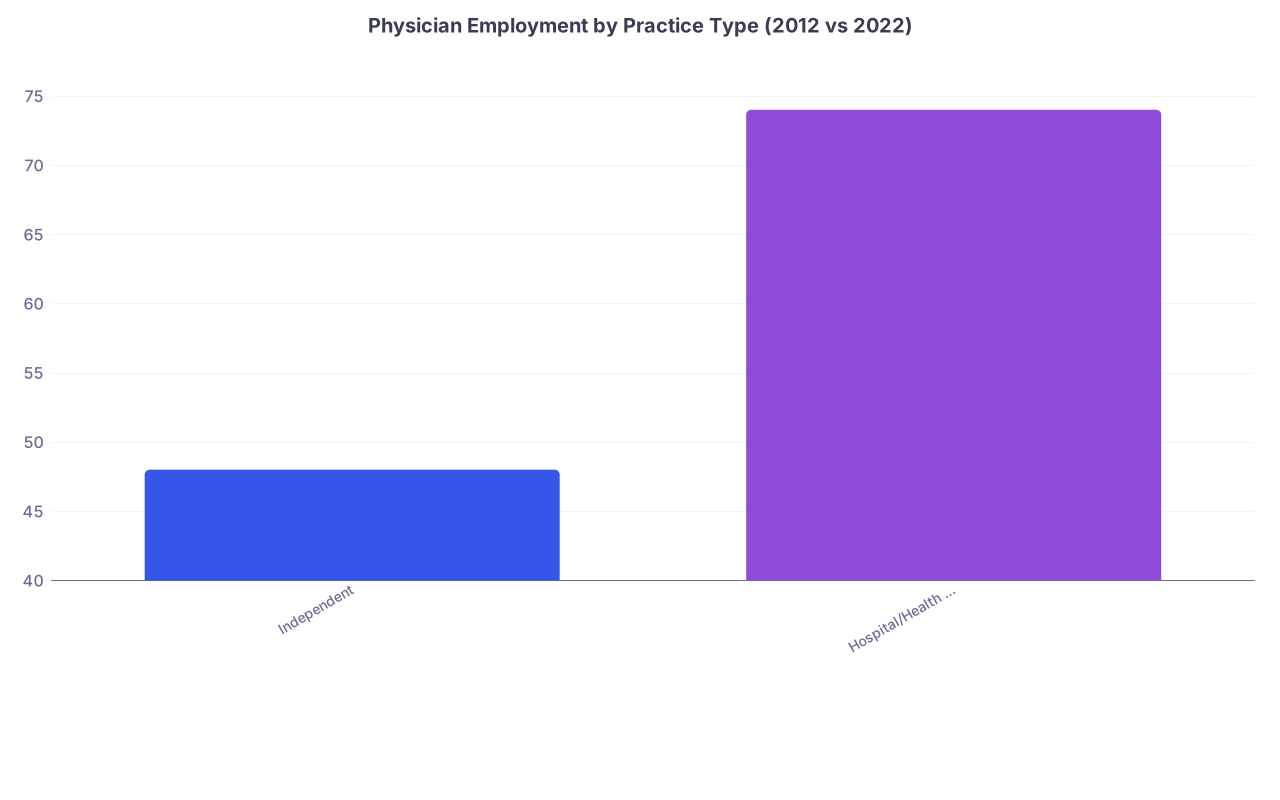
Why does this happen? Because young doctors confuse receiving cash with earning cash. The data on physician retention shows that up to 50% of doctors leave their first post-residency job within five years. If you leave early without understanding how your signing bonus is structured, you aren't just changing jobs, you're walking straight into a financial meat grinder.
Before you agree to any upfront financial incentives, it pays to review signing bonuses relocation loan repayment what's really negotiable to protect your long-term earnings.
This content is created for educational purposes only and is not financial advice, not legal advice, and not tax advice. Real-world figures vary based on practice type and location, so always consult a qualified professional before executing any employment contract.
The Core Challenge
Let's tear apart the mechanics of how this trap actually works. The core issue boils down to three words: taxes, cliffs, and gross repayment clauses.
First, the tax trap. Hospital HR hands you a $50,000 bonus. You check your bank account, expecting $50,000. Instead, you see $32,500. Why? Supplemental wage withholding. Federal tax, state tax, FICA, Medicare, the IRS takes its bite upfront. You spend that $32,500 on moving costs, furnishings, or student loans.
Now, imagine the job turns out to be an absolute nightmare. The call schedule is doubled without warning, or the production metrics are mathematically impossible. You give your notice at month ten.
Here is where the trap springs: almost every standard contract requires you to repay the gross amount of the bonus, not the net amount you actually received. You got $32,500 in your bank account, but you legally owe the health system $50,000 cash. Today. Right now. You are personally on the hook for the $17,500 that you never even touched because it went straight to the IRS.
Second, look at the forgiveness schedule. Conventional wisdom says "as long as I work there, it forgives." Nonsense. How it forgives makes all the difference in the world.
There are two main forgiveness structures in modern physician contracts:
- Monthly Pro-Rata Forgiveness: Every month you work, 1/24th or 1/36th of the bonus is forgiven. If you leave at month 12 of a 24-month contract, you owe 50% back.
- Annual Cliff Forgiveness: Nothing forgives until you hit the 365th day. If you leave at day 364, you owe 100% back.
Hospitals love annual cliffs because it turns the bonus into golden handcuffs. They hold all the leverage. If conditions at the clinic degrade to an intolerable degree at month 11, you can't walk away without handing back every single dollar.
Third, look at termination clauses. Does the clawback trigger if they fire you without cause? If the hospital restructures, closes your clinic, or terminates your contract "for convenience" with 90 days' notice, do you still owe the money? In poorly drafted contracts, the answer is yes. You get laid off through no fault of your own, and you get hit with a five-figure bill on your way out the door. That isn't compensation. That's extortion.
Actionable Next Steps
You don't have to reject signing bonuses. You just need to neutralize the debt trap before you sign on the dotted line. Here is the exact strategy I advise doctors to execute.
Step 1: Execute the "Lockbox Strategy"
When the bonus lands in your checking account, pretend it isn't yours. Because until the forgiveness clock runs out, it isn't.
- Open a completely separate High-Yield Savings Account (HYSA).
- Deposit the net bonus cash into that account immediately.
- Do not touch it. Do not buy a luxury car. Do not put a down payment on a home you can't otherwise afford.
- Let it sit and collect interest. If you stay the full term, you keep the bonus plus the interest. If you need to leave early, the funds are completely intact, sitting right there to pay off the debt.
Step 2: Redline the Contract
Never accept the default language hospital legal teams dump into draft contracts. Have your health law attorney push back on these three specific items:
- Convert Cliffs to Pro-Rata: Strike out any annual or multi-year cliff. Insist on monthly pro-rata earning and forgiveness.
- Eliminate Clawback on Without-Cause Termination: Ensure the repayment obligation vanishes entirely if the employer terminates you without cause, or if you terminate for cause due to employer breach.
- Net Repayment Provision: Negotiate a clause stating that if repayment is required, you are only obligated to repay the net post-tax cash received, leaving the employer to recoup tax withholdings directly from the IRS or through payroll tax adjustments.
Step 3: Understand Tax Recovery Options
If you do end up paying back a bonus in a subsequent tax year, do not eat the lost tax money. The IRS provides a specific mechanism under Section 1341 (Claim of Right). It allows you to claim a tax credit or deduction for repaid income that was taxed in a prior tax year. Hospital HR won't tell you about this, but a competent CPA can save you thousands of dollars if you know to ask.
Step 4: Convert Bonuses to Base Salary
If an employer refuses to modify a rigid, high-risk clawback clause, pivot. Ask to convert that $30,000 upfront bonus into a higher base salary or an unconditional retention bonus paid at the end of each completed contract year. An extra salary bump compounds over time and carries zero clawback risk.
Key Takeaways
- Be prepared for the worst-case scenario: Treat your signing bonus as an uncollateralized loan until the contractual forgiveness period expires. Park the net payout in an untouchable high-yield account until you've cleared the obligation.
- Focus on high-yield areas during contract negotiation: Eliminate annual cliff forgiveness in favor of monthly pro-rata schedules, and ensure clawbacks are completely voided if you are terminated without cause.
- Protect your tax cash flow: Never write a repayment check for a gross bonus without consulting a CPA to use IRC Section 1341 for tax recovery on the withheld funds.