It was 11:47 p.m. on a Tuesday when the email landed: Your payment of $487 is due in 10 days. My Step 3 date was six weeks out. My UWorld percentage was... let's call it "humbling." I was on nights, running on vending machine pretzels, and suddenly I'm doing panic math in my head, exam fee, rent, question bank renewal, groceries, and now this.
You've had this moment. Maybe you're having it right now. The thought creeps in: What if I just... paused the loans? Just for a few months. Just until boards are done. And then the second thought, the scarier one: What if pausing them wrecks everything, my credit, my forgiveness timeline, my entire financial future?
So I went looking for what the data actually says. Not forum rumors. Not what someone's co-intern heard from a financial advisor's cousin. The real mechanics. Here's the short version: pausing loans is neither the genius hack some people claim nor the catastrophe your anxiety is predicting. It's a tool with a price tag, and the price depends on details most of us never read. Let's read them.
A quick pause before we talk about pausing: everything in this article is for educational purposes only, not financial advice, not legal advice, and not tax advice. Loan terms, servicer policies, and interest rules shift constantly, and figures vary depending on your specific loans. Before you change anything about your repayment, consult a qualified professional who can look at your actual situation.
What "Pausing Loans" Actually Means
Here's the first thing that tripped me up: "pause" isn't one button. It's like four different buttons wearing a trench coat, and pressing the wrong one costs real money.
Deferment is the better-behaved sibling. You qualify based on circumstances, being in school, in residency in some cases, economic hardship, and depending on your loan type, the government may cover interest on subsidized portions while payments are paused.
Forbearance is the one servicers love to hand out like free samples. Payments stop. Interest does not. It accrues on everything, subsidized or not, and if you're not careful it capitalizes, meaning it gets folded into your principal, and now you're paying interest on your interest. That's the part that should make your eye twitch.
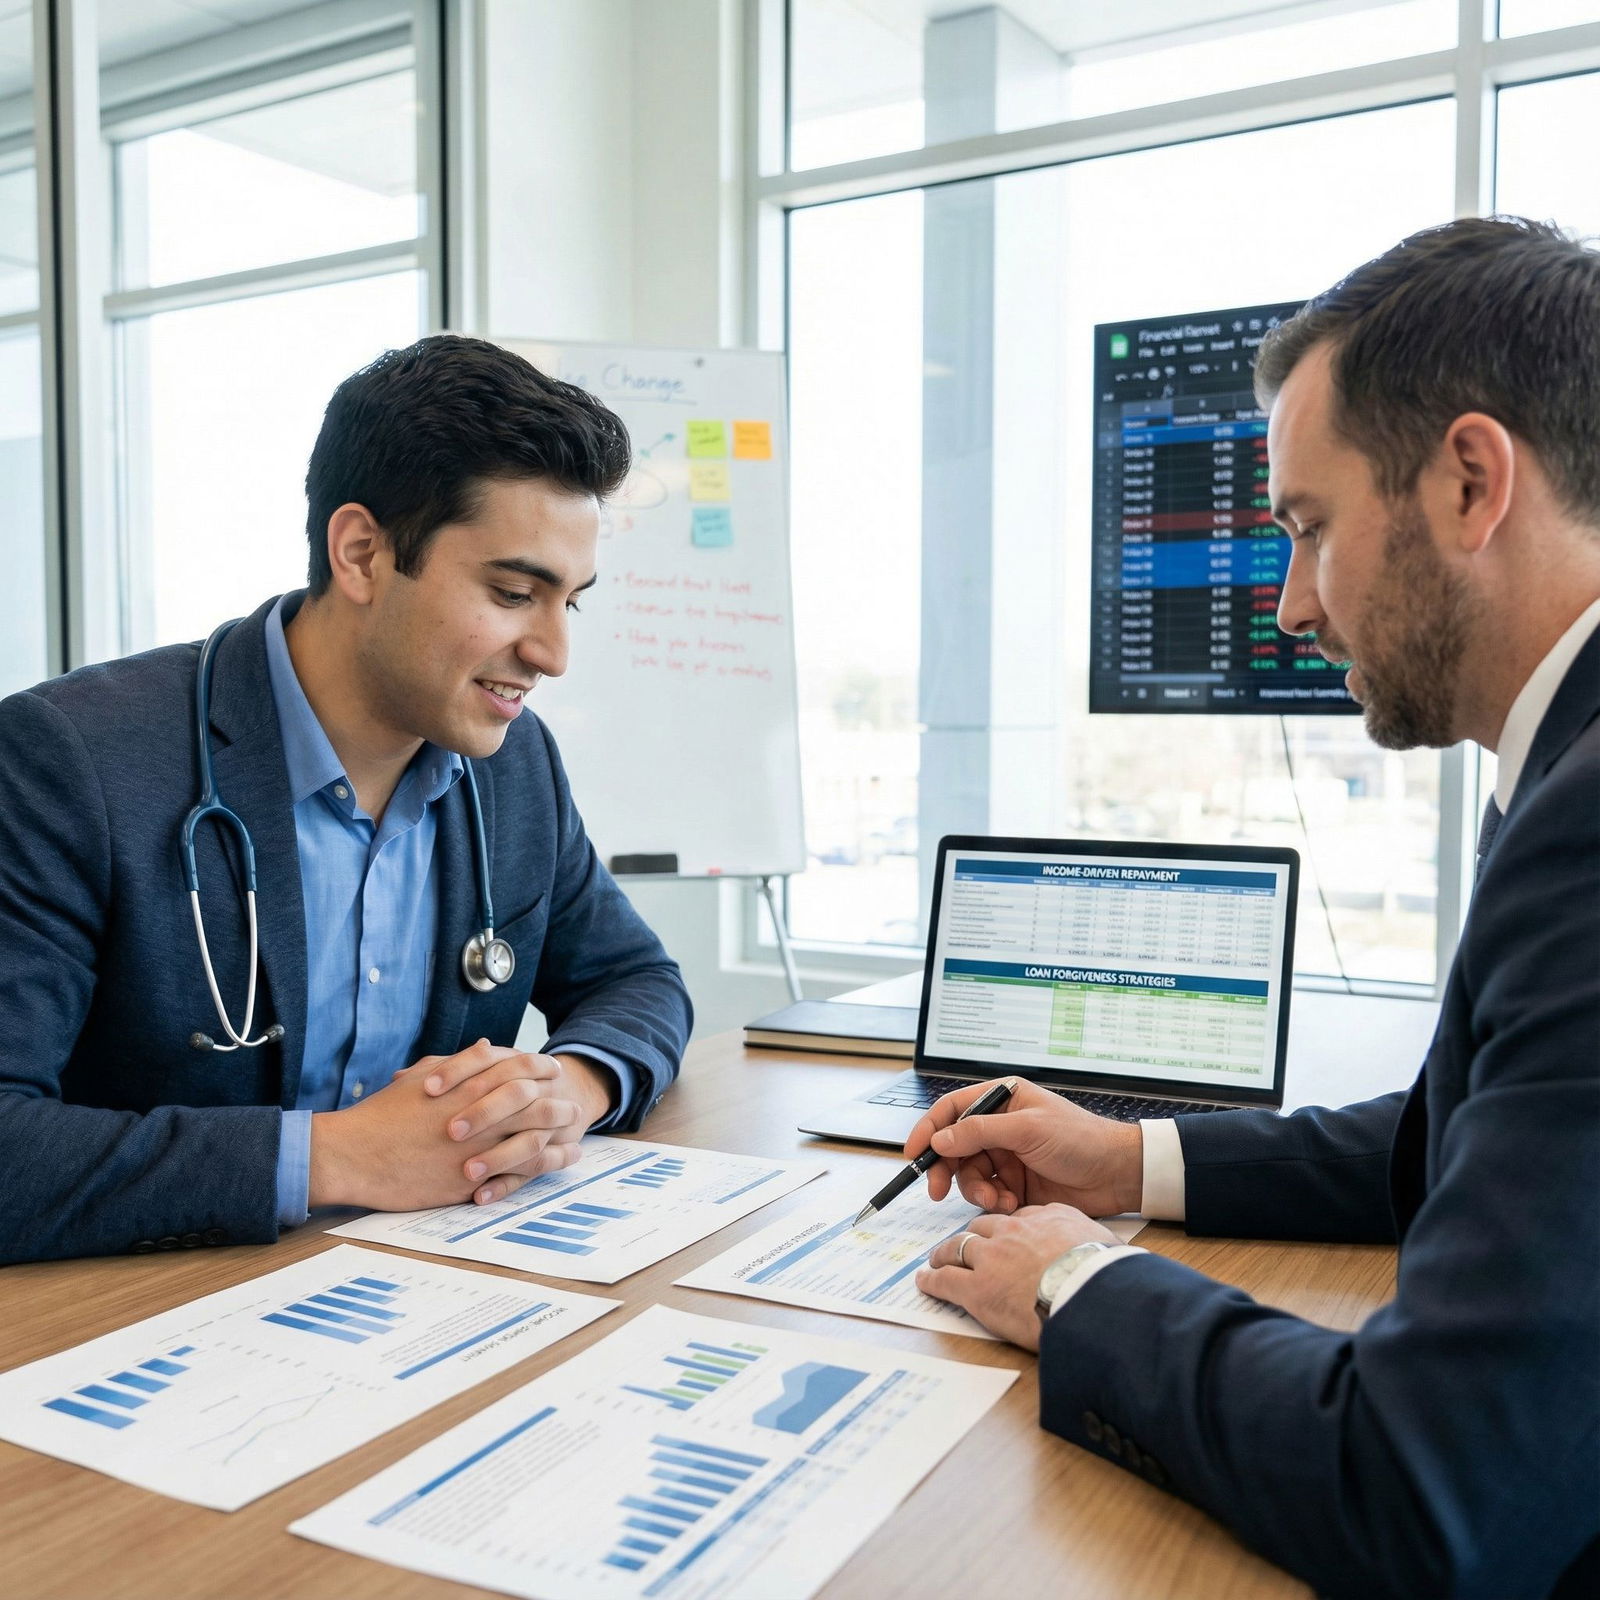
Income-driven repayment adjustments aren't technically a pause, but recertifying your income can drop your payment to nearly nothing, sometimes literally $0, while still counting as a real payment toward forgiveness programs. For residents, this is frequently the smartest option on the menu, and it's the one servicers mention last.
Servicer hardship pauses on private loans are the Wild West. Terms vary by lender, by loan, by mood of the underwriting department. Get everything in writing.
And the thing nobody tells you clearly enough: pausing is not canceling. The balance doesn't freeze like a paused movie. Think of it like a taxi stopped at a red light, the car isn't moving, but the meter is still running.
What the Data Says About Cash Flow, Interest, and Repayment Costs
Let me give the devil its due first: the short-term relief is real. Freeing up $300-$500 a month for three months during boards season can cover the exam fee (which is north of $900 for Step 3, because of course it is), a prep course, childcare during study blocks, or just the ability to stop doing panic math at midnight. During away rotations or an unpaid gap between graduation and your first residency paycheck, that breathing room isn't a luxury. It's survival.
Now the tradeoff, because there's always a tradeoff. Interest on most graduate-level loans doesn't care about your exam schedule. On a $180,000 balance, pretty typical for a new MD, the interest meter runs somewhere between roughly $975 and $1,400 a month depending on your rate. Pause for three months, and you could owe $3,000-$4,000+ more than when you started. If that interest capitalizes, it becomes part of your principal. Your future self pays interest on it for years.
The variables that actually matter, ranked:
- Loan type. Federal subsidized portions may be sheltered in deferment. Unsubsidized, Grad PLUS, and private loans are not.
- Interest rate. A pause on a 5% loan stings. A pause on a 9% private loan is a wound.
- Pause length. Three months is a rounding error over a 10-year repayment. Twelve months is a decision.
- Capitalization. The single most expensive word in this entire article.
Now, the worst-case fear, because I know you're carrying it: Will a pause ruin my repayment? No. Thousands of residents use forbearance every year and survive. The pause itself is rarely the disaster. The disaster is ignoring the terms, not knowing your restart date, not knowing interest capitalized, letting a three-month breather quietly become a two-year drift. The pause doesn't ruin people. The autopilot does.
How Pausing Loans May Affect Credit, Stress, and Exam Performance
Credit first, because this fear is wildly overblown. A properly arranged deferment or forbearance is not a missed payment. It generally doesn't report as delinquency. Your score doesn't crater because you filled out the right form.
What craters your score is thinking you're paused when you're not. I watched a co-resident do this. He requested forbearance, assumed it was approved, never got the confirmation, and stopped paying. Sixty days later: delinquency on his credit report, right before he applied for an apartment. The servicer's response was essentially a shrug. So: approved means confirmed in writing, not "the phone rep sounded positive."
Now the stress side, which honestly matters more to me. Financial scarcity eats cognitive bandwidth, there's actual research on this, and every anxious applicant already knows it in their bones. When part of your brain is running a background process called Can I afford rent AND this exam fee?, that's working memory you're not spending on cardiology questions. Reducing that monthly pressure can genuinely improve your sleep, your focus, and your practice scores. I've felt the difference. It's not small.
But, and this is the honest part, the relief only holds if you understand the terms. If you pause your loans but don't know when repayment restarts or how much interest piled up, you haven't removed the anxiety. You've just deferred it. With interest. Pun fully intended, because that's literally what's happening.
When Pausing Makes Sense vs. When It Could Backfire
After obsessing over this for weeks, here's my honest read.
A pause is probably reasonable when:
- You have a genuine temporary income gap, the dead zone between graduation and your first residency paycheck is the classic example.
- Exam month is colliding with a real cash crunch, and the choice is "pause loans" or "put the exam fee on a credit card at 24%." (Pause the loans. That's not even close.)
- You're in a job transition with a defined end date.
- An actual emergency hit, car repair, family crisis, not "I want a nicer apartment."
Caution flags, and I mean bright red ones:
- High-interest private loans. Every paused month at 9%+ is expensive.
- A capitalization event lurking at the end of the pause.
- You're pursuing PSLF. Forbearance months usually don't count toward your 120 qualifying payments. That's not a pause, that's a detour.
- You have no restart plan. "I'll figure it out after boards" is how three months becomes three years.
And here's the opinion I'll defend: for most residents, forbearance is overrated, and income-driven recertification is underused. Servicers push forbearance because it takes them thirty seconds to process, while an IDR application takes actual paperwork. Their convenience is not your strategy. A $0 IDR payment during a low-income year often beats forbearance on every axis, interest handling, forgiveness credit, all of it. Ask about it specifically. Make them say the words.
Practical Steps Before You Hit Pause
If you're going to do this, do it like a paranoid person. I say that with love, as a paranoid person.
- Log in and identify every loan. Type, balance, rate, servicer. All of them. Yes, even the one you've been avoiding.
- Ask for options in order: deferment first, IDR recertification second, forbearance last. Say the words "income-driven" out loud on the call.
- Ask the magic question: Will unpaid interest capitalize at the end of this pause, and when? Get the answer in writing.
- Document everything. Confirmation numbers, dates, the name of the rep, screenshots of the portal showing your new status. Build a little paper trail like you're preparing for an audit.
- Write the restart date on your calendar. Next to your exam date. Both dates should stare back at you.
- Make a mini plan for the pause months. Exam budget, small savings target, and, if you can swing it, throw even $100 a month at the accruing interest so it never capitalizes. Future you will be annoyingly grateful.
Here's what I landed on after all the spiraling: the loan will still be there after your exam. So will you. A pause isn't weakness and it isn't a trap, it's a line item with a knowable cost. Know the cost, write down the restart date, and walk into that testing center with your whole brain pointed at the questions that actually matter this month.
Key takeaways:
- Pausing can genuinely relieve short-term pressure during Step 3 and board prep, but the true cost depends on your interest rate, loan type, and the pause's fine print.
- A pause isn't automatically harmful, but ignoring capitalization and restart dates is how balances grow faster than your anxiety predicted.
- The safest choice is the one you fully understand, document obsessively, and pair with a restart plan, so today's relief doesn't become tomorrow's 2 a.m. panic.