The day you retire is not the day you stop being an investor. It's the day your portfolio starts doing the heavy lifting.
Let me get the boring stuff out of the way first: this article is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Figures vary depending on your situation. Consult a qualified professional before making portfolio decisions.
If you are concerned about your portfolio sustainability, check out why high-earning physicians often have less secure retirements and how to protect yourself.
If you are worried about your longevity, consider reading why many doctors misjudge how much they actually need to retire to align your expectations.
The Dangerous Myth of the "Retirement Cliff"
Here's one of the most expensive misunderstandings in personal finance: the idea that retirement is a cliff edge. You're 64, you're an aggressive investor with 70% in stocks. You turn 65, you retire, and, supposedly, you need to yank everything into cash and bonds overnight.
That's wrong. Dangerously wrong.
I've watched people do this. They panic at their retirement party, move $1.2 million into a money market fund, and congratulate themselves on being "safe." Ten years later, their portfolio has been quietly ravaged by inflation. They're withdrawing from a shrinking pile, and the math is starting to hurt.
The problem is two-fold. First, there's sequence-of-returns risk. This is the killer that most pre-retirees don't understand. If the market crashes in the first two years of your retirement, while you're actively withdrawing money, your portfolio may never recover. Not because the market didn't come back, but because you were selling shares at depressed prices to fund your life. You sold low, and you'll never get those shares back.
But here's the twist: the solution to sequence-of-returns risk isn't to dump all your stocks. It's to have a cash buffer so you don't have to sell stocks during a downturn. The rest of your portfolio stays invested and continues growing.
The second problem is inflation. If you're 65 and healthy, your retirement isn't 5 years. It's not 10 years. Statistically, at least one member of a 65-year-old couple has a 50/50 chance of living past 90. That's a 25-year retirement horizon, minimum. Some of you are looking at 30 years.
Cash and short-term bonds won't beat inflation over that period. They can't. Historically, equities are the only asset class that reliably outruns inflation over multi-decade periods. If you dump your stocks at 65, you're trading market volatility for the certainty of losing purchasing power every single year.
Before finalizing your strategy, consider reviewing why many doctors misjudge how much they actually need to retire to ensure your goals are realistic.
That's not safety. That's a slow bleed.
Understanding Your Time Horizon: You Aren't Investing for "Retirement Day"
Beyond allocation, understanding common lifestyle inflation traps that destroy physician retirement can ensure your cash flow remains sustainable.
If you are concerned about your portfolio trajectory, learning how historical market data means for physician retirement timelines can offer valuable perspective on your long-term plan.
You're not investing for the day you retire. You're investing for the 30 years after that day.
This is the mental shift that changes everything. Retirement isn't a single event, it's a multi-decade withdrawal phase. The money you need in year 1 of retirement is different from the money you need in year 25. Your portfolio should reflect that.
For those still in the early stages of their careers, avoiding 7 retirement planning mistakes physicians make in their first 5 years can help prevent long-term complications.
The Bucket Strategy: Volatility Management Without Panic
Here's how I've seen this work in practice. You divide your portfolio into three buckets:
Bucket 1: Cash and liquid assets (0-3 years of expenses). This is your war chest. Money market funds, high-yield savings, short-term CDs. This bucket funds your life. When the market drops 30%, you don't care, you're not selling stocks. You're spending cash.
Bucket 2: Bonds and fixed income (3-7 years of expenses). Intermediate-term bonds, Treasury notes, maybe some stable value funds. This is your volatility buffer. It generates interest and gives you a predictable source of funds to refill Bucket 1 when needed.
Many physicians also find that the best way to maintain peace of mind is to work with a professional, especially when weighing if they need a financial advisor to retire comfortably.
Bucket 3: Stocks and growth assets (7+ years of expenses). This is the engine. Broad equity index funds, maybe some international exposure, perhaps a slice of real estate or other growth assets. You don't touch this bucket unless you're rebalancing or the other buckets need replenishing after a sustained market recovery.
The beauty of this approach is psychological as much as mathematical. When the market tanks, you look at Bucket 1 and feel fine. You're not forced to sell anything at a loss. The stocks in Bucket 3 have years to recover.
The Math: Why You Need Growth
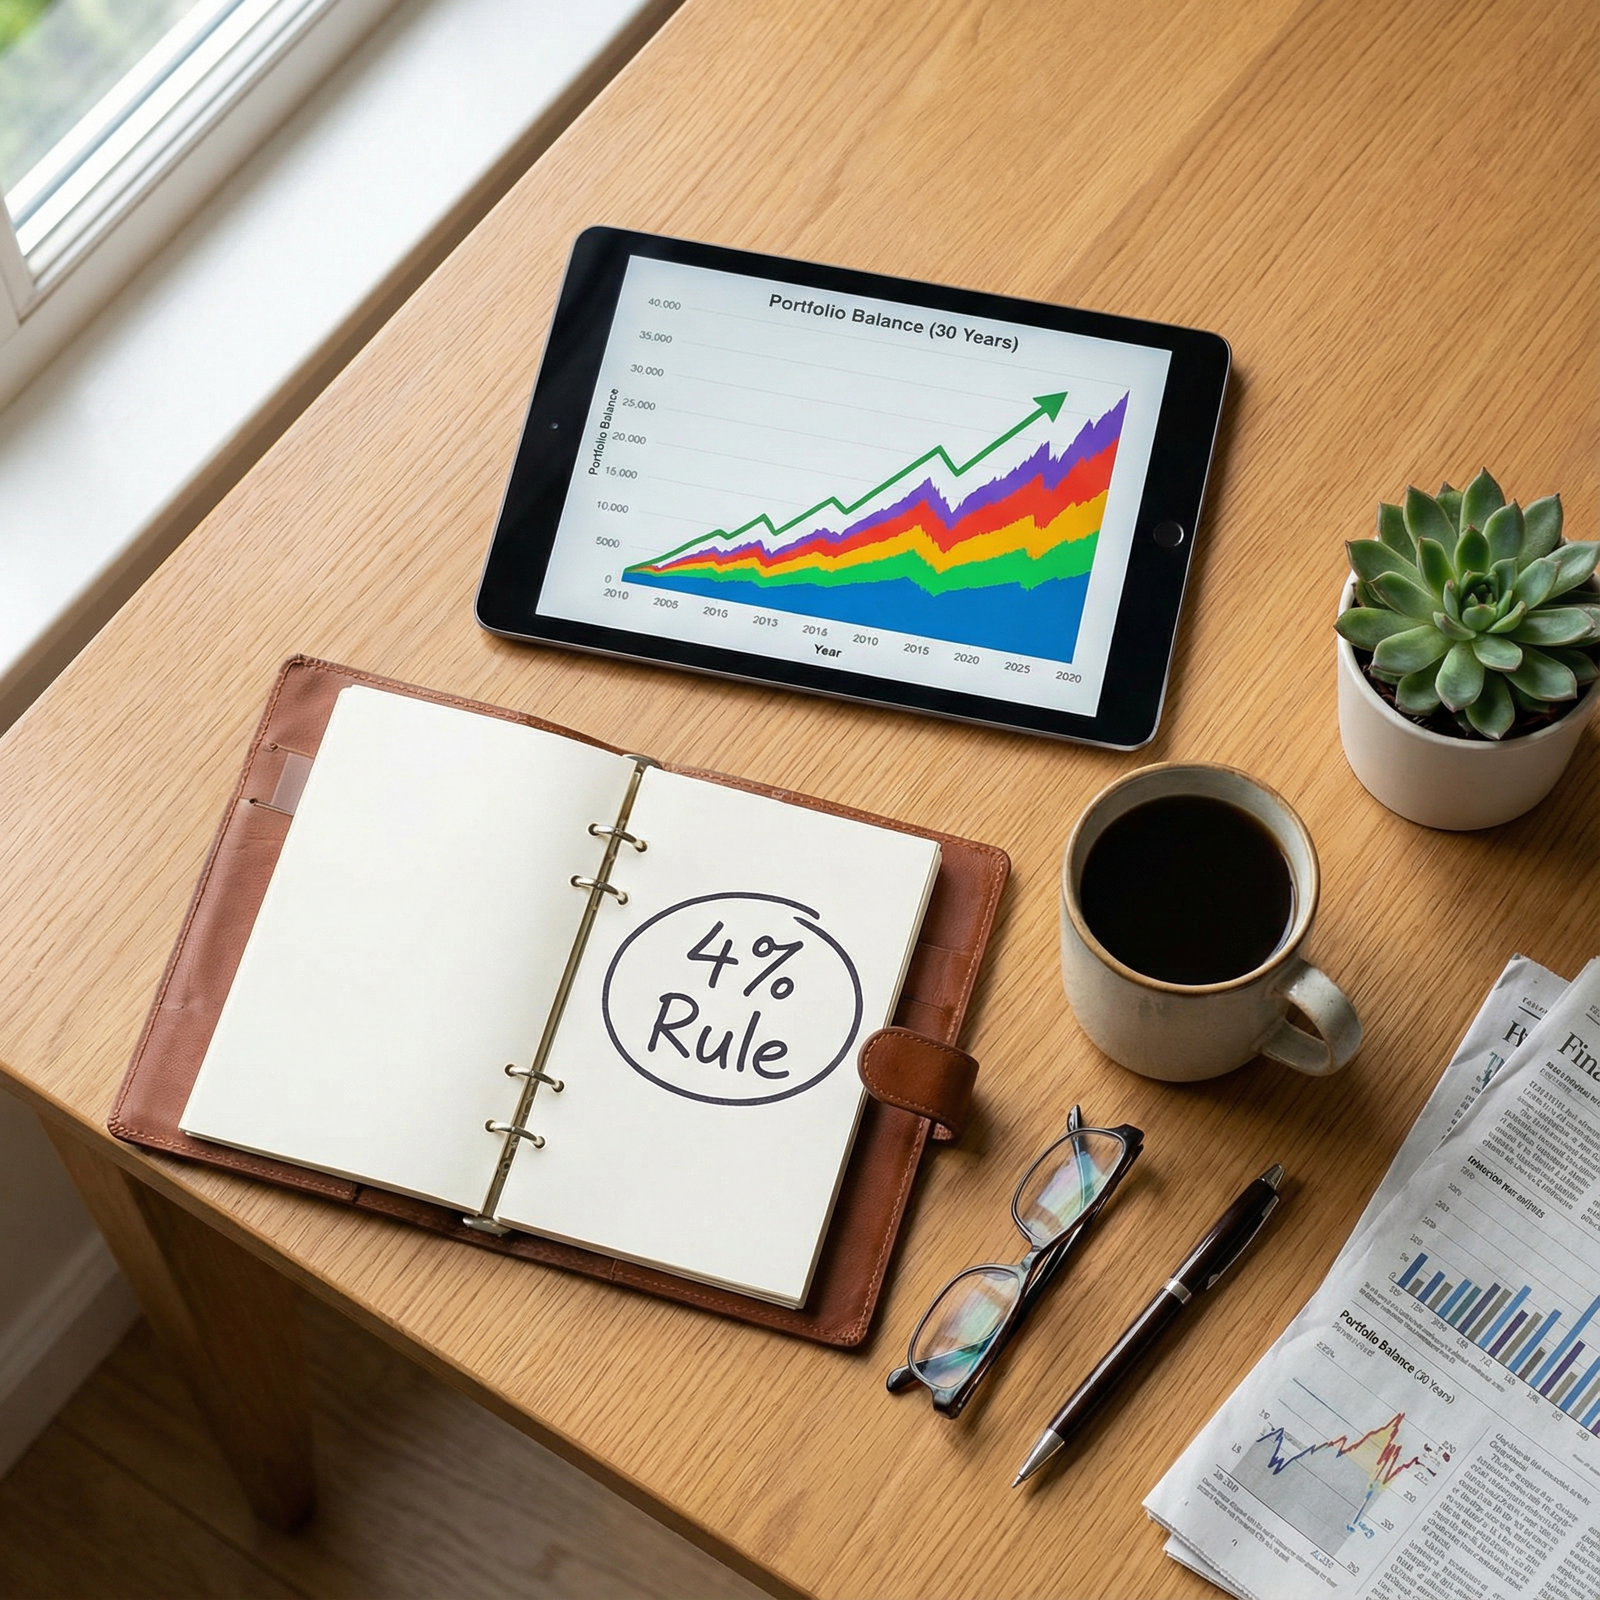
Here's a uncomfortable number. If you're withdrawing 4% of your portfolio annually and inflation averages 3%, your nominal withdrawals will nearly double by year 20 of retirement. Your year-1 withdrawal of $40,000 becomes $72,000 by year 20 just to maintain the same purchasing power.
A portfolio that doesn't grow can't keep up with that. If you've dumped everything into bonds returning 3-4% nominal, you're barely treading water before withdrawals. After inflation and withdrawals, you're sinking.
You need growth. Not aggressive, speculative growth, just steady equity exposure that compounds over decades. That's what makes a 30-year retirement financially viable.
Quantitative Comparison: Stock Allocation vs. Cash/Bond Heavy Portfolios
Let me show you the numbers, because this is where the argument gets won.
Real-World Portfolio Comparison
I've looked at historical data going back to 1970, running Monte Carlo simulations on different portfolio allocations with a 4% withdrawal rate over 30 years. Here's what happens:
100% Fixed Income (Cash/Bonds):
- Average annual return: ~4.5% nominal
- Inflation-adjusted return: ~1.5%
- After 4% withdrawals, you're withdrawing more than your real return
- Portfolio survival rate over 30 years: approximately 45-55%
- Translation: you run out of money more than half the time
60/40 Portfolio (60% stocks, 40% bonds):
- Average annual return: ~8% nominal
- More volatility, but manageable
- Portfolio survival rate: approximately 85%
- This is the classic balanced approach, and it works for most people
80/20 Portfolio (80% stocks, 20% bonds):
- Average annual return: ~9.5% nominal
- More volatility in the short term
- Portfolio survival rate: approximately 92%
- Higher long-term success because growth outpaces withdrawals and inflation
The 100% fixed income portfolio isn't "safe." It's the riskiest option for a 30-year retirement. You're trading visible volatility (market crashes) for invisible risk (inflation eating your purchasing power). One you see on the news and panic about. The other you don't notice until it's too late.
The Inflation Tax Nobody Talks About
Here's what kills conservative portfolios. Not market crashes, inflation.
If inflation averages 3% annually, prices double every 24 years. Over a 30-year retirement, the cost of living more than doubles. Your $50,000 annual expenses become $121,000 by year 30.
A portfolio sitting in cash and bonds can't generate the returns needed to handle that. You're locked into returns that barely match inflation before withdrawals. After withdrawals, you're losing ground every year.
Stocks, for all their volatility, have historically returned 7-10% annualized over long periods. That's 4-7% real return after inflation. That's the cushion that keeps your portfolio alive for three decades.
Historical Success Rates Tell the Story
The data is clear. Portfolio success rates correlate with equity exposure for long retirements:
- 4% withdrawal rate, 30 years, 80/20 portfolio: ~92% success
- 4% withdrawal rate, 30 years, 60/40 portfolio: ~85% success
- 4% withdrawal rate, 30 years, 100% bonds: ~50% success
Even at a 5% withdrawal rate, the equity-heavy portfolios outperform conservative ones. The math doesn't lie, growth is survival for long retirements.
Practical Decision Framework for Adjusting Your Portfolio
Risk Tolerance: Beyond Age-Based Rules
The "100 minus your age" rule is garbage. It tells a 65-year-old to hold 35% stocks. For a 30-year retirement, that's almost certainly too conservative.
Your risk tolerance isn't just about age. It's about three things:
- Your time horizon, when do you actually need each dollar?
- Your withdrawal rate, are you pulling 3% or 6% annually?
- Your psychological capacity, can you sleep at night with market volatility?
The first two are mathematical. The third is emotional. But here's the truth: you can manage the emotional piece with a proper cash buffer. If you have 3 years of expenses in cash, market volatility stops being existential and becomes abstract.
Living Off Dividends and Interest
Here's a strategy that works: don't sell unless you have to.
Many quality dividend stocks and bond funds generate enough income to cover part of your living expenses. If your portfolio yields 2.5% and you need 4%, you're only selling 1.5% of your portfolio annually. That's manageable even during downturns.
Rebalancing handles the rest. When stocks outperform bonds, sell some stocks to rebalance, and that sale funds your living expenses. When bonds outperform (usually during stock downturns), you're selling bonds instead of stocks. This is natural dollar-cost averaging in reverse.
Annual Portfolio Health Check
Run this checklist once a year:
- Verify your cash bucket still covers 2-3 years of expenses after withdrawals
- Rebalance if your allocation has drifted more than 5% from targets
- Review your withdrawal rate, are you still within 4% of current portfolio value?
- Check inflation impact, have your expenses increased? Adjust your cash bucket accordingly
- Tax-loss harvest if opportunities exist in taxable accounts
- Review Social Security timing if you haven't claimed yet
- Assess whether to trim equities only if your portfolio has grown significantly beyond needs
That's it. No panic. No cliff-edge transitions. Just steady, rational adjustments.
Key Takeaways
- Retirement is a 30-year process, not a destination. Your money still needs to work for you for decades after your last paycheck.
- Equities are your primary hedge against inflation. Selling them prematurely forces you to trade market volatility for the certainty of losing purchasing power.
- Use a bucket strategy to ensure liquid cash for immediate needs while letting the rest of your portfolio stay invested for long-term growth.
- A 100% bond portfolio isn't "safe", it's the riskiest choice for a long retirement, with failure rates exceeding 50% historically.
- Don't sell stocks unless you need to. Dividends, interest, and rebalancing can fund most of your retirement without forced selling.