A few months after leaving her first attending job, an internist I know got an ugly surprise. She'd moved cities, started fresh, and thought the old job was behind her. Then came the call: the old malpractice policy was claims-made, her employment had ended, and no one had bought tail coverage. Suddenly she wasn't asking, "Am I protected?" She was asking, "Why am I the one paying for this now?"
That mistake is painfully common. People hear, "We provide malpractice insurance," and stop reading. Bad move. The dangerous part isn't whether insurance exists during the job. It's what happens after you leave.
Educational disclaimer: This article is for education only and isn't legal, financial, tax, insurance, or employment-contract advice. Contract terms, insurer rules, malpractice exposure, and state law vary widely, so review your situation with a qualified healthcare attorney, malpractice broker, or other appropriate professional before you sign, resign, or rely on any coverage decision.
With malpractice coverage, the key distinction is simple:
- Occurrence policy: covers incidents that happened during the policy period, even if the claim is filed years later.
- Claims-made policy: usually covers claims only if the policy is active both when the care occurred and when the claim is reported.
That second type is where trouble starts. If you leave a job with a claims-made policy, there may be a gap between your past care and future claims. That gap is what tail coverage is meant to close. In plain language, tail coverage is extended reporting protection for care you already provided while the old policy was active.
Miss this, and you can get cornered into a large bill at exactly the wrong time: right after changing jobs, relocating, buying a house, or paying down loans. I've seen physicians assume HR handled it. I've seen group leaders say, "Don't worry, we cover malpractice," as if that answered the real question. It doesn't.
Read the actual policy terms and the contract language. Not the recruiting summary. Not the verbal reassurance. The paper.
This article is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Figures vary by individual circumstances, consult a qualified professional before acting.
The mistake people make: assuming tail coverage is automatic
Here's the blunt truth: tail coverage is not a default gift. It is a contract issue, and if you don't pin it down, you may own the problem later.
The most dangerous assumption sounds harmless: "My employer provides malpractice insurance, so I'm covered." No. You may be covered while employed and exposed the minute you leave. That's the trap.
Claims-made coverage is common because it often costs less up front than occurrence coverage. Employers like that. Practices like that. But lower up-front premium does not mean lower total risk to you. It can simply mean the cost shows up later, after separation, when your leverage is gone. Classic bait-and-delay economics.
Don't make these rookie mistakes:
- Confusing active coverage with permanent protection
- Relying on HR summaries instead of the full contract
- Assuming tail is included because no one mentioned it
- Waiting until resignation to ask who pays
Tail coverage matters because malpractice claims don't arrive on your schedule. A patient encounter from two years ago can turn into a claim long after you've left. Without tail, that old claim may not be reported under an active policy. Then what? You're left scrambling.
And yes, physicians do get stuck paying. Not because they were reckless clinicians. Because they were careless readers.
Where the hidden costs live: contract terms that quietly shift the burden to you
This is where people get burned: the contract quietly assigns tail responsibility, and nobody talks about it during the happy phase of recruiting.
You need to find the exact clause that answers one question: Who pays for tail coverage when the employment relationship ends?
Possible answers include:
- Employer pays
- Group practice pays
- Physician pays
- Shared responsibility
- Conditional responsibility based on why you leave
That last one catches a lot of people. Your obligation may change depending on the trigger. Watch for these common separation events:
- Resignation
- Nonrenewal
- Termination without cause
- Termination for cause
- Retirement
- Disability
- Switching insurers or group structure
Some contracts are generous if the employer terminates you without cause but punishing if you resign. Others split costs if you leave before a certain number of years. Some offer employer-paid tail only after partnership. Until then, it's your problem.
Red-flag phrases should make you stop immediately:
- "Employee shall be responsible for tail coverage"
- "Tail expense shall be shared by the parties"
- "Coverage subject to policy terms"
- "Employer may, in its discretion..."
- Any clause that never clearly names the payer
Vague language is not neutral. It favors the party with more power later. Usually not you.
And don't get cute with compensation math. I've heard physicians say, "It's fine, the signing bonus will cover it," or "My productivity check at year-end should absorb it." That's wishful thinking. Hidden insurance obligations have a nasty habit of outrunning the nice-looking bonus you were mentally spending six months ago.
If the contract says you pay, estimate that cost before signing. If the contract is vague, treat that vagueness as a financial liability. Because that's what it is.
How to compare tail coverage without getting blindsided
Don't compare tail coverage the lazy way. This is not just "quote A is cheaper than quote B." That's how people miss exclusions, deadlines, and reporting limitations that matter more than the sticker price.
Start by gathering options. Depending on your situation, you may be able to get information or quotes from:
- The current insurer
- A malpractice broker
- Your employer or group practice
- A new employer offering nose coverage or another transition arrangement
- Any party offering to contribute to the cost
Then compare the details that actually matter.
1. Confirm the reporting window
This is the whole point of tail. How long can claims be reported for prior acts?
Look for whether the extended reporting period is:
- Unlimited
- Limited to a set number of years
- Restricted by claim type or policy language
Unlimited reporting is cleaner. Limited reporting can still be useful, but don't assume it protects you forever.
2. Check what prior acts are actually covered
Some tail arrangements apply broadly to covered services performed during the original policy period. Others may be narrower than you expect. You want to know:
- Which dates of service are covered
- Whether all professional activities under the old role are included
- Whether moonlighting, supervisory duties, telemedicine, or procedural work are excluded
This is where physicians get caught by details they brushed past. If your old work included multiple settings or mixed duties, don't assume one line item covers all of it.
3. Compare timing requirements
A lot of contracts and policies impose deadlines. Miss the window and the option may disappear.
Ask directly:
- Must the tail be purchased immediately on separation?
- Is there a 30-day, 60-day, or 90-day election window?
- Does coverage only matter if a claim is later reported?
- Can the right to purchase tail expire automatically?
I've seen people give notice, get busy with credentialing and relocation, and miss a short purchase window. Brutal mistake. Administrative chaos is not a defense.
4. Weigh the cost against what you're walking away with
A "moderate" hidden cost can wipe out real compensation. Don't evaluate tail in isolation. Put it next to:
- Your final months of salary
- Any retention or productivity incentives
- Relocation reimbursement clawbacks
- Unused PTO payout rules
- Signing bonus repayment obligations
Sometimes a job change that looks financially smart gets much less attractive once tail exposure is added in.
5. Put the quotes into a side-by-side framework
Use a scorecard. Not memory. Not a few notes on your phone.
A practical checklist for each option:
- Who pays?
- Total cost?
- Unlimited or limited reporting?
- Exact prior acts covered?
- Election deadline?
- Any exclusions?
- Written confirmation attached?
If one option is cheaper but vague, that's not the better option. That's just cheaper uncertainty. And uncertainty in malpractice coverage is a terrible bargain.
Red flags, negotiation moves, and when to get expert help
Some contracts practically announce that they're trying to slide this past you.
Here are the red flags I take seriously:
- Premiums that seem suspiciously cheap
- No policy attached
- Undefined terms like "standard tail"
- References to coverage being "subject to policy terms" without giving you those terms
- Contradictory language between the offer letter and employment agreement
- Silence on what happens if the practice changes carriers
Cheap isn't always good. Sometimes it just means the protection is thinner, narrower, or dumped onto you later.
Now the negotiation part. Yes, you should negotiate this. People act embarrassed about pushing on tail, then happily negotiate salary to the last detail. Backwards. Tail can hurt more.
Reasonable asks include:
- Employer-paid tail coverage
- Shared-cost arrangement
- Reduced physician responsibility after a certain number of years
- A sunset clause where your obligation declines over time
- Employer-paid tail if they terminate without cause
- Clear language that names the payer and timing
If you hear, "Don't worry, we always work it out," stop. No. Get it in writing.
Bring in expert help early, especially if:
- You're signing your first attending contract
- The policy is claims-made and the clause is vague
- The practice uses complicated compensation or partnership tracks
- You're about to give notice
- You're comparing multiple offers with different insurance structures
The right experts:
- Malpractice broker for policy structure and quote comparisons
- Healthcare attorney for contract language and legal exposure
- Contract advisor for overall negotiation strategy
This is not overkill. It's cleanup prevention. Much cheaper than regret.
A simple comparison framework you can use before you sign
Use this before you sign anything. Every time.
Tail coverage pre-signing checklist
Identify the policy type
- Occurrence or claims-made?
- If claims-made, assume tail is an issue until proven otherwise.
Locate the tail clause
- Don't stop at "malpractice provided."
- Find the exact separation language.
Confirm who pays
- Employer, physician, or shared?
- If it's vague, treat it as your risk until clarified in writing.
Estimate the cost
- Don't sign blind.
- Get a realistic estimate before you commit.
Verify the reporting window
- Unlimited is different from limited.
- Read the details.
Check deadlines
- When must tail be elected or purchased?
- Put the date on your calendar.
Compare at least three scenarios
- Employer-paid tail
- Physician-paid tail
- Shared-cost arrangement
Get all promises in writing
- Offer letter
- Employment agreement
- Policy or endorsement details
The fast decision rule is this: if the clause is vague, it is bad until fixed. Don't romanticize ambiguity. It won't save you later.
Tail coverage isn't a last-week resignation problem. It's a signing-day problem. Handle it then, when you still have leverage.
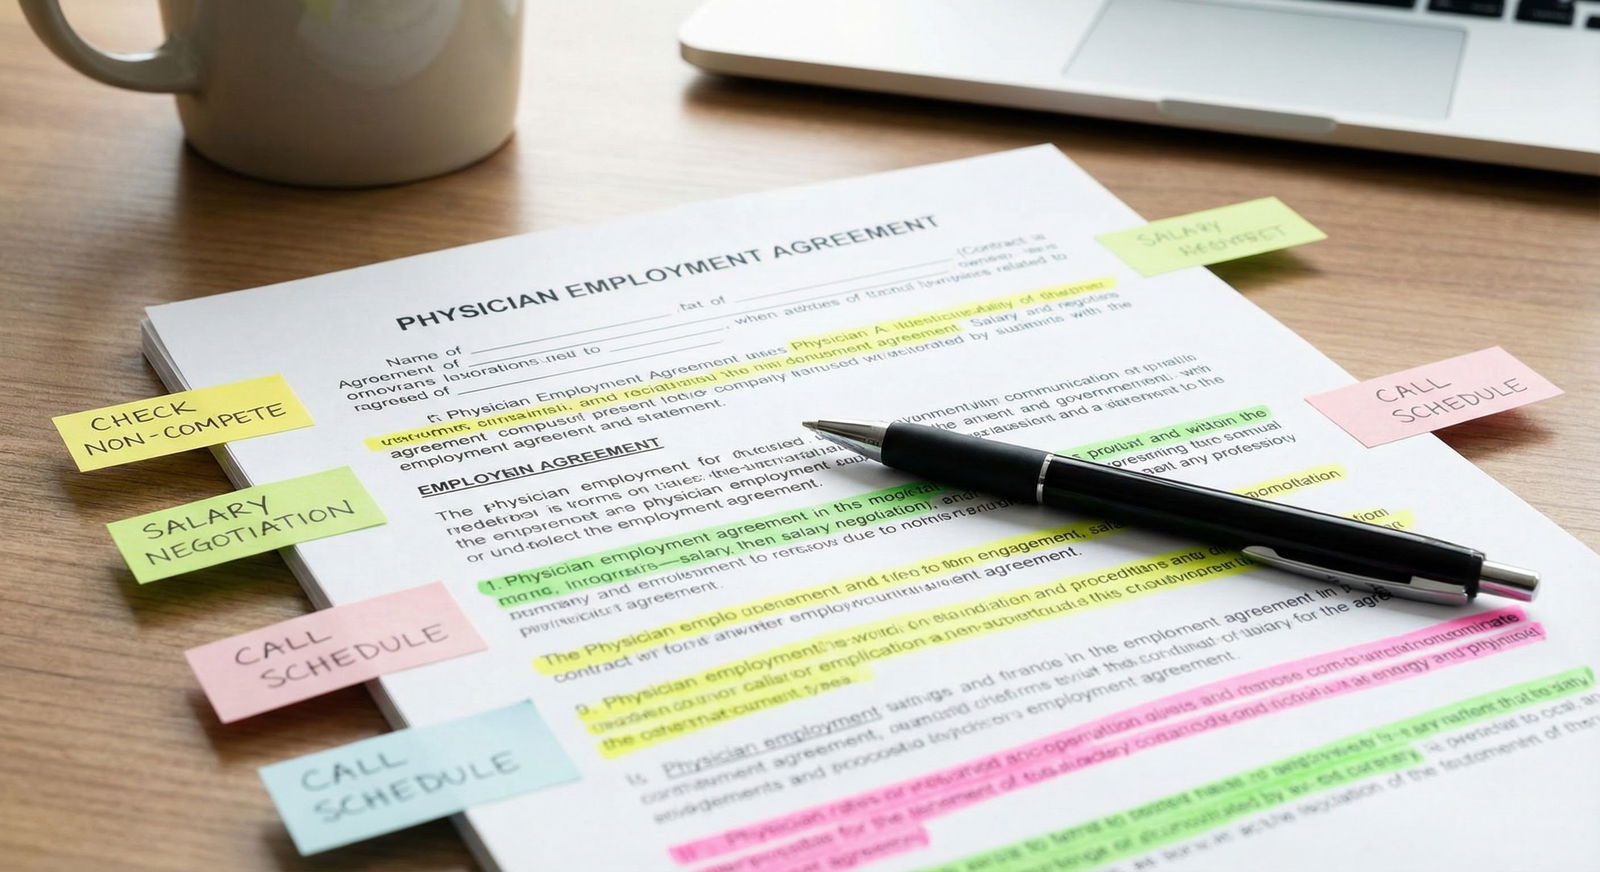
Tail coverage is one of those contract details people ignore because it feels distant and boring. Until it isn't. Don't make that mistake. Know the policy type, find the tail clause, confirm the payer, estimate the cost, and lock down deadlines in writing. If anything is unclear, assume risk and escalate before signing. That's the safe move. The smart move. The professional move.