Moving for residency is a massive life event. You're packing up your life, saying goodbye to friends, and preparing for 80-hour work weeks. But amidst the chaos, most residents completely ignore a critical financial detail: state taxes.
Here is the reality. Your residency stipend is modest. When you move from a zero-percent income tax state like Texas to a high-tax state like New York or California, that identical stipend suddenly buys a lot less. State income tax variance is brutal. If you don't strategize, you're just handing over money you actually need for rent and ramen. Let's fix that.
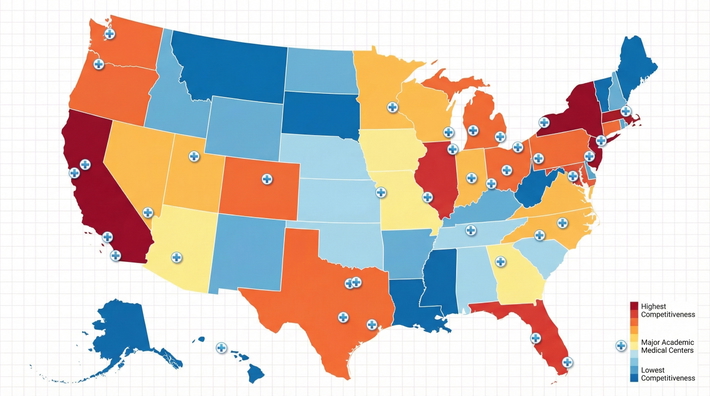
Before finalizing your plan, it is helpful to understand which factors matter most when comparing residency regions to ensure you aren't sacrificing long-term goals for short-term tax convenience.
The following information is for educational purposes only. It is not financial advice, not legal advice, and not tax advice. Because individual circumstances and state laws differ, figures vary, so always consult a qualified professional before making final tax decisions.
1. Understanding Residency vs. Domicile
State tax residency isn't about where your parents live. It's not about where you are registered to vote. It is about where you physically live and where you intend to remain.
If you are concerned about your financial future, what older attendings regret about taxes they ignored in residency can serve as a vital cautionary tale to guide your current decisions.
Most states use the 183-day rule. If you spend more than half the year (183 days) in a state, you are a statutory resident for tax purposes. Period. But it gets trickier during your transition. The exact date you arrive in your new state matters immensely. If you fly in on June 30th and start working July 1st, your physical presence clock starts immediately.
You also need to understand "domicile." Your domicile is your permanent home. You can only have one domicile at a time. If you move to a new state for residency but keep your driver's license, car registration, and voter registration in your old state, the old state might argue you never actually abandoned your domicile. They will try to tax your income. Break ties with your old state cleanly and establish new ones immediately.
Before finalizing your cross-country plans, read more about post-match timeline logistics of moving cross-country to avoid common logistical pitfalls.
2. Reciprocity Agreements: The Hidden Benefit
Some states actually play nice with each other. These are called tax reciprocity agreements. If you live in one state but work in another (common in places like the DC/Maryland/Virginia corridor), reciprocity means you only pay income tax to the state where you live.
It is crucial to recognize the 7 costly relocation mistakes doctors make when choosing a new state to protect your long-term earnings.
If your new state and your old state have a reciprocity agreement, you need to file a specific exemption form with your hospital's payroll department. Do this on day one. If you don't, they will withhold taxes for both states, and you'll be fighting for a refund come April.
What if there is no reciprocity? You aren't entirely out of luck. You'll use the "Credit for Taxes Paid to Other States." You file a non-resident return for the state where you worked and a resident return for the state where you live. Your home state will give you a credit for the taxes you paid to the work state so you aren't double-taxed. It's a paperwork headache, but it keeps you out of tax jail.
3. Deductions and Moving Expenses
Let me save you some time: federal moving expense deductions are mostly dead. The Tax Cuts and Jobs Act (TCJA) suspended the moving expense deduction for almost everyone except active-duty military. You cannot deduct the cost of the U-Haul, the gas, or the hotel stays on your federal return.
Don't throw away your receipts just yet, though. You need to check local laws. A handful of states still allow a state-level moving expense deduction on their specific tax returns. California, for instance, still conforms to the older federal rules for this specific deduction. If your new state allows it, those U-Haul receipts just saved you a few hundred bucks. Keep them in a dedicated folder just in case.
4. State Income Tax vs. Cost of Living
Residents obsess over their gross salary. Big mistake. You need to obsess over your net take-home pay.
A $65,000 stipend in a high-tax, high-cost-of-living area like San Francisco feels vastly different than a $65,000 stipend in a no-income-tax, lower-cost area like Houston. When you are evaluating your budget, calculate your exact net income after federal, state, and local taxes. Don't forget local city taxes, either. Places like New York City and Philadelphia tack on their own municipal income taxes right on top of the state tax.
Your cash flow depends entirely on your payroll withholding settings. If you move to a high-tax state and your hospital payroll department accidentally leaves your withholding set to your old, low-tax state, you are going to get crushed with a massive tax bill in April. Verify your withholdings on your first paycheck.
5. Filing as a Part-Year Resident
If you moved mid-year, you are a part-year resident. This means you have to file two state tax returns. You will apportion your income based on exactly when you lived in each state.
This is where residents make the most errors. They guess their move date. They use the date they signed their lease instead of the date they actually slept in the apartment. Use the exact date you established physical presence.
You need hard documentation to back this up. State tax auditors love to scrutinize part-year returns. Have your old lease termination document, your new lease start date, your flight itineraries, and your first utility bill ready to go. If you claim you moved to Florida on December 28th to avoid New York taxes, the auditor will ask for proof. Have it ready.
6. The Impact of Moonlighting Income
Picking up extra shifts is a great way to pay down debt. It's also a great way to trigger an IRS audit if you aren't careful.
Moonlighting income usually comes in two forms: W-2 or 1099. If it's W-2, the taxes are withheld, and it's treated just like your residency income. If it's 1099 (independent contractor), you are now a sole proprietor. You owe self-employment tax (15.3%) on top of your regular income tax.
If you moonlight in a different state than your residency, you just opened a multi-state tax can of worms. You must allocate your 1099 income to the state where the work was physically performed. Because no taxes are withheld from 1099 income, you need to make quarterly estimated tax payments. If you don't, the underpayment penalties will eat up your extra moonlighting profits.
7. Keeping Records for the IRS and State Departments
Do not rely on your memory. You are working 80 hours a week; you won't remember the exact date you transferred your car registration eight months from now.
Create a "move file." This is a dedicated physical or digital folder specifically for your relocation. Organize it by timeline. Include your move dates, your final paystubs from your old job, your first paystubs from your new job, and confirmation emails for your new driver's license and voter registration.
Digital storage is fine, but make sure it's backed up. A simple cloud folder named "Residency Move Tax Docs" works perfectly. When April rolls around, you just hand this folder to your CPA or upload it to your tax software. It turns a weekend-long nightmare of digging through emails into a 30-minute filing session.
Start Strong
Your tax structure needs to be set up in month one. Go to your hospital's payroll department during orientation and update your W-4 and state withholding forms immediately. Don't guess on the forms. If your situation involves moonlighting, part-year moves across three states, or a spouse with complex income, don't use cheap tax software. Hire a CPA who specializes in physician and resident taxes. Take control of your finances right now so you can actually focus on learning medicine during your busy rotation months.